
You can access both of our platforms from a single Saxo account.

Why Defense is creeping into “core portfolio” conversations
Key points:
- The big shift: Defense is no longer a “headline trade”. Early 2026 is showing it is becoming a standing line item when tensions flare in more than one region from US-Venezuela, to Greenland to China-Japan and others at the same time.
- Spending is rising, but the rules are tightening: Europe is trying to lock in a multi-year plan, while the US is signalling “deliver first” — which can create winners and losers within defense, not just lift the whole sector.
- AI is changing what ‘defense’ means: Budgets are moving from only big platforms to information advantage (drones, sensors, networks, software).
Why defense is being discussed as “part of all portfolios”
Defense sits at the intersection of three forces that matter for long-term investing:
- Geopolitics has reset the baseline. Early 2026 has already delivered multiple pressure points at once — US action in Venezuela, renewed focus on Greenland and the Arctic, and sharper Japan–China tensions.
- Europe is trying to turn urgency into a multi-year plan. NATO’s new spending commitment matters because it pushes defense from “reaction” toward “roadmap,” even if progress will differ by country.
- AI is changing what defense looks like. The story is no longer only jets and ships. Increasingly, it is also sensors, secure networks, drones, and software that helps decisions happen faster.
Geopolitics is setting the tone early in 2026
The year has started with a reminder that national security issues are no longer “somewhere else” or “some other time.”
- In the US, the aftermath of the Venezuela operation has reinforced a mood of hard-power politics returning to the agenda.
- In Europe, leaders have publicly stressed that Greenland’s future is for Greenland and Denmark to decide, reflecting unease about Arctic strategy and sovereignty.
- In Asia, Japan–China tensions have sharpened, with China restricting exports of some dual-use items to Japan and Japan approving a record military budget (Reuters reported 9 trillion yen for the coming fiscal year).
This matters for investors because defense spending is often one of the first places governments try to “do something visible”—even when other parts of the budget are under strain.
NATO has raised the bar on European defense spending
For years, the shorthand was “2% of GDP.” Now the direction is clearer.
NATO’s Hague Summit commitments point to 5% of GDP by 2035, with at least 3.5% aimed at core defense and up to 1.5% toward security-related areas like protecting infrastructure, networks, and resilience.
Chart 1: Military spending as a share of gross doemtic product, by country, 2024 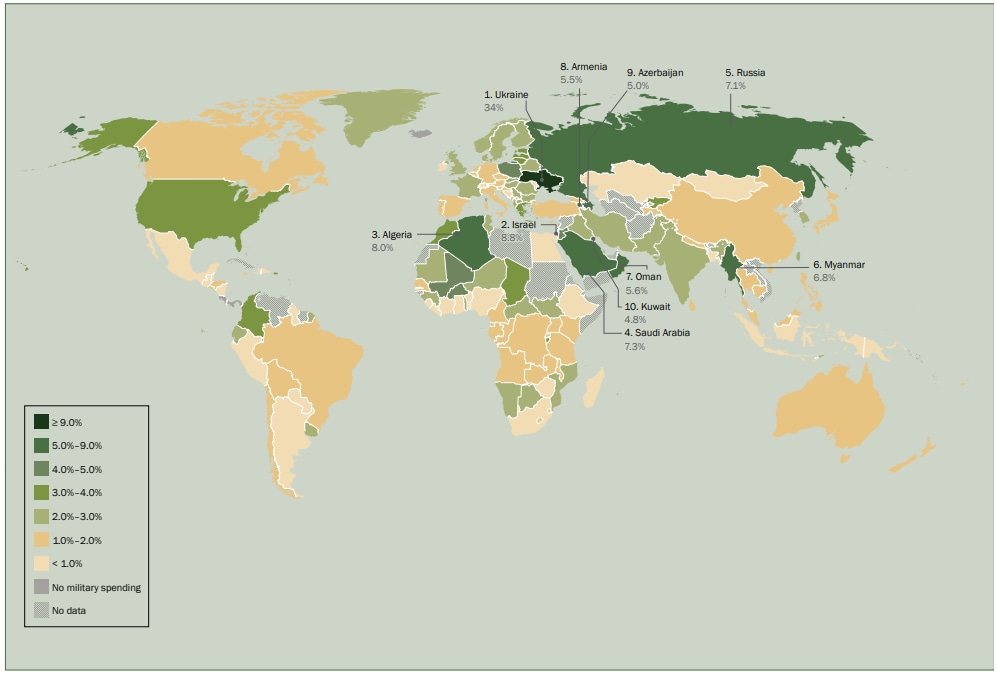 Source: SIPRI Military Expenditure Database, April 2025
What that signals for Europe
- Spending pressure is rising, even if the pace is uneven across countries.
- The definition is broader than “weapons only.” It includes security-related areas like infrastructure resilience and network protection.
- Europe will care more about local supply chains. That means not only buying equipment, but also building production capacity at home.
The US twist: bigger ambition, tougher rules
President Trump has called for a $1.5 trillion US military budget for 2027 (up from $901 billion for 2026), but he has also signalled tougher expectations for contractors, pushing them to prioritise delivery and production over shareholder payouts in cases of underperformance.
This means demand can rise, but the sector may face more political scrutiny. That can create more headline-driven swings, especially in companies tied to programs that are delayed or over budget.
AI is changing defense faster than most people think
AI’s impact is practical and near-term:
- More unmanned systems. Drones in the air and at sea can scale faster than traditional platforms.
- More sensing and tracking. Countries are spending more on satellites, radar, and detection.
- More secure connectivity. Communications and electronic systems must keep working under stress.
- More software. Tools that turn data into usable action are becoming more important.
But the risks are real: AI in security can become controversial quickly after accidents, misuse, or public backlash. That can slow projects, change rules, or redirect spending.
Mapping out the defense sector
1) Air and missile defense
This area is focused on protecting cities, bases, and critical infrastructure. It often includes sensors, air defense electronics, and command systems.
US: RTX, Lockheed Martin
Europe: Thales, Saab
What to watch: new orders, delivery timelines, and whether replenishment becomes a priority.
2) Weapon and ammunition manufacturing
This area matters when governments want to rebuild stockpiles and shorten delivery times.
Europe: Rheinmetall, BAE Systems
US (more indirect, but still relevant): General Dynamics
What to watch: production capacity expansion, availability of key components, and political pressure on pricing.
3) Space, surveillance, and secure communications
This is where the “AI and data” angle often shows up most clearly. It is about seeing, connecting, and coordinating faster.
US: Northrop Grumman (space and strategic systems exposure), L3Harris (communications and defense electronics), Palantir (software and data tools linked to defense use cases; often more volatile)
Europe: Leonardo (defense electronics and platforms), Thales (sensors, electronics, and security systems)
What to watch: government contracts that move from pilots to real deployment, and any sudden political pushback around surveillance or AI.
4) Shipbuilding and naval (“protect trade routes”)
This area supports maritime security, but projects can take longer and face delivery risk.
US: Huntington Ingalls (naval shipbuilding exposure), General Dynamics (submarine exposure via Electric Boat)
Europe: Rolls-Royce (defense propulsion exposure; not a pure-play defense company)
Risk note: capacity constraints and program delays are common here. The work can be large, but the timelines can be messy.
5) Japan
Japan has been on a path of higher security spending, and the investable names tend to reflect different parts of the ecosystem.
- Mitsubishi Heavy Industries — aerospace and defense programs, plus broader industrial capacity.
- IHI Corporation — defense and aerospace-related industrial exposure (including engines and heavy industry capabilities).
- NEC — communications, networks, and defense-related electronics and systems.
Risks investors should watch
- Fiscal pressure: higher defense ambitions collide with debt, interest costs, and competing domestic priorities. This can slow the pace or change what gets funded first.
- Policy risk: the US push to prioritise production over payouts can create sudden volatility in individual names.
- Execution risk: late delivery and cost overruns can hurt sentiment even when spending is rising.
- AI controversy risk: regulation and political scrutiny can arrive quickly after incidents.
This material is marketing content and should not be regarded as investment advice. Trading financial instruments carries risks and historic performance is not a guarantee of future results.
The instrument(s) referenced in this content may be issued by a partner, from whom Saxo receives promotional fees, payment or retrocessions. While Saxo may receive compensation from these partnerships, all content is created with the aim of providing clients with valuable information and options..
The instrument(s) referenced in this content may be issued by a partner, from whom Saxo receives promotional fees, payment or retrocessions. While Saxo may receive compensation from these partnerships, all content is created with the aim of providing clients with valuable information and options..