
You can access both of our platforms from a single Saxo account.

The front end emptied, the back end held - Options Brief - 5 October 2026
Summary: Payrolls cleared and the price of the next two days collapsed, while the price of the next year barely moved. The relief was local to the event, and the one extreme on the board never came down at all.
Payrolls was the week’s only scheduled event. With it gone, the option market stopped paying for the next two days.
MARKET REGIME: LOW VOL BULL | VIX 15.31 | TERM STRUCTURE: CONTANGO | SKEW: MID-RANGE (144.88) | FRONT-MONTH VIX FUTURES: 17.75
Key findings
- Ordered by tenor. VIX1D fell 22.31%, VIX9D 13.86%, the VIX 6.59%, VIX3M 3.07%, VIX6M 1.80% and VIX1Y 0.78%, each less than the one in front.
- The curve went back to normal, not an extreme. VIX3M to VIX is 1.176, its 60-session median, from 1.134.
- Rate volatility is the only extreme. MOVE at 107.30 beats 58 of those 60 against a median of 76.11; equity volatility is mid-range.
The September employment report missed. Payrolls came in at 29,000 against a 84,000 consensus, the prior two months were revised down by 60,000, and unemployment ticked up to 4.2% from 4.1%. The market cut the probability of a Federal Reserve hike at the October meeting to 20%.
The Federal Reserve is not of one mind on it. Vice Chair Bowman signalled no urgent need for further action, joining a growing group favouring a pause, while Dallas Fed president Logan held that rates need to rise another 50 basis points or more. Minutes land Wednesday.
Europe supplied the second strand. The euro fell to a new cycle low against the dollar, trading as low as 1.1161 this morning from a Friday close near 1.1255, on French fiscal concern and widening sovereign spreads. The German-French ten-year spread touched 159 basis points before ending Friday near 141.
- US (Friday 2 October close): The S&P 500 rose 0.73% to 7,722.72, the Nasdaq 100 1.00% to 30,807.93 for a record close, and the Dow 0.49% to 51,182.11. Breadth was narrow, the equal-weight index up 0.33%. Semiconductors led, the chip fund 2.07% and technology 1.01%. Tesla rose 4.65%, Nvidia 1.34% and Meta 0.30%.
- Europe: Friday was a partial recovery after a week weighed down by yields. The Stoxx Europe 600 gained 0.75% to 631.36, the DAX 1.17% to 25,231.20, the Euro Stoxx 50 1.02% to 6,238.51 and the CAC 40 0.79% to 7,897.19. On the week the Stoxx 600 lost 1.1% and the CAC 2.24%, its worst since April.
- Asia (Monday morning): Tokyo leads, the Nikkei 225 up 2.22% at 69,822.57 on semiconductor strength. The Hang Seng is little changed at 23,952.28. Mainland China and South Korea are shut, so nothing is quoted.
- Commodities and rates: Brent trades near 101.51, down 0.72%, after regaining 100 last week. Gold spot is near 4,140 against a Friday futures settle of 4,170.80; silver settled 1.82% higher at 61.52. The ten-year yield is 5.264%, the two-year 4.808% and the thirty-year 5.615%.
- Market regime: Low volatility bull: VIX 15.31, the cash curve in contango, twenty-day realised volatility 10.06% and stable, the index 0.85% above its fifty-day average.
Source: Saxo, Bloomberg, CBOE. Levels as of the 2 October close unless stated. Yield changes are derived from the prior session’s reading. Past performance is not indicative of future results.
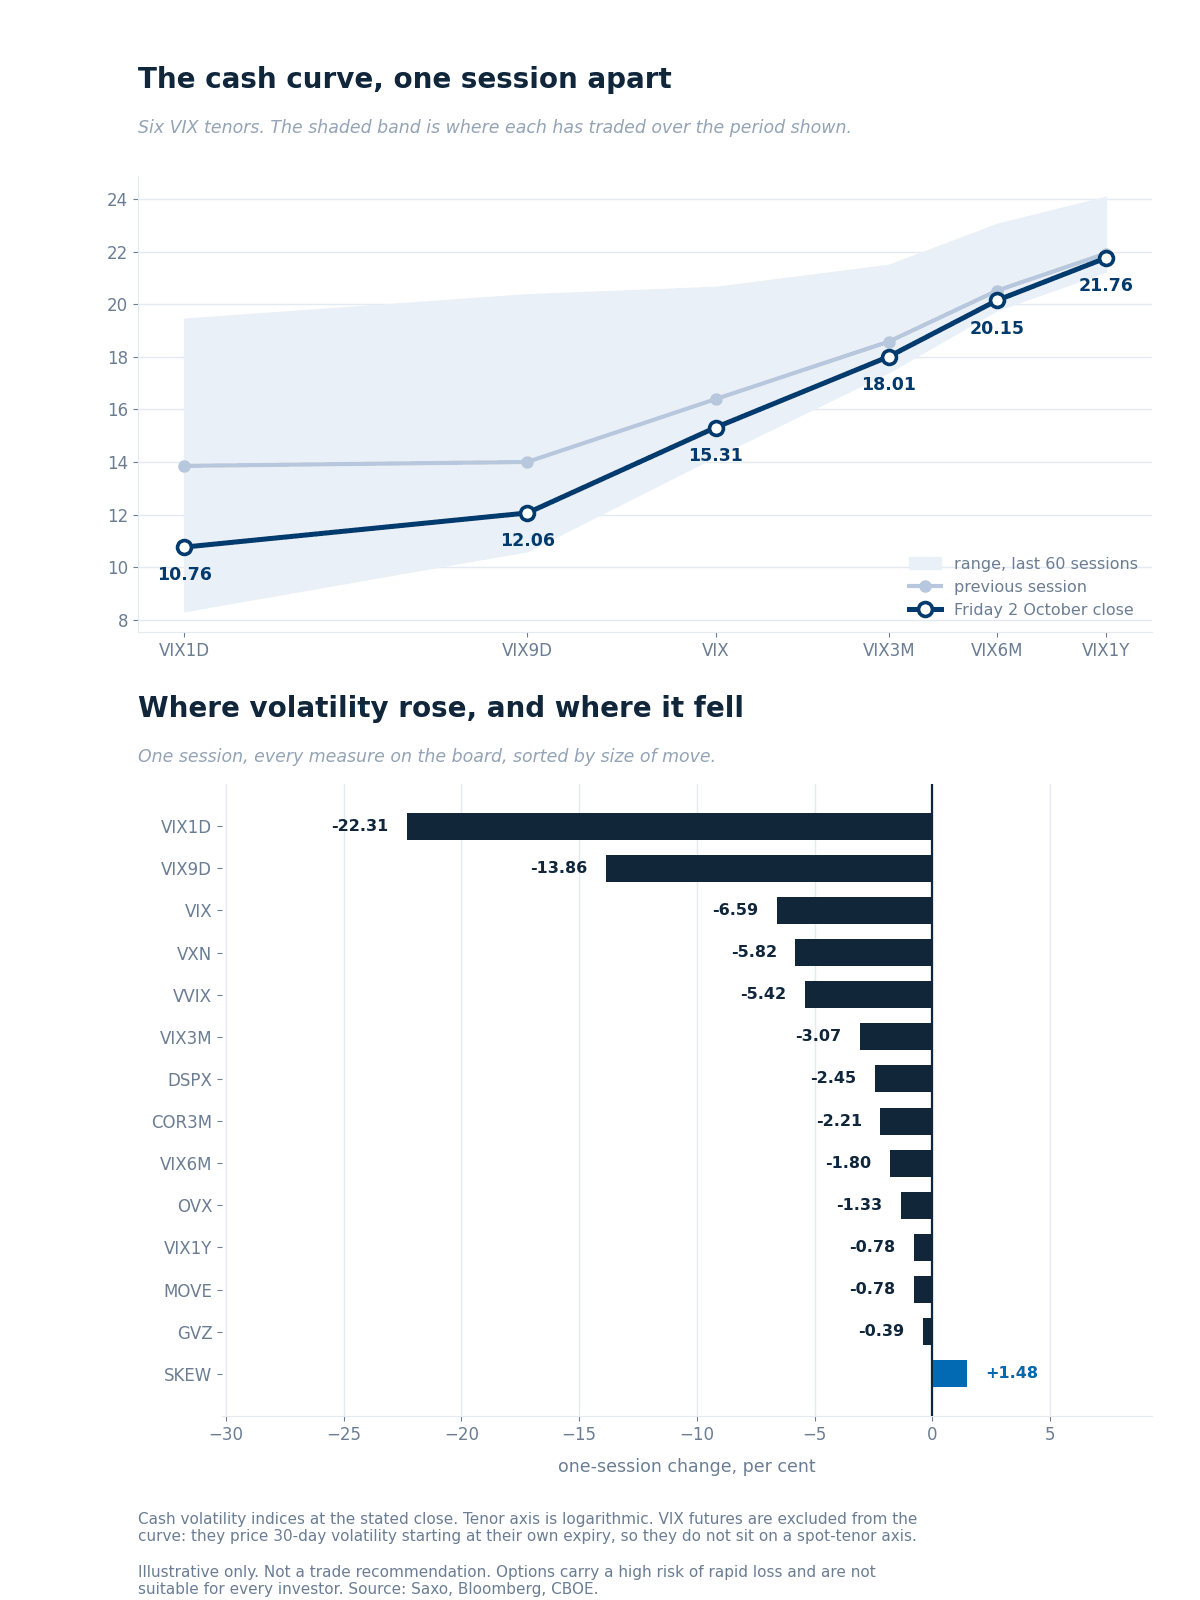 The six cash VIX tenors at Friday’s close against the prior session, over their 60-session ranges.
Reading the curve
- The whole curve fell, the front hardest. The near tenors sit low in their ranges, VIX9D tenth of our last 60 readings and VIX1D twenty-first, against the VIX at the twenty-fourth.
- Rates hold the only extreme. MOVE at 107.30 beats 58 of those 60 against a median of 76.11. Gold volatility at 23.23 is lower than all but three; oil 51.00.
- Ratios the graphic does not carry. VIX3M to VIX is 1.176, exactly its 60-session median, the Nasdaq-to-S&P ratio 1.385. SKEW rose 2.11 to 144.88, high against a long-run norm nearer 115 but within a tenth of a point of its own three-month median.
VIX futures
- The front contract is 17.75 and the second 18.40, a contango ratio of 0.965. The premium to spot widened to 2.36 from 1.69: spot fell 1.08, the October contract about 0.41.
- Parity puts the October forward at 17.67 and the November at 18.33, within 0.09 of each feed, so neither has rolled and the comparison holds. Neither sits in the graphic: both price thirty-day volatility from their own expiry.
Source: Saxo, Bloomberg, CBOE, 5 October 2026, approx. 06:00 CET. Past performance is not indicative of future results.
Saxo’s implied-volatility rank across 187 US and 334 euro-zone option underlyings, where 0 is a one-year low and 100 a high. Both universes held the same names across the two sessions, so the comparison is like for like.
- The typical name got cheaper, gently. The median US rank eased to 44.3 from 45.8 and median implied volatility to 32.37% from 32.96%; the euro-zone median fell to 45.1 from 47.1. Against the index measures that is a small move in the same direction.
- The distribution thinned at the top. The share of US names ranking above 70 fell to 10.2% from 11.8%, while the share below 20 rose to 17.6% from 15.0%.
- Rates and credit keep the top of the board. The long-bond fund holds 92.1 and the investment-grade credit fund 88.9, both near one-year percentile highs on single-digit and mid-teens implied volatility, which is the message MOVE carries.
- Health care is where single-name volatility is bid, taking six of the top twenty with Merck at 91.0, Danaher 89.1 and Thermo Fisher 88.4. The one rank extreme outside it is the Brazil fund at 100.0, into a presidential run-off on 25 October. See Saxo pricing for costs and charges.
Data source: Saxo, as of 5 October 2026, reflecting the 2 October close. Past performance is not indicative of future results.
Based on end-of-day 2 October, Friday’s positioning and not today’s price action.
The flow is neutral toward today’s reading and worth stating as such. Near-dated call supply was the one legible behaviour, but far tails were being sold rather than bought in several unrelated books, so the set does not support a story about distant protection getting dearer.
- Single-name flow had no net lean. Call premium dominated, yet the largest call lines were bid-side, crossed at mid, or legs of spreads and rolls; where an aggressor side resolves cleanly the buying was mostly in puts.
- Sector and ETF flow was structural rather than directional, built from two-sided volatility and financing trades. The exception was rates and credit, where duration upside was bought while credit protection stayed on. Named funds are market context only; see Saxo pricing for costs and charges on exchange-traded fund trades.
What the option market priced for this week, drawn around Friday’s close.
Expected move to Friday 9 October, drawn around the 2 October close with the nearest listed strike at each bound. Volatility uses the 21 October expiry, which is the next listed one. Read from the chain at Friday’s close, not a forecast.
- The week opens with none of it used, the cleanest read of the five. The index band runs 7,634.71 to 7,810.73, a 1.14% move either way, with the nearest listed strikes at 7635 and 7810.
- The ranking is the part worth keeping. The bitcoin fund is priced widest at 3.23%, then energy at 2.72% and the gold fund at 2.00%, against the Nasdaq 100 fund at 1.72% and the index at 1.14%.
- Volatility itself is priced for 12.76% either way to the October expiry, a band of 13.36 to 17.26 around 15.31. The upper bound sits almost exactly where the front future already trades.
- Options carry a high risk of rapid loss and are not suitable for every investor; see Saxo pricing for costs and charges.
The US cash session runs 15:30 CET to 22:00 CET. The calendar is almost bare: the September ISM services survey at 16:00 CET is the only US release of note, and there is little else before Wednesday’s Federal Reserve minutes.
That emptiness is the point for anyone reading the front of the curve. Today’s expiry settles at the 22:00 CET close with no scheduled event inside it. Earnings do not start in volume until Thursday, when PepsiCo, Fast Retailing, Progressive and Tesco report, followed by Delta Air Lines on Friday. Mainland China and South Korea stay shut. Future outcomes are uncertain and may result in losses.
- Session implied move. SPXW options price 39.25 points, or 0.51%, to tonight’s close and 87.70, or 1.14%, to Friday’s. Quotes before the open are indicative.
- What the clock did not explain. Friday’s expiry priced 88.10 points into Friday’s close and 87.70 now. No session has elapsed in between, so that 0.4 point is pure repricing: the week’s range is unchanged while the front collapsed.
- Tail risk signal. SKEW returned to its median while the VIX fell, and the front-month premium widened to 2.36 points. In our view the market may have let go of the event rather than repriced what sits behind it.
- Correlation read. Implied correlation at 11.48 beats 49 of 60 while dispersion at 34.70 sits at the twenty-third, and the typical single name carries implied volatility above 32% against an index at 15.31. In our assessment the index may be priced for calm the names are not.
The thing to watch is which end moves next. The front gave back a payrolls premium in one session with nothing on the calendar to replace it before Wednesday, so the near tenors are cheap because nothing is in them. What the week has not spent sits further out: rates volatility that never came down, correlation that stayed bid. Options carry a high risk of rapid loss.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it’s crucial to make informed decisions.
| More from the author |
|---|