
You can access both of our platforms from a single Saxo account.

Chips drag the index as correlation climbs - Options Brief - 16 November 2026
Summary: A few chipmakers pulled the S&P 500 lower on Friday while the equal-weighted index rose. Options now price stocks to move more as one block. Nvidia reports on Tuesday: will the rest of the market follow?
A handful of chipmakers pulled the S&P 500 lower on Friday while the equal-weighted index rose, and options now price stocks to move more together into Nvidia’s results.
MARKET REGIME: NEUTRAL / CHOP | VIX 19.30 | TERM STRUCTURE: CONTANGO | SKEW: ELEVATED (147.14) | FRONT-MONTH VIX FUTURES: 19.450
Today in brief
On Friday the largest companies counted for more than the typical one. The S&P 500 fell 0.40% to 7,561.67 and the Nasdaq 100 1.22%, yet the equal-weighted S&P 500, which gives every company the same say, rose 0.17%. Chipmakers led the fall: the semiconductor fund lost 2.99%, and AMD fell 8.8% and Broadcom 4.8%, according to the Saxo Market Quick Take.
Over the same session the option market priced stocks to move more together. Implied correlation, a gauge of how closely stocks are expected to move as one block, jumped 10.44% to 13.12. The one-day volatility gauge, which measures what options charge for protection over the next session, rose 16.51% to 18.63, almost level with the VIX at 19.30. In our view that may suggest traders expect the chip-led swings to spread into the wider index this week rather than stay contained.
In our view the week’s pricing may point the same way. Today’s expiry prices about 0.86% for the S&P 500 and the 20 November expiry about 1.78%, which leaves about 1.56% for the four sessions that hold Nvidia’s report on Tuesday. Time alone would have cut the 1.80% quoted for that expiry in Friday’s edition to about 1.64%, so in our view the market may have added premium over the weekend. Two readings may cut the other way: the price of Nvidia’s report day itself held at 7.7%, and the typical single name’s volatility rank eased to 29.4.
Backdrop: the index finished last week above its priced range, using 105% of it, and this week’s band is narrower at 1.78% against 2.39%. The large index funds’ volatility ranks rose while most single names fell, and the flow showed no readable direction. Fed Chair Warsh speaks at 18:00 CET.
That is the whole brief in one read. The sections below hold the detail behind each paragraph, with the charts, the full set of readings and the sources, for when you want to go deeper on one part.
Headline driver
US stocks fell on Friday as renewed selling in chipmakers weighed on Wall Street, according to the Saxo Market Quick Take. AMD dropped 8.8%, Broadcom 4.8% and Nvidia 2%, taking Nvidia’s weekly loss to 13% after its chief executive’s departure. The S&P 500 still gained 2.5% on the week, its first weekly gain in five.
Over the weekend the Quick Take reports that US Treasury Secretary Bessent called for an external shake-up at Nvidia’s top and a review of its compliance with export controls, while the FT reports that Jensen Huang is considering a return. Markets more than fully price a December rate hike, and Fed Chair Warsh speaks at 18:00 CET today. Iran launched drones at a US base in Bahrain, all intercepted, and Asian chipmakers led regional stocks lower this morning.
Market snapshot
- US (Friday 13 November close): S&P 500 7,561.67, down 0.40%. Nasdaq 100 27,943.74, down 1.22%. The Dow rose 0.10% to 52,353.24 and the equal-weighted S&P 500 0.17%. Small caps fell 0.32%, the semiconductor fund 2.99% and Nvidia 2.01% to 162.85.
- Europe (Friday close): the Stoxx 600 ended flat at 664.15, the DAX fell 0.08% to 26,749.95 and the FTSE 100 rose about 0.4% to its highest close since July.
- Asia (Monday, 05:00 CET): the Kospi was down 2.72% and the Hang Seng up 0.84%. Later in the morning the Quick Take has the Kospi down 3.6% and the Nikkei 2.4%.
- Commodities and rates: Brent traded at 94.91 and WTI at 88.25, with the Quick Take reporting Brent back near 96.6 after a 94.32 low. Gold futures traded at 3,880.0 and silver futures at 47.61, down 3.08%. The ten-year Treasury yield sat near 5.14%, the two-year near 4.86%, and the dollar near 159.65 yen.
- Market regime: neutral, with the VIX at 19.30, the curve in contango and SKEW at 147.14, below its 60-session median.
Index levels and volatility readings from the watchlist export taken at 05:00 CET on 16 November 2026, which carries Friday’s US and European closes and early Asian trading; chip moves, the FTSE 100, later Asian moves, Brent’s low and rebound, Treasury yields and policy context from the same-morning Saxo Market Quick Take. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
Volatility surface
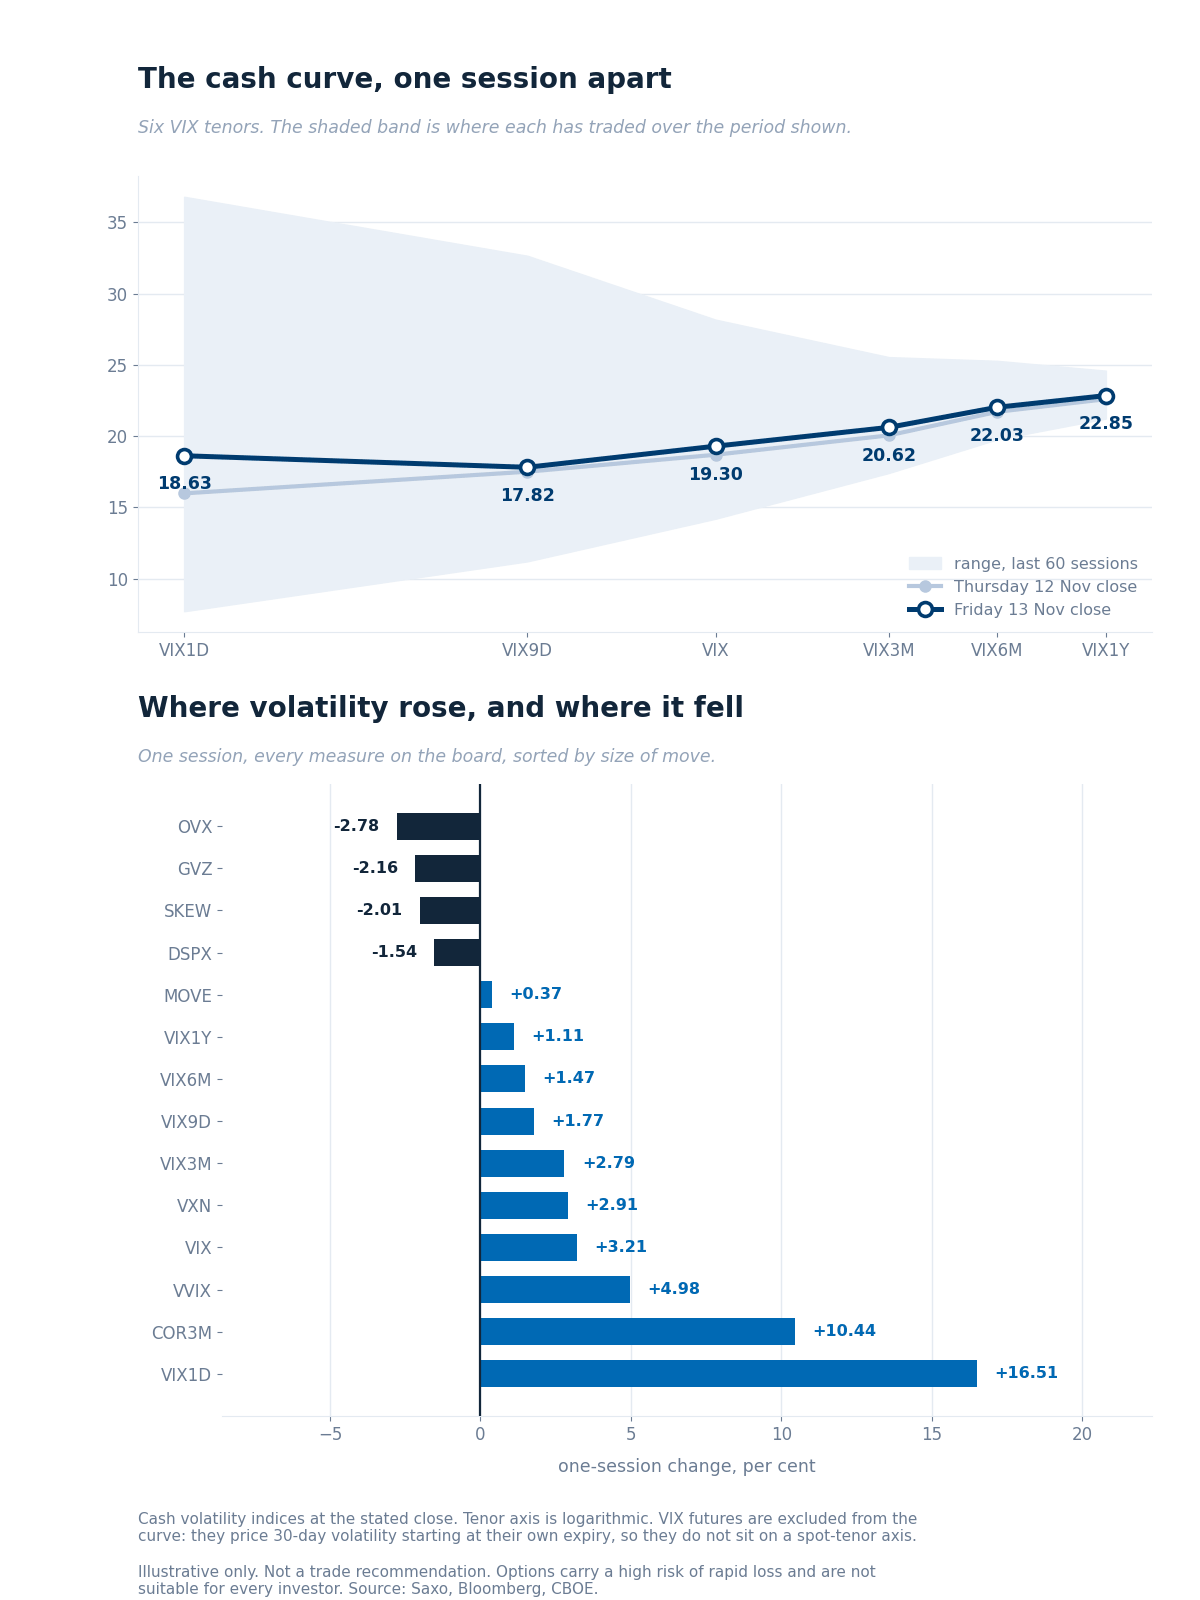
The cash curve at Friday’s close against Thursday’s, over each tenor’s 60-session range, with the one-session change across every measure. Illustrative only. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
The front of the curve rose most. The one-day gauge gained 16.51% to 18.63, almost level with the VIX, which rose 3.21% to 19.30, while the nine-day stayed below both at 17.82. Further out the rises were smaller, 2.79% for the three-month and 1.11% for the one-year. VVIX, the volatility of the VIX, rose 4.98% to 101.53. MOVE, the Treasury volatility gauge, edged up 0.37% to 98.78. VIX futures stay off the chart, since each prices a month from its own expiry.
Ratios. VIX3M/VIX held at 1.07. VXN/VIX eased to 1.52 from 1.53, with Nasdaq volatility up 2.91% to 29.38.
VIX futures. November trades at 19.45 and December at 20.15. A parity check on the 18 November options reads 19.44, in line with the feed, against 18.68 on Thursday’s quotes for the same contract.
Tails and correlation. SKEW fell 2.01% to 147.14, below its 60-session median of 149.22. Implied correlation, a gauge of how closely stocks are expected to move together, jumped 10.44% to 13.12, above its 60-session median of 11.71, while the dispersion index fell 1.54% to 38.42.
Single-name volatility
The typical single name’s volatility eased, but not where the index weight sits. On a common set of 522 underlyings the median implied-volatility rank fell to 29.4 from 31.3, with 345 names down and 172 up, and 13 names at a rank of 80 or more. The US median eased to 38.6 from 39.1 and the euro-zone median to 25.0 from 25.4.
The index measures above rose, and so did the large index funds. The Nasdaq 100 fund’s rank rose to 60.0 from 56.4, the semiconductor fund to 63.4 from 59.9 and the S&P 500 fund to 27.2 from 25.5, while the small-cap fund eased to 17.7. Among the chipmakers, Broadcom rose to 79.8 from 74.2 and AMD to 54.7 from 49.1, while Nvidia held near the top of its year at 92.9, at the 98.8th percentile. Microsoft fell to 31.0 from 35.6 and Tesla to 42.7 from 46.9. Home Depot, which reports on Tuesday, rose to 71.3.
Implied-volatility rank from the Saxo screener, read at about 03:00 CET on 14 November 2026, carrying Friday’s close, against the reading carrying Thursday’s close. Source: Saxo.
Options flow sentiment
Based on end-of-day Friday 13 November, yesterday’s positioning, not today’s price action.
- Single-name flow was mixed, with most large positions in the biggest technology names crossed in paired packages with no clear buyer or seller.
- Sector and ETF flow showed no readable direction and no demand for tail protection on the index.
Where the week's range sits
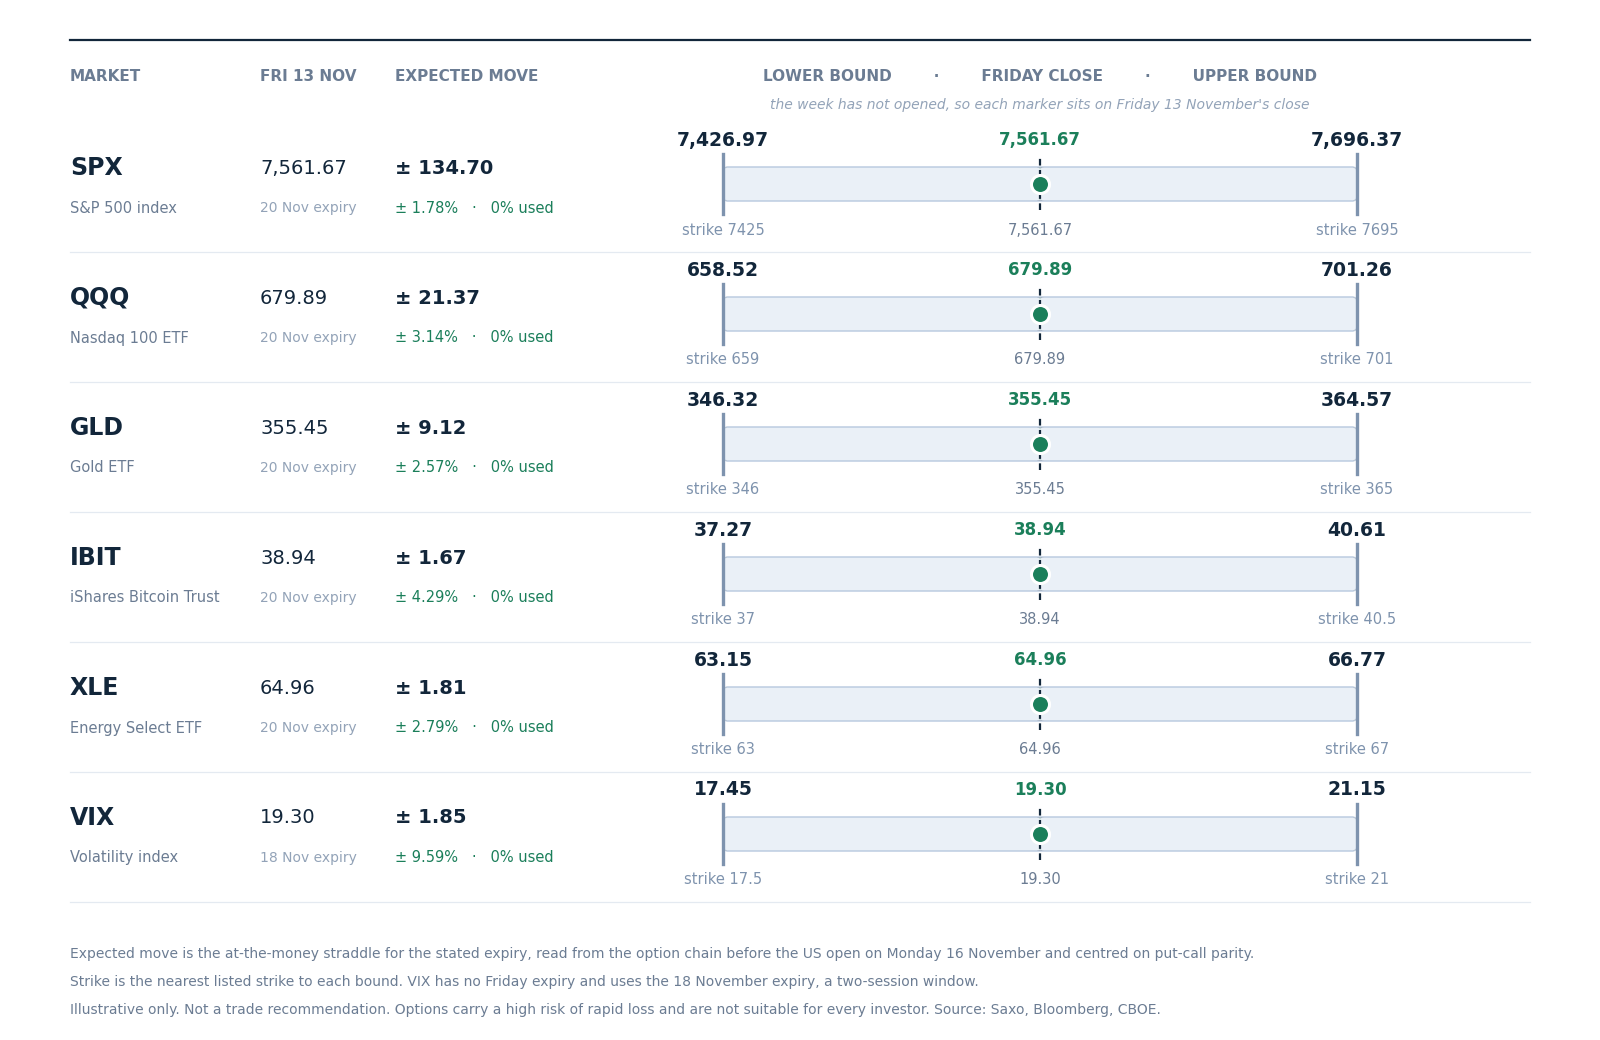
The range the option market priced for this week around Friday 13 November’s close. The week has not opened, so each marker sits on Friday’s close. Illustrative only, not a trade recommendation. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
The S&P 500 starts the week with 134.70 points priced around Friday’s 7,561.67 close, 1.78%, from 7,426.97 to 7,696.37. Last week’s band was 2.39%, so the market prices a narrower week, though one that holds Nvidia’s report. The Friday-close reading did not run, so this week’s ranges were read from the option chain before the US open.
Last week the index finished above its upper bound of 7,552.91, using 105% of its range. This week the bitcoin fund is the only market priced wider than a week ago, at 4.29%. The Nasdaq 100 fund carries 3.14% and the energy fund 2.79%. The VIX row uses the 18 November expiry, so it measures two sessions rather than five.
Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you.
Today's catalysts
- Today: 11:00 CET euro-zone industrial production for September and Fed speaker Barr; 14:30 CET the New York Empire State manufacturing survey; 15:03 CET Fed voter Williams; 18:00 CET Fed Chair Warsh; 20:15 CET Fed voter Hammack.
- This week: US retail sales and industrial production on Tuesday, with Nvidia, Home Depot and Disney reporting; housing starts, the Fed minutes, Palo Alto Networks, TJX, Lowe’s and Target on Wednesday; Walmart and Intuit on Thursday.
Earnings scorecard
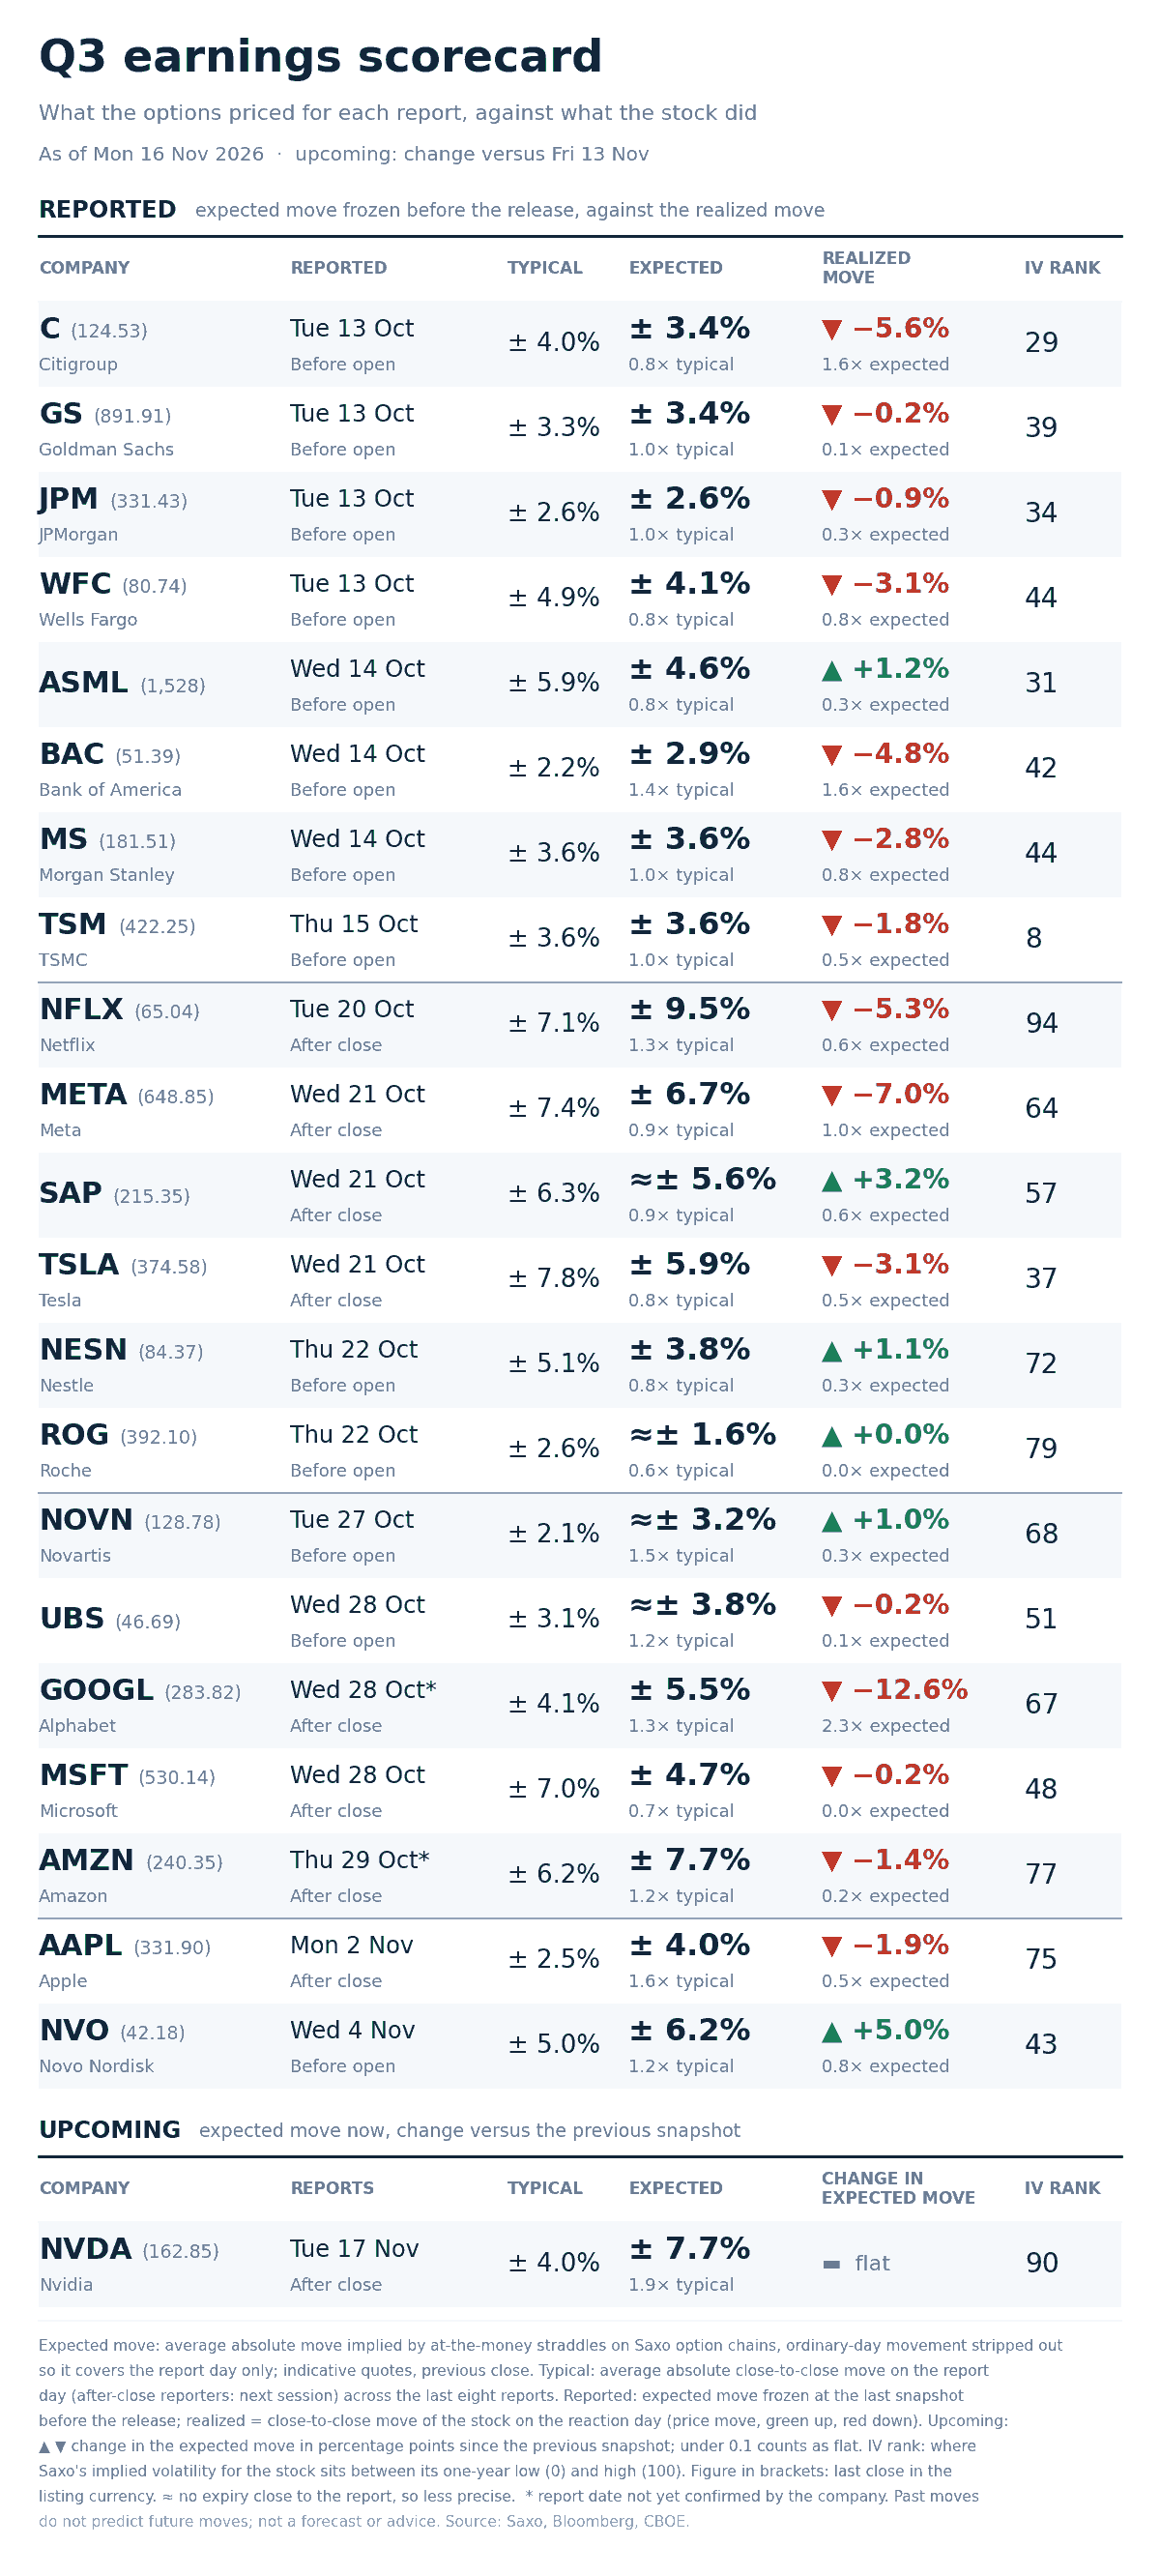
Option-implied expected move for each report day against the stock’s average move after its last eight reports, across the twenty-two names tracked this season. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
Nvidia is the one name on the scorecard still to report, on Tuesday after the close. Its options price a report-day move of about 7.7%, 1.9 times the 4.0% it has moved on average after its last eight reports, unchanged from Thursday. Its last four report-day moves were 3.1%, 5.5% and 1.8% lower and 8.7% higher.
In our view the contrast may matter again. Nvidia fell another 2.01% on Friday and the scorecard’s own rank reading, taken from this morning’s chain, stands near 90, yet the price of the report day itself did not move, which may suggest the extra premium is going into the sessions around the report rather than into the report.
The other twenty-one names have reported and their board is unchanged.
Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you. Past performance is not indicative of future results.
What the market is pricing
- Session implied range: S&P 500 options price about 0.86%, roughly 65 points, for today’s expiry, from indicative quotes read before the US open. The one-day gauge at 18.63 implies about 1.17%, a one-standard-deviation figure, a different measure from the expected move.
- Clock against price: Friday’s edition quoted 136.95 points, 1.80%, for the 20 November expiry with six sessions left. Time alone would have left about 125 points, roughly 1.64%, and it now prices 134.70 points, 1.78%, so in our view the market may have added premium over the weekend.
- Week ahead: netting out today leaves about 1.56% for the four sessions after it, which hold Nvidia’s report and the Fed minutes.
- Correlation read: implied correlation rose 10.44% while the dispersion index fell and Friday’s decline stayed narrow. In our view that may suggest the market is pricing the chip-led moves to spread across the index rather than stay contained.
In our view the first test may be Fed Chair Warsh at 18:00 CET, with Nvidia’s report on Tuesday the larger one for a market now priced to move more as one block. Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you. Past performance is not indicative of future results.
| More from the author |
|---|