
Access all our platforms from a single account.

Asia Market Quick Take – 15 May, 2026

Asia Market Quick Take – 15 May, 2026
Key points:
- Macro: Retails sales in line at 0.5%; Initial jobless claims at 211k vs 205k
- Equities: Equity futures new high for 2nd straight day
- FX: USD strengthens following constructive Trump-Xi Summit
- Commodities: Oil looking to close for 7% gain for the week
- Fixed income: US 2Y yields highest since June 2025
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Kevin Warsh was confirmed as the new Federal Reserve chair, with bond markets already repricing higher and raising interest rates ahead of his tenure.
- US retail sales rose 0.5% month-on-month in April 2026, in line with forecasts, after a downwardly revised 1.6% gain in March. Gasoline stations led with a 2.8% increase amid higher fuel prices; excluding gas stations, sales were up 0.3%. Core retail sales (excluding food services, autos, building materials, and gas) also climbed 0.5%, slightly above expectations of 0.4%.
- Japan’s producer prices rose 4.9% year-on-year in April 2026, the fastest since May 2023 and above the 3% forecast, driven by higher energy-related costs linked to Iran war–related disruptions. On the month, PPI jumped 2.3%, up from 1% in March and the strongest increase since April 2014.
- Major resignations are intensifying a leadership challenge to UK PM Keir Starmer after Labour’s local-election losses, with MP Josh Simons stepping aside for Andy Burnham and Health Secretary Wes Streeting quitting to position for PM; Angela Rayner was cleared in a tax probe, potentially enabling a bid. BoE’s Sarah Breeden said the Middle East conflict is unlikely to spark a 2022-style inflation surge, while UK GDP grew 0.6% in Q1 and 1.1% year-on-year.
- US jobless claims rose by 12,000 to 211,000 in the first week of May, above forecasts of 205,000. Continuing claims increased by 24,000 to 1.782 million, slightly below expectations, but both measures remain below last year’s averages, signaling a still-strong labor market. Claims by federal employees fell by 46 to 392.
Equities:
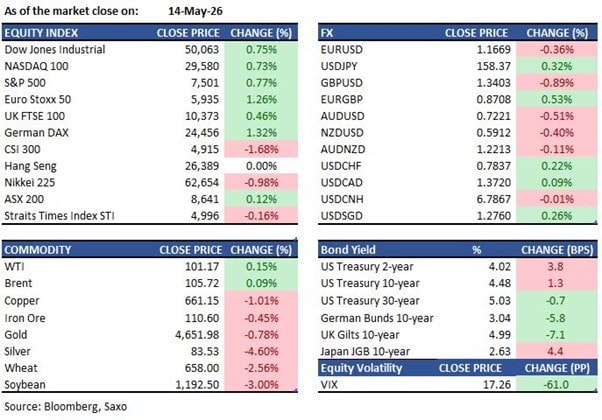
- US: The S&P 500 climbed 0.8% to 7,501.24, setting an all-time high for a second straight day after retail sales showed signs of consumer strength despite war-driven energy costs. The Dow Jones Industrial Average rose 370 points or 0.8% to close above 50,000 for the first time since the Iran war began, boosted by Cisco Systems which surged 13% on blockbuster earnings. Cerebras Systems surged 68% on debut after a $5.5bn IPO, valuing it at about $67bn ($83bn fully diluted). Trump says China agreed to buy 200 Boeing jets—its first US-made purchase in nearly a decade—but the deal is well below earlier talk of up to 500 737 MAXs plus widebodies. The Nasdaq 100 gained 0.7% to a new record. Nvidia continued its meteoric rise after US/ China announced resumption of chip sales to China, extending gains toward an unprecedented $6 trillion market capitalization. In after-hours trading, Applied Materials jumped 2.7% after giving sales and profit forecasts far above analysts' estimates, while Figma rose 12% to $22.69 on raised outlook.
- EU: The Stoxx Europe 600 Index rose 0.8% to 616.04, advancing for a second straight day with technology shares leading gains. ASML Holding climbed 3.0% on the back of better-than-expected results from Cisco Systems in the US. Siemens rallied 2.6% after agreeing to acquire several businesses from Mer Mec. Germany's DAX jumped 1.3% or 319.45 points to 24,456.26, the largest one-day gain since May 6, with Infineon Technologies rising 5.8%. The FTSE 100 gained 0.5% or 47.58 points to 10,372.93 in London. France's CAC 40 rose 0.93% to 8,082.27, while the Euro Stoxx 50 climbed 1.26% to 5,934.96.
- Asia: Asian markets showed mixed performance on Thursday. South Korea's Kospi rose 1.8% to 7,981.41 at the close, rebounding from recent volatility as the index has surged 200% over the past year, far outpacing every other market globally. The rally has fueled speculative mania with locals borrowing record sums and trading volumes soaring to all-time highs. Japan's Nikkei fell 1.0% to 62,654.0 on Wednesday but futures indicated a 0.5% rise to 63,090 for Friday as AI enthusiasm continued. Hong Kong's Hang Seng and mainland Chinese benchmarks were mixed as investors monitored the Trump-Xi summit in Beijing. Singapore's Straits Times Index gained 1.2% or 57.96 points to finish at 5,003.96 on Wednesday, with Wilmar International leading gainers by rising 3.0%. Singapore Airlines’ net profit slumped 57% to S$1.18b, beating estimates, as losses at associates including Air India weighed; it flagged a cautious outlook amid Iran‑war risks.
Earnings this week:
- Friday: No major earnings expected
FX:
- The British pound fell 0.9% versus the dollar, down the most since February 5, dropping to 1.3436 per dollar, the lowest since April 13, after Manchester Mayor Andy Burnham said he's seeking to run for Parliament, potentially opening an avenue to challenge Prime Minister Keir Starmer.
- The Japanese yen weakened past 158 per dollar after a brief overnight rally, rising 1.1% for the week on track for its biggest weekly gain since March, keeping traders on alert for possible intervention by Japanese authorities.
- The offshore yuan advanced for an 11th straight session, marking its longest stretch of gains against the dollar since 2017, reaching 6.7816 per dollar, its strongest level since February 2023, as the Trump-Xi summit progressed with positive signs.
- The euro slid as resilient US sales data fueled a dollar rally, with further advances in US yields threatening a breakout to the downside for EURUSD.
- AUDGBP steady at 0.53899 after hitting a near three‑year high on sterling weakness amid UK political jitters (Burnham bids for Parliament).
Commodities:
- Oil headed for a weekly gain of almost 7%, with WTI edging toward $102 a barrel and Brent crude closing near $106, as the crucial Strait of Hormuz remains effectively closed with the US naval blockade of Iran's ports still in place.
- Gold headed for a modest weekly decline of 1.2% since last Friday, trading steady near $4,650 an ounce, as war-driven surge in US inflation fueled expectations for higher interest rates, with the dollar strengthening and 10-year Treasury yields jumping.
- Metals fell broadly, with LME tin, COMEX silver, and lithium carbonate dropping over 2%, while LME nickel, LME and SHFE copper also declined amid global market volatility.
Fixed income:
- The 30-year Treasury yield fell to 5.012%, snapping a three-day streak of rising yields, though it remained near the fourth highest level this year and off just 0.077 percentage points from its 52-week high of 5.089%.
- The 10-year Treasury yield was little changed at 4.468% after topping 4.5% earlier this week, with Treasuries trimming early gains as the market moved with oil prices and left yields near their highest levels of the year. US 2Y yield hits highest since June.
- Japanese government bond futures fell as much as 32 ticks to 128.37, tracking moves in US Treasuries, as external pressures built from climbing Treasury yields and renewed yen weakness.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.