
Access all our platforms from a single account.

Nine prints later: what Q2 earnings season taught us

Summary: Between 15 July and 3 August we published what the options market was charging for nine company earnings events, before any of them reported. All nine are now in. Four moved further than priced, five stayed inside, and implied volatility fell on every single one.
An implied move is a price, not a forecast. A season of results is the clearest way to see the difference.
Between 15 July and 3 August 2026 we ran a series of articles, each published a few days ahead of a company’s quarterly results. The method was the same every time. Take the option chain for the expiry that captures the print, add the at-the-money call and the at-the-money put, and read that combined straddle as what the market was charging for one uncertain evening.
Those numbers went out before the results were known, which makes this a test rather than a retrospective. Every figure below can be checked against an article that was already public.
Options carry a high risk of rapid loss and are not suitable for every investor.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it’s crucial to make informed decisions.
What was priced, and what happened
Each line shows the implied move published ahead of the report (below this article you can find the links to the original reports), the move the share actually made on the following session, and the ratio between them.
- Amazon – implied 8.16%, realised 15.32%, 1.88x
- Apple – implied 3.98%, realised 7.35%, 1.85x
- Microsoft – implied 8.40%, realised 15.51%, 1.85x
- Alphabet – implied 6.71%, realised 7.13%, 1.06x
- Meta – implied 8.26%, realised 7.95%, 0.96x
- Netflix – implied 8.08%, realised 7.26%, 0.90x
- Rheinmetall – implied 5.20%, realised 3.46%, 0.67x
- Disney – implied 6.66%, realised 3.65%, 0.55x
- Novo Nordisk – implied about 8%, realised 4.32%, 0.54x
Implied moves are the figures published ahead of each report, taken from the at-the-money straddle on the Saxo option chain, between one and ten days before the print rather than at the final close before it. Realised moves are the close before the report against the close after (Source: Saxo, as of 10 August 2026). Past performance is not indicative of future results.
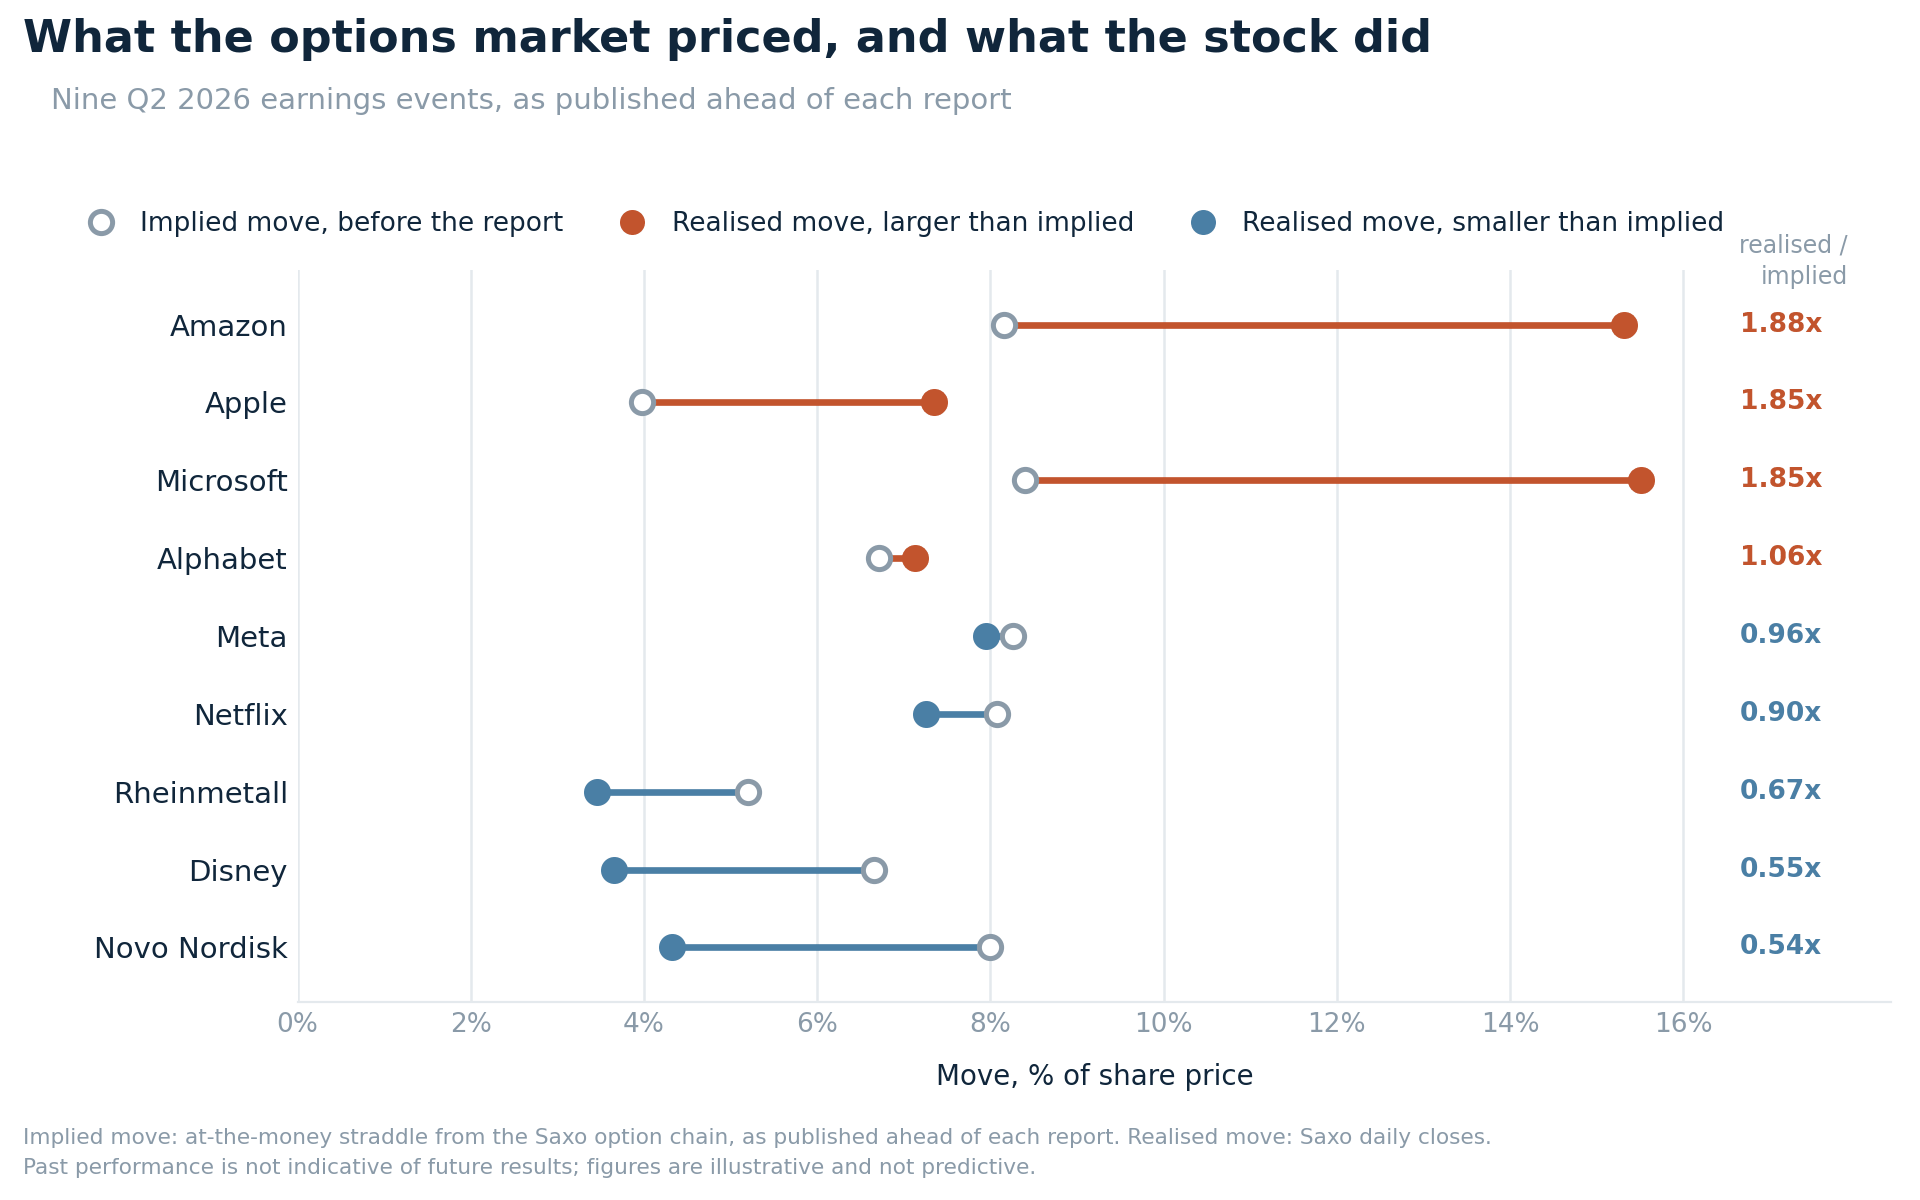 What the options market priced into nine Q2 2026 earnings events, and what each stock did the following session. Past performance is not indicative of future results; figures are illustrative and not predictive. Source: Saxo
Reading the table
Four moved further than priced. Five stayed inside. That is close to a coin flip, and in our view the closeness is the point rather than a disappointment.
Amazon, Apple and Microsoft all landed near 1.85x, so the market charged roughly half of what those events turned out to be worth. At the other end, Novo Nordisk, Disney and Rheinmetall came in near 0.55x to 0.67x, so buyers there paid for roughly twice the movement they got. Only Alphabet and Meta finished close to their own price, at 1.06x and 0.96x.
Almost nothing landed in the middle. The distribution has two clusters and a thin centre, which in our view is what an event premium looks like when it is doing its job: roughly right on average, unreliable in both directions on any individual name.
Strategy insight – what an implied move is for. The implied move is a clearing price for a single uncertain evening, and it carries no obligation to be right about any one of them. Treating it as a forecast is where the damage happens: selling premium into an event that lands at nearly twice the implied move can lose a multiple of the credit taken in, while buying premium into one that lands at half loses most of the debit paid. In our view it is better used as a hurdle, the level a directional view has to clear before a structure earns its place, than as an expectation of where the share will finish. Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply to each leg; see Saxo pricing for costs and applicable charges.
The one thing that behaved predictably
Direction was close to a coin flip across these nine. Implied volatility was not.
Composite 30-day implied volatility fell on every single name, from 7.9% on Apple to 33.2% on Netflix, with most of the group between 15% and 32% (Source: Barchart options-overview history, as of 10 August 2026). Netflix went from 53.99% to 36.06% overnight. Microsoft from 44.22% to 32.81%, on the same session it delivered its 15.51% move.
That last pair is the one worth dwelling on. A trader who owned Microsoft calls into the print was directionally right by a wide margin, and still had roughly a quarter of the volatility priced into those options removed from underneath them.
Worth being precise: a 30-day figure spreads the event premium across three weeks of ordinary time, so the collapse in the expiry containing the print is likely to have been larger. These numbers are a floor.
Strategy insight – vega before delta. When the fall in implied volatility is close to certain and the direction is not, in our view the decision about which side of vega a position sits on may matter more than the directional call, and neither side of it is safe. Long premium into a print carries a volatility drag that a correct directional view can still fail to overcome; short premium collects that drag while carrying the open-ended exposure that Microsoft and Amazon made real this quarter. Options carry a high risk of rapid loss and are not suitable for every investor, and costs and charges apply to each leg; see Saxo pricing for full details.
The four we could not measure
We previewed thirteen companies. Only nine appear above, and the reason matters more than the omission.
ASML and LVMH were covered in formats that never published an implied move, so there is no number to compare against. Intel’s figure was priced fourteen days before the print, so it carried two weeks of ordinary calendar time on top of the event and is not comparable to a one-day reaction. Shell’s came from an expiry twenty-nine days out, chosen because it straddled the report, which prices a month of movement rather than an evening.
Each measures something different from the other nine, and a comparison that quietly mixes measurements is worse than a smaller honest one.
What the wider market was doing
One piece of context that helps explain the spread. The Cboe S&P 500 Dispersion Index, ticker DSPX, measures how much index constituents move independently of one another. Through the reporting season it climbed to 50.40. By 10 August it had fallen back to 36.63 (Source: Cboe, as of 10 August 2026). Over the same stretch the VIX sat at 15.45, which on its own would describe an ordinary summer. Past performance is not indicative of future results.
Index volatility is broadly constituent volatility scaled by how much those constituents move together, so when dispersion is high, large single-name moves cancel at the index level instead of accumulating. A quiet index this season did not mean a quiet market, and anyone sizing single-name event risk off a headline volatility number was working from the wrong instrument.
Dispersion has since given back most of that rise, which is what you would expect once the events creating it are behind the market.
Final thoughts
The most useful thing here is what the exercise did not show. No pattern would have allowed a trader to sort the four expensive events from the five cheap ones beforehand. The biggest undershoots and overshoots were priced by the same mechanism within three weeks of each other, and nothing marked out which was which.
That is not a failure of the options market. In our view it is what a fair price looks like when the outcome is genuinely unknown: approximately right across many events, unreliable on any single one, and most dangerous to whoever mistakes it for a forecast.
Nvidia reports later this month. In our view the answer will be the one this season already gave: the implied move tells you what an event costs, not what it turns out to be worth. Options carry a high risk of rapid loss and are not suitable for every investor, and past performance is not indicative of future results.
The original articles
- 15 July 2026 – How to trade an earnings event with options: a Netflix case study
- 16 July 2026 – Before Alphabet reports: reading the expected move and structuring three views
- 23 July 2026 – Microsoft into earnings: where the expected move meets the moving averages
- 28 July 2026 – Amazon into earnings: choosing a structure when the move is already priced
- 28 July 2026 – Where the strikes go: a Meta earnings case study
- 29 July 2026 – Small move, big night: how the options market prices Apple earnings
- 31 July 2026 – Rheinmetall: how to use options on a share that costs EUR 1,139
- 3 August 2026 – Disney: high rank, cheap event
- 3 August 2026 – Selling the expected move: a Novo Nordisk earnings case study
Also previewed, and excluded from the list above for the reasons given: ASML (13 July), Intel (21 July), LVMH (22 July), Shell (24 July).
This content is marketing material and should not be regarded as investment advice. Trading financial instruments carries risks and historic performance is not a guarantee of future results.
The Author is permitted to wait at least 24 hours from the time of the publication before they trade the instruments themselves.
The author does not hold positions in any of the instruments mentioned in this article.
The instrument(s) referenced in this content may be issued by a partner, from whom Saxo receives promotional fees, payment or retrocessions. While Saxo may receive compensation from these partnerships, all content is created with the aim of providing clients with valuable information and options.
This content will not be changed or subject to review after publication.
| Related articles/content |
|---|
| Adyen earnings an investors options playbook | 6 Aug 2026 DRAM the memory boom now has an option chain Here is how to read it | 4 Aug 2026 Disney high rank cheap event | 3 Aug 2026 Rheinmetall how to use options on a share that costs EUR 1139 | 31 Jul 2026 Shell into second-quarter earnings two ways to use options for income | 24 Jul 2026 LVMH through results season what mini options change for a smaller portfolio | 22 Jul 2026 What investors misunderstand about covered calls | 10 Jun 2026 Covered call or cash-secured put | 2 Jun 2026 From shareholder to options user | 26 May 2026 |
| More from the author |
|---|