
Access all our platforms from a single account.

What investors misunderstand about covered calls

Summary: Most investors think of covered calls as an income strategy. That’s understandable, the premium is immediate and visible. But for many long-term investors, the more valuable part of the trade is what the strike price actually does: it turns a vague exit intention into a specific commitment. Deciding when to sell is one of the hardest problems in investing. Most investors never build a structured plan for it. Covered calls can help ...
What investors misunderstand about covered calls
A decision framework for long-term investors.
Imagine owning a stock that has been one of your better investments. A year ago, it traded at EUR 100. Today it reaches EUR 120.
You tell yourself: “If it gets much higher, I’ll probably take some profits.”
A few weeks later, the stock trades at EUR 125. Then EUR 130. Now selling feels much harder than it did at EUR 120. What if it keeps going?
So you hold on.
A quarter later, the company disappoints investors. Earnings miss expectations, guidance is lowered, and the share price falls back to EUR 100.
Suddenly the conversation in your head changes. Instead of wondering whether you should have sold at EUR 130, you’re wondering why you didn’t. If this sounds familiar, you’re not alone.
Most investors spend years learning how to buy stocks. Far fewer spend time thinking about how they will eventually sell them. Yet selling is often one of the hardest decisions in investing.
Ironically, this is one of the reasons covered calls can be useful.
Most investors think covered calls are primarily about generating income. While the premium can certainly be attractive, that may not be their most valuable feature. For many long-term investors, covered calls can help solve a much more difficult problem: deciding when enough profit is enough.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it is crucial to make informed decisions.
Why selling is so difficult
Buying a stock is usually based on a thesis. You believe earnings will grow. You expect a new product launch to succeed. You think the market is undervaluing the company.
Selling is different. There is rarely a clear signal telling you that now is the perfect time to exit.
Sell too early and the shares may continue higher. Sell too late and years of gains can disappear surprisingly quickly.
As a result, many investors do what feels safest. They postpone the decision.
Unfortunately, postponing a decision is still a decision.
Most investors already use covered-call thinking
Even investors who have never traded an option often think in terms of future selling prices.
Perhaps you’ve said:
- “I’d probably sell if it reaches EUR 120.”
- “If the stock doubles, I’d take some profits.”
- “I’d be happy to exit around that level.”
These are all examples of target prices.
The challenge is that target prices often look sensible when a stock is trading at EUR 100. They become much harder to follow when the stock is actually trading at EUR 120. That is where emotions begin to compete with discipline.
A covered call can help bridge that gap.
Turning a target price into a plan
A covered call combines two elements:
- Ownership of at least 100 shares
- The sale of a call option against those shares
In exchange for receiving a premium, the investor agrees to sell the shares at a specific price, known as the strike price, if the option is exercised.
Many investors focus immediately on the premium. However, the strike price is often the more important part of the decision.
Suppose you own 100 shares trading at EUR 50. You decide that EUR 55 would be an attractive level to sell. You then sell a covered call with:
- Strike price: EUR 55
- Premium received: EUR 1 per share
- Total premium received: EUR 100
At that moment, you have done something many investors struggle to do. You have created a plan.
Rather than saying: “Maybe I’ll sell if the shares go higher.”
You have said: “I am comfortable selling at EUR 55, and I will be paid EUR 100 today for making that commitment.”
That is a very different mindset.
The premium is still important
None of this means the premium should be ignored. The premium is a real benefit of the strategy.
- If the shares remain below the strike price until expiry, the option may expire worthless. In that scenario, the investor keeps both the shares and the premium received.
- If the shares fall modestly, the premium can help offset part of the decline.
- If the shares rise above the strike price, the investor may sell at the predetermined level and still keeps the premium.
The premium improves all three potential outcomes.
But it is often the structure, rather than the income, that creates the greatest value.
What about missing further gains?
This is often the biggest concern. Suppose the shares rise from EUR 55 to EUR 65 after the covered call is sold. Many investors immediately focus on the EUR 10 they “missed”.
That reaction is understandable. However, it overlooks an important fact. The investor selected EUR 55 as an attractive selling price before entering the trade. The original objective was achieved.
The real danger for many investors is not missing some upside after taking profits. It is never taking profits at all.
A covered call does not eliminate regret. No investment strategy can do that. What it can do is replace an emotional decision with a structured one.
When covered calls may make sense
Covered calls are often most suitable when an investor:
- Already owns at least 100 shares
- Has a price in mind where selling would be acceptable
- Wants to generate additional income while holding the shares
- Is moderately positive, rather than extremely bullish, on the stock
- Prefers a structured approach to profit-taking
They are not necessarily about maximising returns. They are often about improving discipline.
A different way to think about covered calls
The biggest misunderstanding about covered calls may not involve options at all. Many investors see them as income strategies. In reality, they can also be decision-making strategies. The premium attracts attention because it is visible and immediate. The strike price receives less attention, even though it may be the more important choice.
For long-term investors, a covered call can help transform a vague future intention into a clear plan.
The income is valuable. The clarity may be even more valuable.
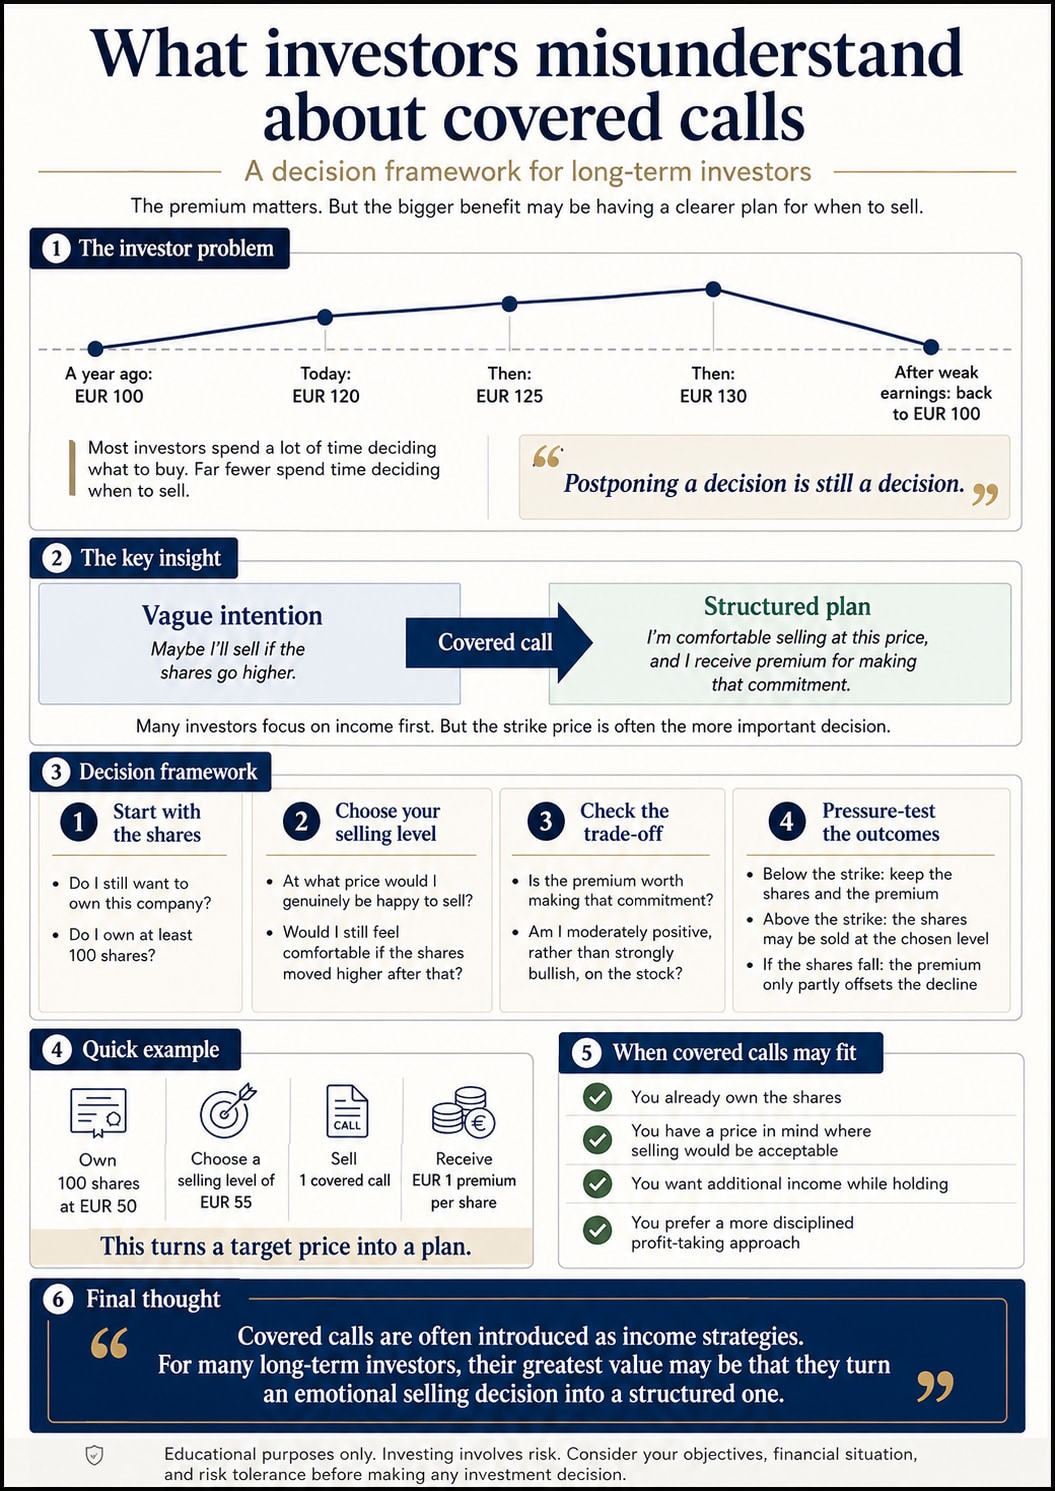
Covered calls are often viewed as income strategies, but they can also help investors create a structured plan for taking profits. This framework highlights the key questions to consider before deciding whether a covered call fits your investment objectives. Source: Saxo
This content is marketing material and should not be regarded as investment advice. Trading financial instruments carries risks and historic performance is not a guarantee of future results.
The Author is permitted to wait at least 24 hours from the time of the publication before they trade the instruments themselves.
The instrument(s) referenced in this content may be issued by a partner, from whom Saxo receives promotional fees, payment or retrocessions. While Saxo may receive compensation from these partnerships, all content is created with the aim of providing clients with valuable information and options.
This content will not be changed or subject to review after publication.
| Related articles/content |
|---|
| Covered call or cash-secured put | 2 Jun 2026 From shareholder to options user | 26 May 2026 Micron before earnings - using a covered call after a strong rally | 29 May 2026 Alphabet after earnings - how a covered call can help investors manage a strong rally | 30 Apr 2026 Tesla shares after earnings could a covered call make sense | 27 Apr 2026 A structured way to buy IWDA at a lower price using options | 20 Mar 2026 How to improve the yield on a long-term IWDA holdings | 12 Mar 2026 How to use a collar to protect stock gains - a Tesla case study | 20 Feb 2026 Palantir after earnings - using options to define a potential entry price | 4 Feb 2026 Golds pullback - thinking beyond buy or sell | 3 Feb 2026 Why options got so popular in recent years | 28 Jan 2026 |
| More from the author |
|---|