
Access all our platforms from a single account.

Apple earnings: where the options market puts the price of the report

Summary: Apple reports on 2 November 2026, and the 4 November options already carry the reaction. What a later expiry adds shows where the price of the report sits. A double calendar and a long straddle take opposite sides of that gap.
If the report is already inside the first expiry, what is the second expiry paying for?
Option prices around earnings come in layers. Apple reports on 2 November 2026, after the US close, so 3 November is the first session that prices the result. The first expiry after that, Wednesday 4 November, holds the whole reaction, and every later expiry adds ordinary trading days on top.
That layering is the subject here: how much of an option’s price is the report, how it shows in the gap between two expiries, and what two structures do with it. They take opposite sides and neither is a view on Apple’s results. In our view, the gap between expiries may say more than the headline size of the expected move.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it’s crucial to make informed decisions.
Apple rarely moves much, and the options still charge for it
Over its last eight reports Apple’s shares typically moved about 2% the next day. Six of the eight were falls, and the largest, in July 2026, was 7.4%. Source: Apple report dates from company filings; Saxo price data, author calculation. Past performance is not indicative of future results.
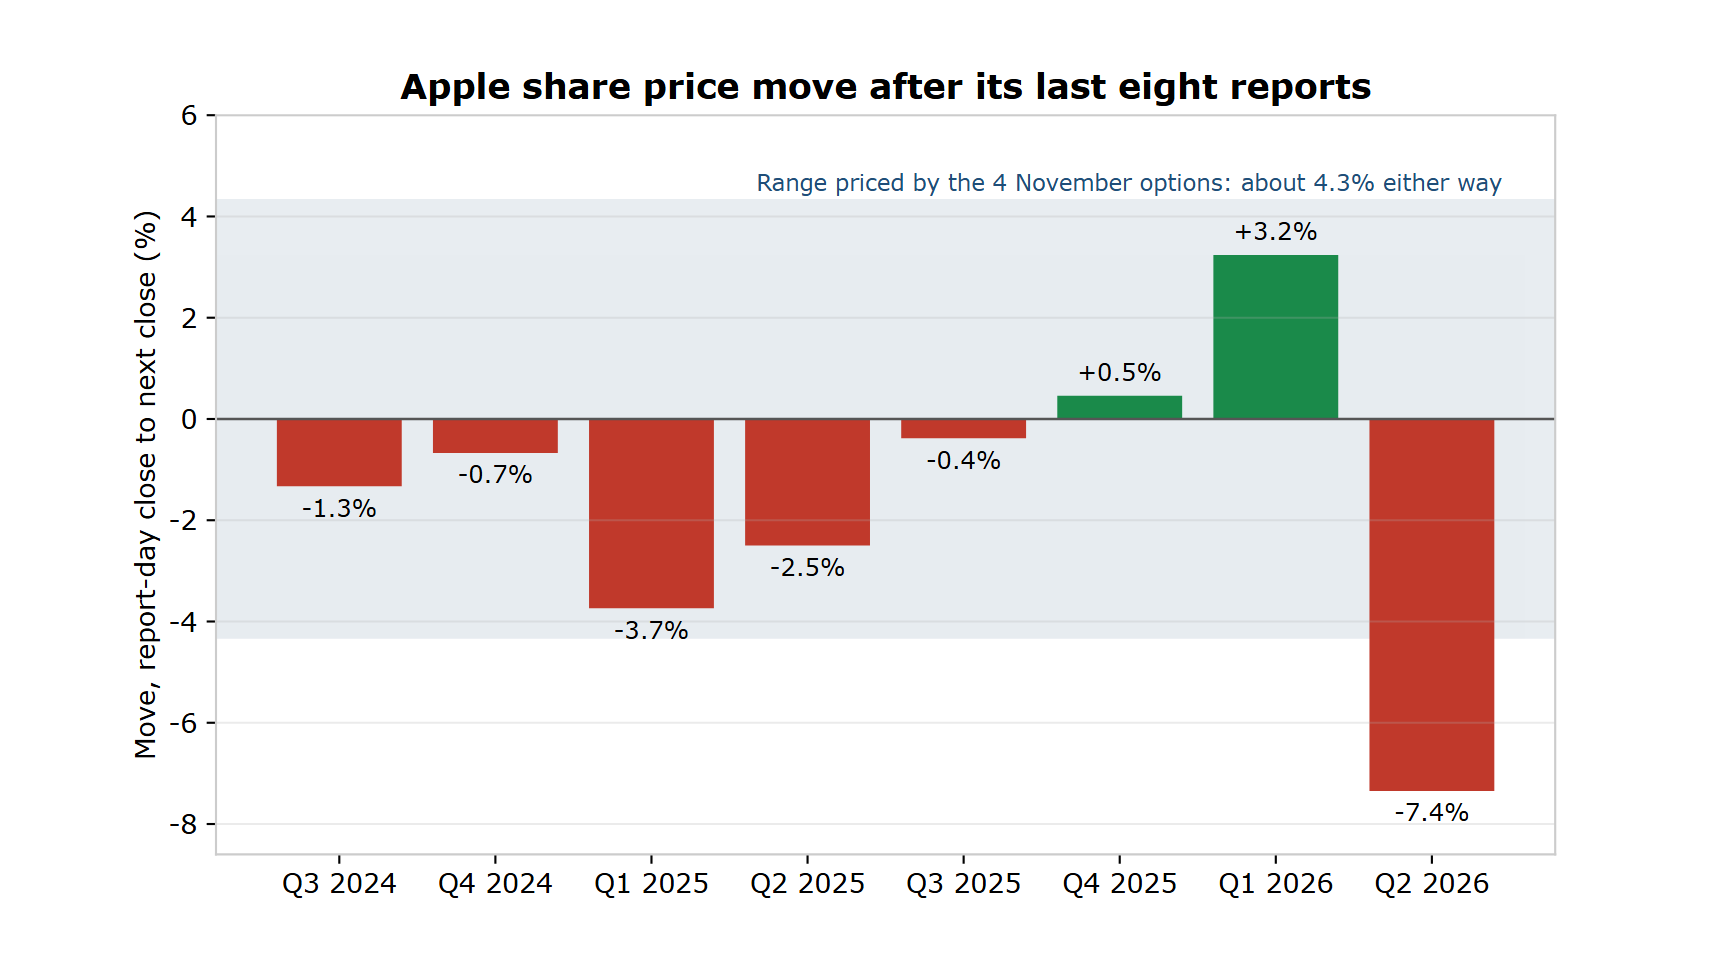 Apple share price move from the report-day close to the next close on its last eight reports, against the range of about 4.3% priced by the 4 November 2026 options. Past performance is not indicative of future results; figures are illustrative and not predictive. Source: Apple company filings, Saxo price data and indicative Saxo option quotes after the US close on 27 October 2026; author calculation.
A common way to estimate the move the market expects is to add the at-the-money call and put for the expiry that captures the report. The 347.5 strike is closest to the share price:
- Share price: about USD 347.10, the 27 October close
- 347.5 call, 4 November expiry: about USD 7.23
- 347.5 put, 4 November expiry: about USD 7.75
- Straddle: about USD 14.98, roughly 4.3% of the share price, or a range of about USD 332 to USD 362
- (Source: Saxo, indicative quotes after the US close on 27 October 2026)
That is about twice Apple’s usual move. Part of the price pays for the ordinary days before the report, and part is uncertainty that tends to drain away once the numbers are out, often called the IV crush. The drain helps whoever sold the options and hurts whoever bought them.
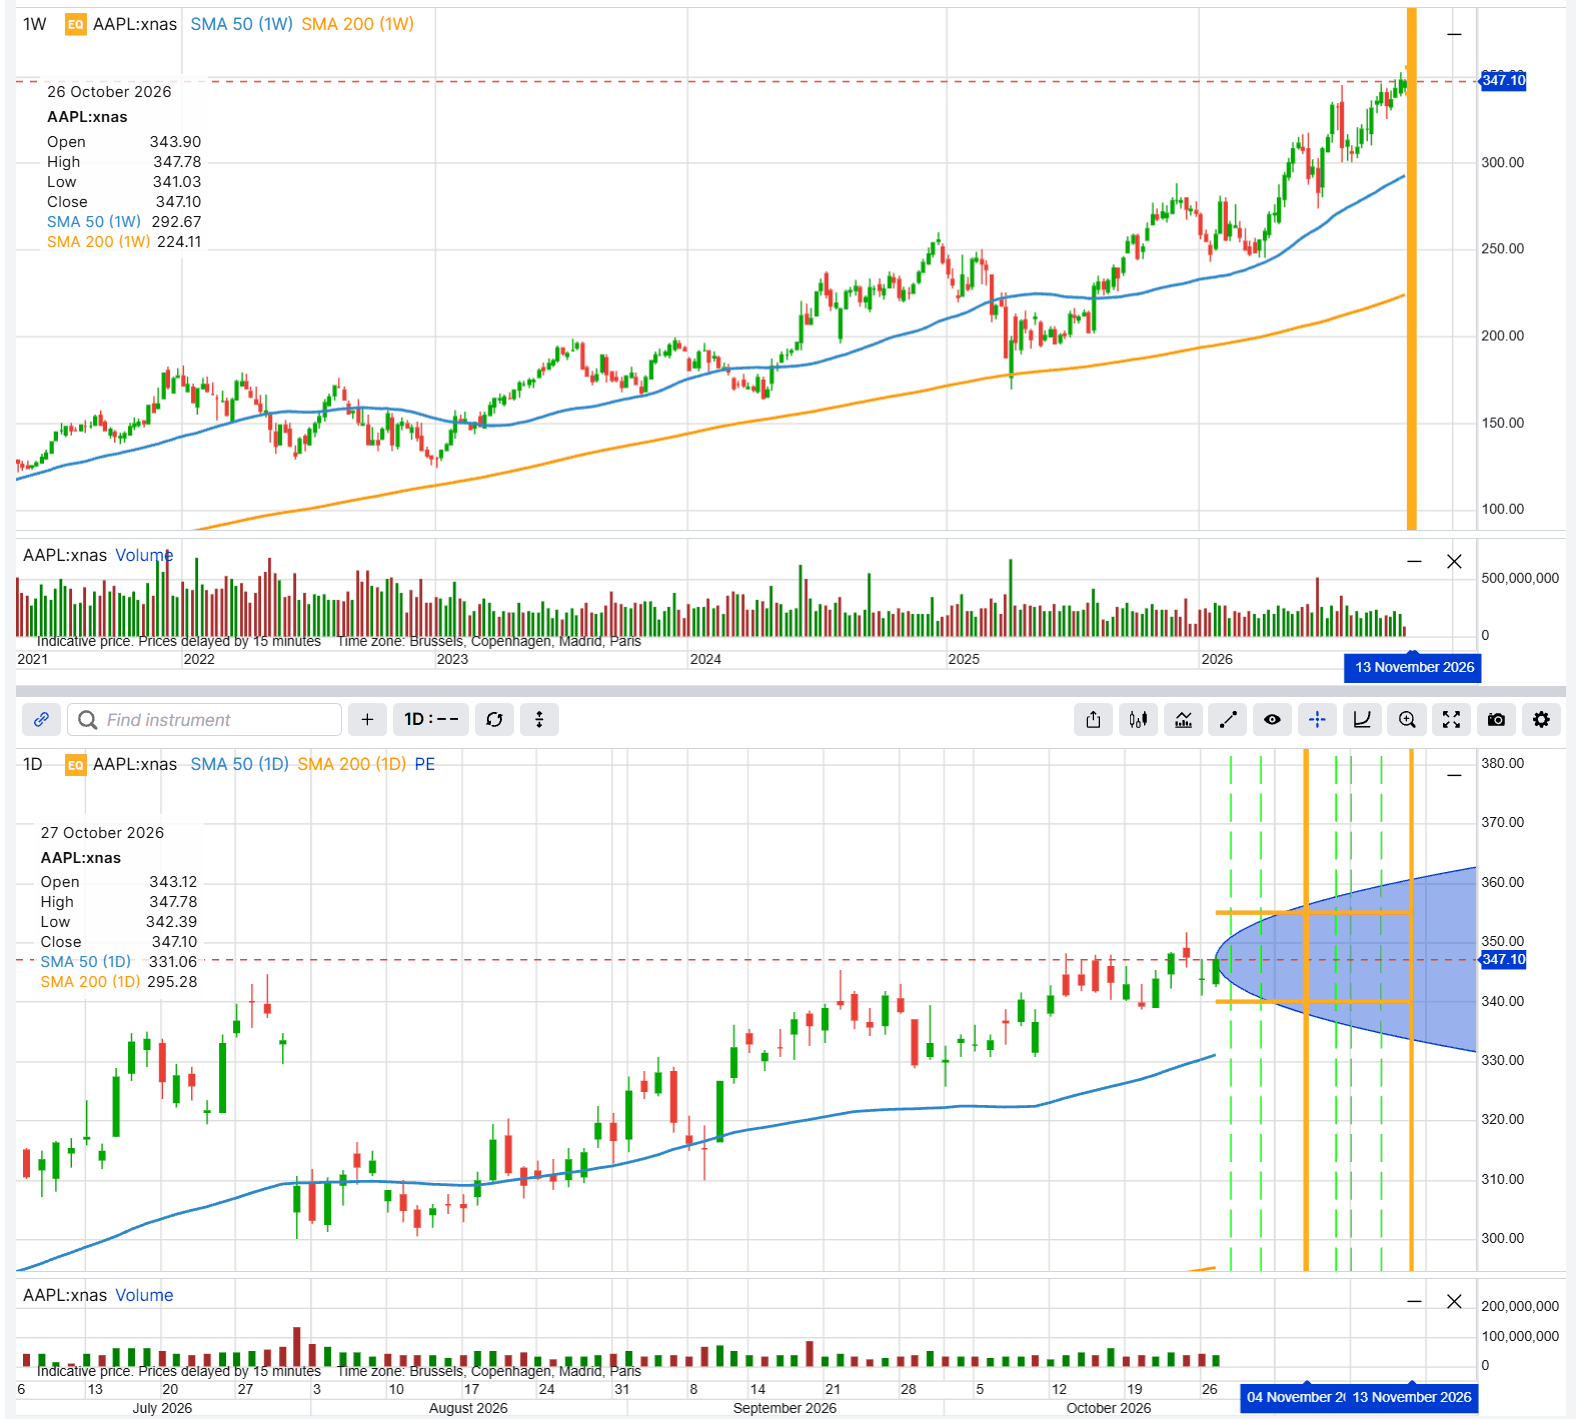 Apple share price, weekly and daily, with the 4 and 13 November 2026 expiries marked. Past performance is not indicative of future results; figures are illustrative and not predictive. Source: SaxoTrader, 27 October 2026 close.
One report, two expiries: where the price sits
The same 347.5 straddle gets more expensive with each later expiry, but not by much. Each figure is the call plus the put at that strike:
- 4 November: about USD 14.98, 4.3% of the share price
- 6 November: about USD 15.85, 4.6%
- 13 November: about USD 17.96, 5.2%
- (Source: Saxo, indicative quotes after the US close on 27 October 2026)
Reading across, the first expiry already contains the report, and the seven further sessions to 13 November add about USD 2.98. In our view, that pattern may suggest most of the price is for the report itself and the rest for ordinary movement, though the split cannot be read exactly from a chain.
It also hints at two ways to use the gap. Owning the first expiry pays the report’s premium, and a structure that sells the first expiry and owns the second aims to collect it. The two examples below do each.
Why 4 November, and why these strikes
The 4 November expiry is the first after the reaction day, so it captures the report with the fewest ordinary days attached. Later expiries dilute it. The 13 November expiry is used for the long legs of the calendar because it is far enough out to keep most of its value after the report.
The straddle uses the 347.5 strike, the one nearest the share price. The double calendar uses puts at 340 and calls at 355. Each strike sits about 2% from the share price, close to Apple’s typical report move, and both carry open interest on each expiry. Strikes further apart lower the cost and widen the zone where the position gains, but lower the peak; strikes closer together do the opposite. All figures are hypothetical and for education only.
Selling the report’s premium: a double calendar
The risk comes first: the most this structure can lose is the debit paid, and only if it is closed on or before 4 November. A big move either way, like July 2026, may leave both sides worth less than they cost. If the share price stays near or between the strikes, the short options may lose value faster than the long ones, which is where the gain would come from.
Example structure (illustrative only - not a trade recommendation)
- Sell 1 Apple 4 November 2026 340 put at about USD 4.475 (bid 4.35, ask 4.60)
- Buy 1 Apple 13 November 2026 340 put at about USD 5.80 (bid 5.50, ask 6.10)
- Sell 1 Apple 4 November 2026 355 call at about USD 3.875 (bid 3.75, ask 4.00)
- Buy 1 Apple 13 November 2026 355 call at about USD 5.40 (bid 5.10, ask 5.70)
- Net debit: about USD 2.85 per share, USD 1.325 for the put pair (5.80 less 4.475) plus USD 1.525 for the call pair (5.40 less 3.875), or USD 285 per contract
- Maximum loss: about USD 285 per contract (hypothetical, for education only), the full debit, if the position is closed on or before 4 November; maximum profit: not fixed at entry (hypothetical, for education only)
- Costs and charges apply to each leg and vary by account and venue; check the applicable rates before entering any position.
- (Source: Saxo, indicative quotes after the US close on 27 October 2026)
Unlike a vertical spread, a calendar has no fixed maximum profit or break-even. The gain depends on implied volatility and on what the 13 November options can be sold for once the 4 November options expire. Because the long options also lose value when implied volatility falls after the report, the gain may be smaller than the idea of selling the premium suggests.
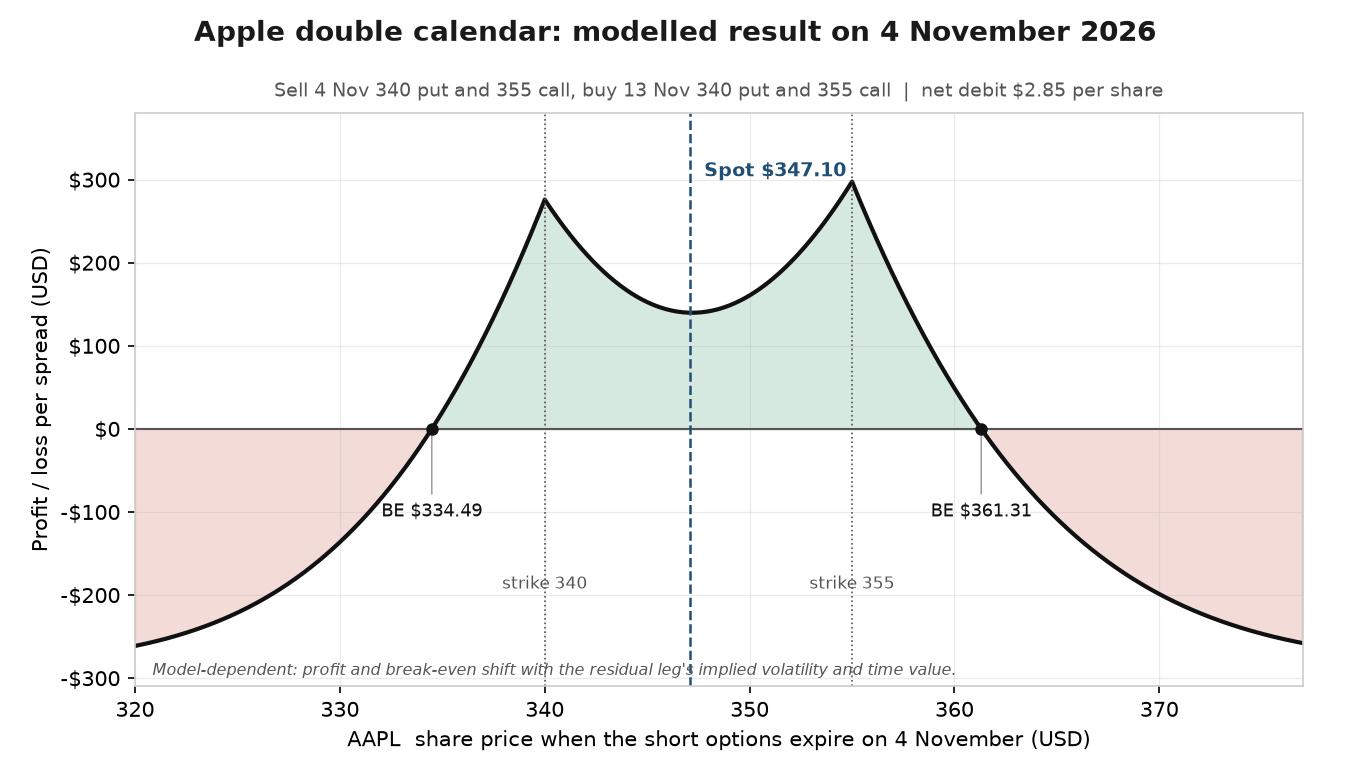 Double calendar with 340 puts and 355 calls, 4 and 13 November 2026 expiries, modelled at the 4 November close with an assumed implied volatility of 23% for the long options. The platform does not draw a profit and loss chart for two-expiry orders, so this is a model, and the line moves with the volatility assumed. Hypothetical example for education only. Past performance is not indicative of future results; figures are illustrative and not predictive. Source: author calculation from indicative Saxo quotes after the US close on 27 October 2026.
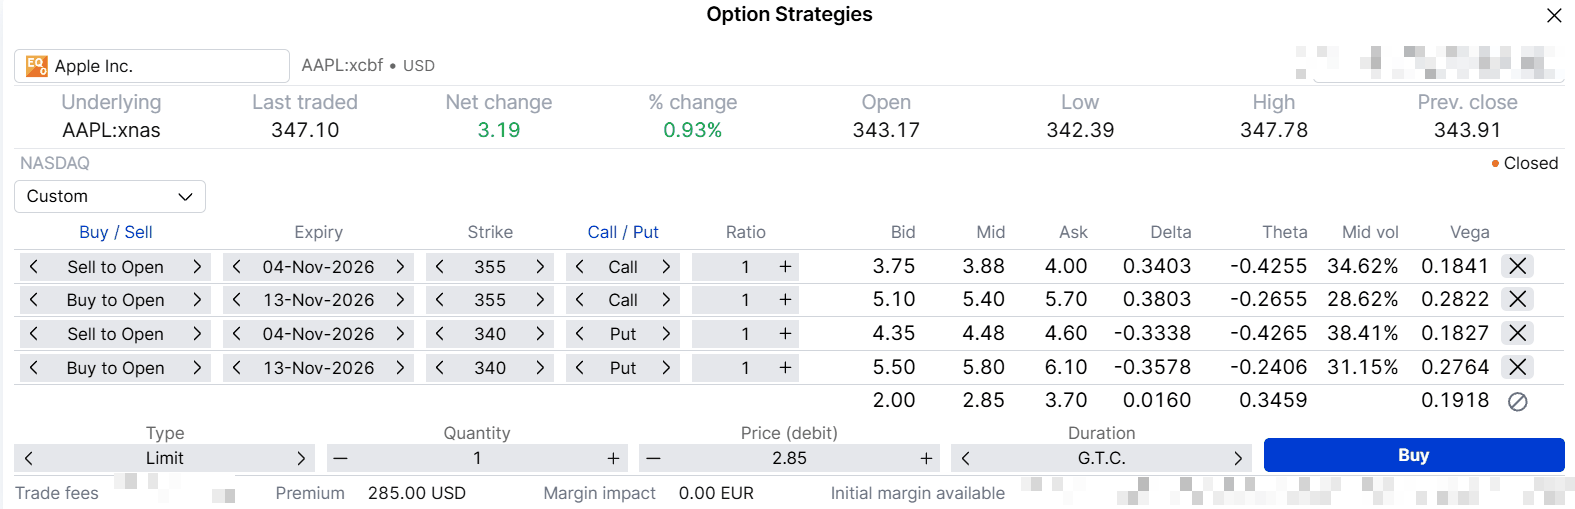 SaxoTrader order ticket for the double calendar with its four legs. Hypothetical example for education only. Source: SaxoTrader, 27 October 2026.
Its best case is a report that leaves Apple near or between the two strikes; its worst is a large move in either direction. Options carry a high risk of rapid loss and are not suitable for every investor.
Buying the report’s premium: a long straddle
The risk comes first: the debit is the most that can be lost, and all of it goes if Apple closes at 347.5 on 4 November. The report has to move the shares by more than the price paid, and the IV crush works against both options. Because the expiry is the day after the reaction, little time value is left to soften the fall.
Example structure (illustrative only - not a trade recommendation)
- Buy 1 Apple 4 November 2026 347.5 call at about USD 7.23 (bid 7.05, ask 7.40)
- Buy 1 Apple 4 November 2026 347.5 put at about USD 7.75 (bid 7.05, ask 8.45)
- Net debit: about USD 14.98 per share, USD 7.23 for the call plus USD 7.75 for the put, or USD 1,498 per contract
- Maximum loss: about USD 1,498 per contract (hypothetical, for education only), the full debit, if Apple closes at 347.5; maximum profit: not capped on the upside, and on the downside limited only by the share price falling to zero (hypothetical, for education only)
- Break-even at expiry: USD 362.48 and USD 332.52, about 4.4% above and 4.2% below the share price
- Costs and charges apply to each leg and vary by account and venue; check the applicable rates before entering any position.
- (Source: Saxo, indicative quotes after the US close on 27 October 2026)
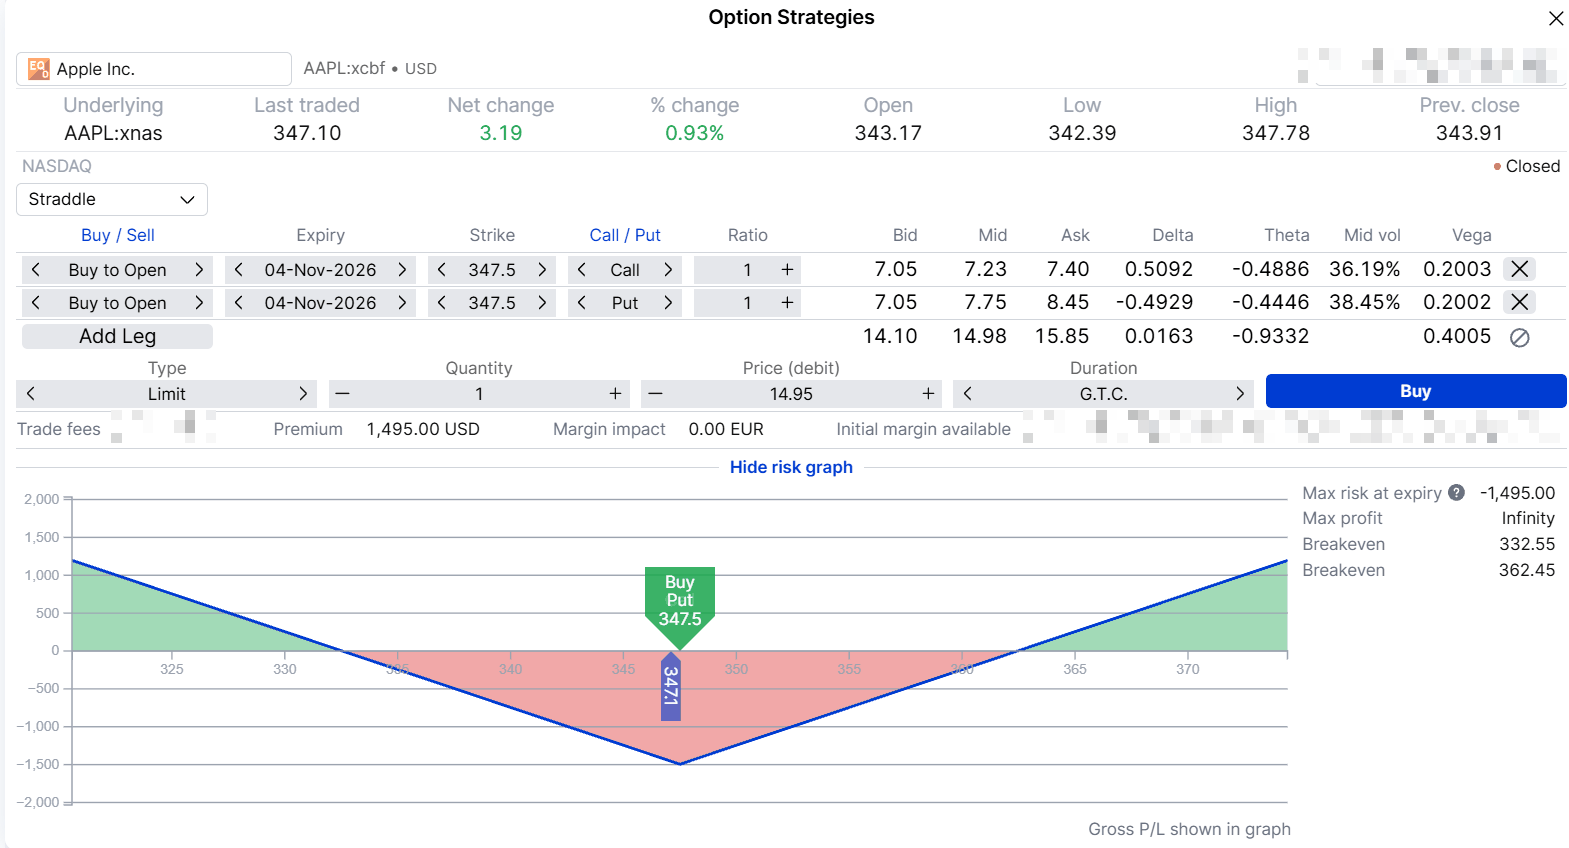 Long straddle with the 347.5 call and 347.5 put, 4 November 2026 expiry, payoff at expiry. The screen uses a limit price of 14.95, just under the 14.98 mid, so its break-evens and maximum loss differ slightly from the figures in the text. Hypothetical example for education only. Past performance is not indicative of future results; figures are illustrative and not predictive. Source: SaxoTrader, 27 October 2026.
Applied to the current share price, only July 2026’s fall would have gone beyond the break-evens in the last eight reports; the 3.7% drop after the May 2025 report came close. Source: Saxo price data, author calculation. Eight reports are a small sample, and past performance is not indicative of future results. A report like most of the eight leaves this structure with a loss. Options carry a high risk of rapid loss and are not suitable for every investor.
Practical points: spreads, assignment and the exit
- Costs add up with every leg. Each leg is charged separately and crosses its own bid/ask spread. The two 13 November options in the calendar each quote about USD 0.60 wide, which is a real cost on a debit of USD 2.85.
- Wide quotes on the straddle. The 4 November 347.5 put quotes about USD 1.40 wide, close to a tenth of the straddle’s price.
- Orders. Both examples can be placed as one multi-leg order on Saxo, including the two expiries of the calendar.
- Timing. The report lands after the close on 2 November, so the first reaction comes at the open on 3 November, and 4 November is the expiry of the short options and the straddle.
- The exit. The calendar’s 13 November options outlive the short ones and stay open unless they are closed. Deciding the exit before the report is easier than deciding during the move.
Assignment risk: Apple options are American-style, so a short leg that moves into the money can be assigned before expiry, particularly close to expiration. Only the calendar has short legs; the long straddle has none.
Final thoughts
The two examples read the same gap from opposite sides. One may gain if the report is smaller than the first expiry charges for, the other if it is larger, and each has a maximum loss known before entry.
Which expiry holds the report, and how much the next one adds, is something a reader can check on the chain before choosing any structure. Whether either example fits depends on the reader’s view, risk tolerance and live prices. Options carry a high risk of rapid loss and are not suitable for every investor.
The author does not hold positions in any of the instruments mentioned in this article. The Author is permitted to wait at least 24 hours from the time of the publication before they trade the instruments themselves.
| More from the author |
|---|