Quick Take Asia

Asia Market Quick Take – 30 March, 2026

Macro 6 minutes to read

Asia Market Quick Take – 30 March, 2026

Key points:

  • Macro: Iran backed Houthis joins US-Iran conflict
  • Equities: S&P down 1.7% on Friday in fifth consecutive week of decline on war
  • FX: JPY near 160 against USD, intervention fears rise as global risk-off deepens
  • Commodities: Brent rallies 3% on record-month pace; WTI >$100
  • Fixed income: Treasuries up; 2s10s yield curve twist steepening to 50bp.

------------------------------------------------------------------
qt 3003

Disclaimer: Past performance does not indicate future performance.

Macro: 

  • As the Iran war entered its fifth week, investor doubts about a quick resolution grew after Iran‑backed Houthis joined the conflict, fired missiles at Israel, and threatened further attacks, while the US reportedly prepared for weeks of ground operations with more troops deployed to the region.
  • Despite repeated warnings from Tokyo, including Finance Minister Satsuki Katayama’s pledge to take “bold actions” against excessive FX moves, the yen remained under pressure from surging Middle East–driven oil prices that threaten Japan’s recovery, prompting the Finance Ministry to reportedly explorepossible intervention in crude futures.
  • The Michigan Consumer Sentiment Index fell to 53.3 in March from 56.6 in February, near late‑2025 lows, amid higher gas prices and market volatility linked to the Iran conflict. Short-term economic and personal finance expectations weakened sharply, while long-term views slipped slightly. Year-ahead inflation expectations rose to 3.8% and long-term expectations dipped to 3.2%.

Equities:

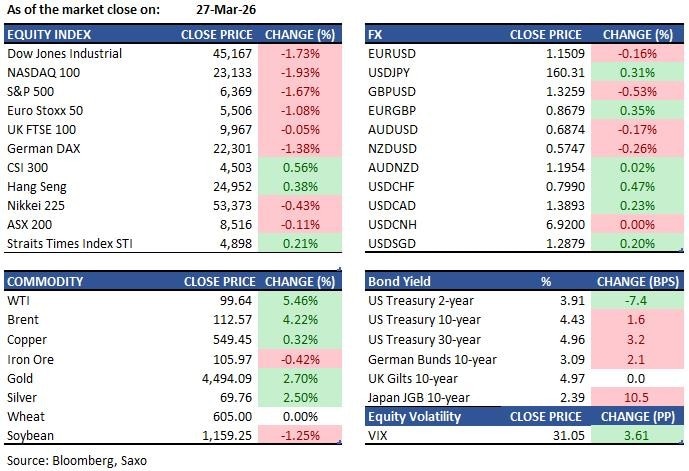
  • US: US stocks fell sharply on Friday with the S&P 500 down 1.7% to 6,368.85, marking its fifth consecutive weekly decline - the longest losing streak since 2022. Both the Nasdaq 100 and Dow Jones entered correction territory, trading more than 10% below recent highs, as fears intensified that surging oil prices will cripple the global economy. The VIX index closed above 30 for the first time since April. Dow futures fell 300 points overnight as investors braced for potential US ground assault on Iran. Mega‑cap tech remained under pressure, with Nvidia, Microsoft and Alphabet down over 2% and Meta falling 4%. 
  • EU: European equities ended sharply lower on Friday as rising energy prices reinforced stagflation concerns across the region. The STOXX 50 fell 1.1% to 5,508 and the STOXX 600 dropped 0.9% to 575. While President Trump extended the pause on strikes on Iran’s energy facilities until April 6, higher oil prices are already feeding into inflation. Spain’s March inflation hit its highest level since 2024. Banks slid on rising yields, and industrials extended losses.
  • Asia: Asian markets opened sharply lower on Monday as the Iran conflict intensified. Japan's Nikkei plunged 5.0% to 50,712 in early trading, while South Korea's Kospi tumbled 4.4% to 5,236, extending Friday's losses. The Hang Seng closed Friday unchanged at 24,952 after weekend developments. China's CSI 300 was flat at 4,503. Singapore's STI finished Friday at 4,898, up 0.2%.SoftBank Group is down 8.3% after $40 bridge loan for Open AI investment.

Earnings this week:

  • Monday: Agricultural Bank of China, Bank of China
  •  Tuesday: Nike, Beyond Meat
  •  Wednesday: SAIC Motor

FX:

  • Currency markets are mixed in early Asia amid risk-off sentiment and geopolitical tensions, with USDJPY around 160 as the yen hovers near intervention levels following strong warnings from Japan’s top FX official about potential “bold” action. USD remains firm, hitting a 20‑month high against the yen, while EURUSD 1.1506 and GBPUSD 1.3251 edge lower on Middle East concerns.
  • Asian FX shows a varied picture with a slightly weaker yuan at USDCNY 6.9112, and a firmer Singapore dollar at USDSGD 1.2891, and commodity-linked currencies are under pressure, led by the Australian dollar at AUDUSD 0.6850, down 0.35 percent and the weakest performer among majors.

Commodities:

  • Oil rose as Iran-backed Houthi militants in Yemen joined the Middle East conflict and more US troops were deployed, heightening fears for energy markets. Brent—on course for a record monthly gain—surged more than 3% at the open to $116.43 after the Houthis fired missiles at Israel and vowed to continue operations until attacks on Iran and its proxies cease, while WTI climbed above $100.
  • Gold logged its first weekly gain since the Middle East war began as bargain hunters stepped in, with bullion near $4,490 an ounce in early trading after a 2.7% rise, as opportunistic buying followed the steepest sell-off in years even amid worries that a prolonged conflict could prompt central banks to sell holdings or raise interest rates to curb inflation.

Fixed income:

  • Treasuries ended Friday mixed with a twist steepener around a near‑unchanged 7‑year sector as the front end outperformed—2‑year yields topped 4% in the morning amid a dovish tone in SOFR futures/options and a large 2‑year note futures block—most yields retreating from year‑to‑date highs and the 2s10s spread breaching 50bp for its biggest widening since 1 August.

For a global look at markets – go to Inspiration.

This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.


Disclaimer

Confidentiality and Usage:
You may not reproduce, distribute, or transmit this material or any portion thereof without prior written permission from Saxo.

Nature of Information:
The information provided herein is based on current market conditions and analysts' opinions, which may reflect personal views of the author, and are subject to change without notice. This material does not include a record of any trading prices, or an offer of, or solicitation for, or endorsement to enter into any transaction in any investment product. Any forecast on the economy, markets and economic trends of the markets provided is not necessarily indicative of the future or likely performance of the investment product subject of this material.

Responsibility and Liability:
Saxo accepts no liability for any use that may be made of these comments or for any consequences that arise from such use. Saxo does not guarantee the accuracy or completeness of any information provided and assumes no liability for any errors, omissions, losses, or damages resulting from the use of this information.

The information provided in this material is solely for information only. It is intended for general circulation and does not take into account the specific investment objectives, financial situation or particular needs of any particular person. Accordingly, it should not be relied on or treated as a substitute for specific advice concerning specific situations of any person. Please seek advice from a financial adviser regarding the suitability of any investment product taking into account your specific investment objectives, financial situation or particular needs before you make a commitment to purchase an investment product. In the event that you choose not to seek advice from a financial adviser, you should consider whether any investment product mentioned in this publication is suitable for you.

Notwithstanding the above, insofar as any information provided herein contains research analyses or reports concerning any investment product authored by any foreign research house and is issued or promulgated to a person in Singapore who is not an accredited investor, expert investor, and/or institutional investor, Saxo Capital Market Pte. Ltd. accepts legal responsibility for the contents of this material to the extent required by law. Recipients of such material are to contact Saxo Capital Markets Pte. Ltd. in respect of any matters arising from, or in connection with, this material.

Risk Disclosure:
Trading in investment products involve significant risk, including the risk of losing your entire investment. Historical returns are not a guarantee of future returns. Prices can both rise and fall, and there is a risk that you will not get back the money you invested.

Conflicts of interest:
The author may hold positions in the investment products mentioned. The author does not own positions in the underlying investment product exceeding 0.5% of its market capitalisation, save as otherwise declared. The author is not permitted to trade the mentioned investment products within the first 24 hours after the publication of this article.

Saxo maintains partnerships with companies that compensate Saxo for promotional activities conducted on its platform. Additionally, Saxo has agreements with certain partners who provide retrocession contingent upon clients purchasing specific investment products offered by these partners. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.

Publication details:
If any listed companies are the subject of the material, the content has not been submitted to the companies in question prior to publication.

Please refer to our full disclaimer and notification on non-independent investment research for more details.

Saxo Markets
88 Market Street
CapitaSpring #31-01
Singapore 048948

Contact Saxo

Singapore
Singapore

Saxo Capital Markets Pte Ltd ('Saxo Markets') is a company authorised and regulated by the Monetary Authority of Singapore (MAS) [Co. Reg. No.: 200601141M ] and is a wholly owned subsidiary of Saxo Bank A/S, headquartered in Denmark. Please refer to our General Business Terms & Risk Warning to consider whether acquiring or continuing to hold financial products is suitable for you, prior to opening an account and investing in a financial product.

Saxo is part of the J. Safra Sarasin Group.

Trading in financial instruments carries various risks, and is not suitable for all investors. Please seek expert advice, and always ensure that you fully understand these risks before trading. Trading in leveraged products such as Margin FX products may result in your losses exceeding your initial deposits. Saxo Markets does not provide financial advice, any information available on this website is ‘general’ in nature and for informational purposes only. Saxo Markets does not take into account an individual’s needs, objectives or financial situation.

The Saxo trading platform has received numerous awards and recognition. For details of these awards and information on awards visit www.home.saxo/en-sg/about-us/awards.

The information or the products and services referred to on this website may be accessed worldwide, however is only intended for distribution to and use by recipients located in countries where such use does not constitute a violation of applicable legislation or regulations. Products and Services offered on this website are not intended for residents of the United States, Malaysia and Japan. Please click here to view our full disclaimer.

This advertisement has not been reviewed by the Monetary Authority of Singapore.

Apple and the Apple logo are trademarks of Apple Inc, registered in the US and other countries and regions. App Store is a service mark of Apple Inc. Google Play and the Google Play logo are trademarks of Google LLC.