
Access all our platforms from a single account.

Asia Market Quick Take – October 13, 2025

Key points:
- Macro: Trump imposes 100% tariffs on China beginning 1st November
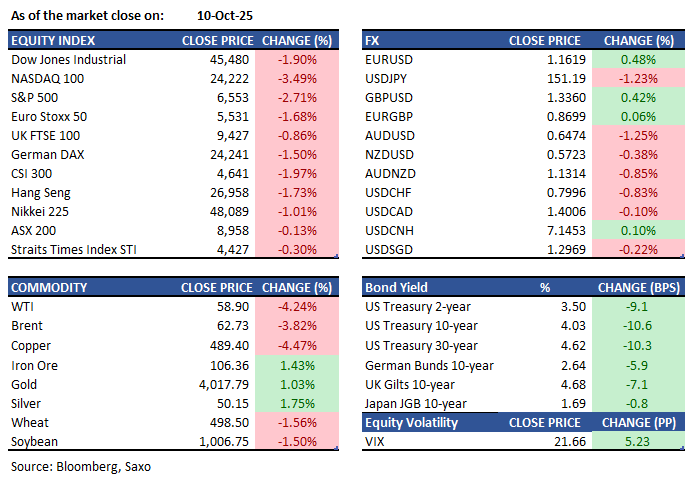
- Equities: US stock indices drop; Trump's tariff threat hits tech hard
- FX: Trump's critique of China's exports weakens USD; JPY and CHF gained against USD
- Commodities: Brent rebounded after Friday’s 3.8% drop, its sharpest since August.
- Fixed income: Treasuries retraces down reversing some of the gains
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Trump's administration signaled openness to a China trade deal despite rising tensions from Beijing's export controls and Trump's announcement of 100% tariffs on Chinese imports starting November 1. Vice-President J.D. Vance claims Trump holds leverage in a prolonged dispute. Beijing vowed countermeasures, threatening trade negotiation progress. A Commerce Ministry spokesperson condemned the tariff threats, asserting China's readiness to protect its interests while stating it does not seek, but is prepared for, a tariff war.
- The University of Michigan's US consumer sentiment was 55 in October 2025, almost unchanged from September's 55.1 and above forecasts. Improvements in personal finances and business conditions balanced declines in future finances and buying conditions. The economic conditions index rose to 61, while expectations fell to 51.2. Inflation expectations for the year ahead edged down to 4.6%, while long-term expectations remained at 3.7%.
- Japan's opposition considers a unified PM candidate to challenge LDP President Takaichi and aims to form an alliance with other parties, according to Nikkei.
Equities:
- US - US stocks slumped Friday after Donald Trump threatened a “massive” tariff hike on Chinese goods and hinted at cancelling his meeting with Xi Jinping. The S&P 500 dropped 2.7%, its steepest fall since April, while the Dow lost 879 points and the Nasdaq slid 3.6%, erasing weekly gains. Tech and chipmakers bore the brunt: AMD plunged 7.8%, Nvidia 5%, and Qualcomm 7.3% amid a Chinese antitrust probe. Concerns deepened as Beijing imposed new rare earth export controls and the US government shutdown entered its 10th day. Futures rebounded Monday after Trump signalled softer tariff plans, saying ties with China “will be fine”, echoed by VP JD Vance, who noted the US is ready to negotiate if Beijing is “reasonable”.
- EU - European stocks fell for a second session Friday, with the Stoxx 50 and Stoxx 600 down about 1% as defence shares slumped on signs of progress in a US-brokered Middle East peace deal. Israel confirmed a ceasefire with Hamas at noon local time, including troop withdrawals and hostage releases. The Stoxx Europe Aerospace & Defence index dropped over 2%, led by Leonardo (-5.6%), Rheinmetall (-2.5%), Thales (-2.4%), Saab (-2.2%), BAE Systems (-1.9%), Rolls-Royce (-1.7%), Safran (-1.6%) and Airbus (-1%). Mining stocks also weakened, with the Basic Resources index down more than 1.5%. Sentiment worsened after Donald Trump threatened a “massive” tariff hike on Chinese goods. On the upside, Jyske Bank gained 4% on upbeat corporate updates.
- HK - Hang Seng fell 1.7% to 26,290 on Friday, its fifth straight loss and lowest in two weeks. Tech stocks slumped over 3% after China tightened rare earth export controls and enforced chip import restrictions to curb reliance on US products like Nvidia’s AI chips. Consumer shares dropped 2.7% as investors awaited key September data on trade, inflation and credit. Major laggards included Zhaojin Mining (-7.4%), SMIC (-7.2%), China Hongqiao (-5.9%), Kuaishou (-5.4%) and Tencent (-3.6%). Hang Seng futures fell sharply over 3% after Trump threatened a massive tariff hike of 100% on Chinese goods in the US session on Friday.
Earnings this week:
- Monday: HCL Technologies; Fastenal
- Tuesday: Tech Mahindra; Aeon; Takashimaya; JPMorgan; Goldman Sachs; Citi; Johnson & Johnson; Wells Fargo
- Wednesday: HDFC Asset; Bank of Queensland; Bank of America; Morgan Stanley; ASML
- Thursday: Infosys; ABB, TSMC
- Friday: Tokyo Steel; American Express; Interactive Brokers; Volvo
FX:
- USD's safe-haven status diminished after President Trump criticized China's rare earth export policy, suggesting potential tariffs on Chinese imports. This prompted a risk-off sentiment, boosting the CHF and JPY. Concerns about a November US-China trade agreement resurfaced, yet the Dollar Index remained strong, ending the week around 98.97.
- AUD and NZD, with closer China ties, fell against the USD. AUDUSD dropping to around 0.6480 and NZDUSD fell to 0.5730.
- Canada’s employment data surprised positively with a 60.4k rise in jobs, keeping the unemployment rate at 7.1%, which helped stabilize USDCAD. USDCAD traded slightly below 1.40.
- In Japan, political shifts emerged as Komeito leader Saito signaled an exit from the coalition, weakening LDP leader Takaichi’s majority. JPY traded choppily around 152.
- Trump's tariff threat pushed USDCNH to 7.1481, complicating his upcoming meeting with President Xi and prompting consideration of various countermeasures.
Commodities:
- Oil prices rebounded as the Trump administration signalled openness to a deal with China, easing renewed trade tensions between the world’s two largest crude consumers. Brent recovered above $63 a barrel after Friday’s 3.8% slide, its sharpest since August, while West Texas Intermediate traded near $60.
- Silver whipsawed near a record as a historic London short squeeze and US-China trade tensions roiled markets, while gold set a fresh peak above $4,060 an ounce after an eighth consecutive weekly gain. Tariff fears lifted platinum and palladium by more than 2%, with silver up as much as 1.1% towards $51.
Fixed income:
- US 10-year Treasury futures trimmed Friday’s surge after President Donald Trump signalled openness to a China deal amid renewed trade tensions. The contract opened down 6 ticks in early Asian morning. Cash Treasuries were shut in Asia for a Japanese holiday. Australian sovereign bonds opened higher, but their two-day moves versus Treasuries remained muted despite the weekend headlines.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.