
Access all our platforms from a single account.

Asia Market Quick Take – November 24, 2025

Key points:
- Macro: US consumer sentiment near record lows in Nov
- Equities: US futures rise on Fed rate cut bets, Nvidia sales optimism
- FX: JPY halts slide on intervention talk; concerns over fiscal outlook
- Commodities: Oil extends losses after biggest weekly drop since early Oct
- Fixed income: Odds of a rate cut rise to nearly two-thirds
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- New York Fed President John Williams signalled scope to lower rates in the near term as the labour market softens, citing rising employment risks, easing inflation risks, and modestly restrictive policy, prompting investors to raise December cut odds to about 70% from roughly 35%.
- US consumer sentiment fell near record lows in November, with current conditions at a record and personal finances worst since 2009, as high prices, softer incomes, and job-loss risk (highest since July 2020) darkened the outlook.
- US officials are in early talks about allowing Nvidia to sell H200 AI chips to China, with no decision and licence approvals still required, and some in the Trump administration viewing it as a compromise concession to Beijing likely to face strong opposition from China hawks.
Equities:
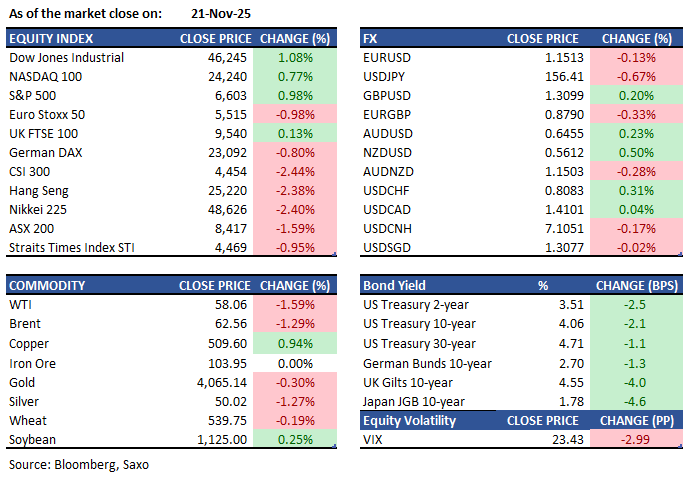
- US - US stocks rebounded Friday, with the Dow up 1.2%, S&P 500 gaining 1.1%, and Nasdaq rising 0.8%, after NY Fed President John Williams hinted policy could move toward neutral and traders boosted December rate-cut odds to nearly 70%. Communication services led early gains as Alphabet jumped 3.3% on Gemini 3 momentum and data center plans, while Meta and Intuit advanced. Later, tech weakened: Nvidia (-1%), Microsoft (-1.3%), Broadcom (-1.9%), AMD (-1.1%), and Oracle (-5.7%) fell as AI valuations faced scrutiny. Nvidia up 0.5% in post market after the Trump administration is considering allowing H200 chip sales to China.
- EU - European stocks fell Friday, with the STOXX 50 down 1% and STOXX 600 off 0.4%, reversing two days of gains as tech and AI concerns resurfaced. For the week, STOXX 50 dropped 2.3% and STOXX 600 lost 1.5%, echoing declines in Asia and the US. ASML slid 6%, Infineon fell 3.6%, and Prosus dropped 1.5%. Defense names weakened amid reports of a US–Russia peace proposal for Ukraine: Rheinmetall (-7.2%), Leonardo (-6.2%), Thales (-3.8%), and BAE Systems (-2.4%). Flash PMIs showed Eurozone activity strong in services, while Germany’s manufacturing stayed weak and service growth slowed.
- HK - Hong Kong’s Hang Seng plunged 615 points (2.4%) to 25,220 Friday, its lowest in five weeks, extending last week’s slide amid global equity volatility. Tech stocks dropped 3.2% to a three-month low, mirroring U.S. weakness, while consumer, property, and financial shares also fell as mainland markets hit mid-October lows. Weekly, the index sank 5.1%, reversing prior gains, as Tokyo-Beijing tensions escalated over seafood bans and travel warnings. Inflation rose to 1.2% in October, a four-month high, though officials expect muted price pressures. Major decliners included JD Health (-8.5%), SMIC (-6.3%), China Hongqiao (-4.4%), and Galaxy Entertainment (-4.3%).
Earnings this week:
- Monday
MISC, Want Want China, Kiwi Property Group, Prosus, Naspers, Couche-Tard, Agilent Technologies, Symbotic
- Tuesday
Alibaba, Chow Tai Fook Jewellery, Nio, Abercrombie & Fitch, Tongcheng Travel, Robosense Technology, Analog Devices, Dell, Workday, Compass Group, Zscaler, Best Buy, HP, Kohl’s
- Wednesday
Li Auto, Alibaba Health Information, Envision Greenwise, Rockwool, CD Projekt, Aroundtown, Tiger Brands, Strauss Group, Deere
- Thursday
Bosideng International, Sime Darby, Luk Fook Holdings, Ryman Healthcare, Oberbank, Asseco Poland, Remy Cointreau, CPI Europe, Grenergy Renovables
- Friday
Chagee, China Gas, China Water Affairs, CPI Property, Dottikon ES, 4iG, Kernel Holding, Electrica
FX:
- USD was steady on Friday, with DXY trading above 100. Fed Governor Williams suggested a possible rate cut in December, creating a dovish market shift, though the move softened after the BLS delayed the October CPI report.
- JPY outperformed in the G10, strengthening after Finance Minister Katayama signaled possible intervention against rapid FX moves. USDJPY traded near 156.70.
- GBP recovered from earlier losses tied to disappointing UK retail sales and Flash Services PMI. It rebounded in the US session with improved risk sentiment.
- EUR weakened after poor German and Eurozone PMI data. EURUSD traded in a tight range between 1.1492 and 1.1552.
- AUDUSD and NZDUSD reached session highs, boosted by overall positive risk sentiment during the US trading hours.
Commodities:
- Gold steadied as investors weighed the prospect of another Fed rate cut after NY Fed’s John Williams signalled scope to lower borrowing costs amid a softening labour market, even as other officials were more cautious; bullion pared losses Friday but still ended lower, and rose 0.1% to $4,070.08 after a 0.3% drop. Silver, platinum and palladium climbed.
- Oil extended losses after the biggest weekly drop since early October as traders weighed a potential Ukraine–Russia peace deal that could swell crude flows into an already well‑supplied market, with Brent above $62 and WTI below $58 after last week’s near-3% slump. European leaders and allies told the US the plan needs more work, seeking to temper a push to grant concessions to Russia and set terms by Thanksgiving.
Fixed income:
- Treasuries ended with modest gains led by the front end and belly, though off early highs after NY Fed’s John Williams signalled scope for a near‑term cut amid a softening labour market. Short‑dated rates priced higher December odds, the 5s30s steepened to the highest since 11 September, and traders now see nearly two‑thirds odds of a 10 December reduction versus about 35% before Williams spoke.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.