
Access all our platforms from a single account.

Cheap at the money, dear in the tail - Options Brief - 21 September 2026

Summary: Equity volatility kept draining out of the curve on Friday, and yet the crash measure rose and bond volatility jumped. The premium did not leave the market. The question is where it went.
Friday cleared the largest expiry of the quarter and equity volatility kept draining out of the curve. What did not drain was the tail. The crash measure rose on the same session the 30-day measure fell, and the bond market’s volatility gauge went up almost six percent with the US 10-year yield back at 5.00%.
Premium is not disappearing. It is changing address.
MARKET REGIME: TRANSITIONING | VIX 14.81 | TERM STRUCTURE: CONTANGO | SKEW: ELEVATED (148.10) | FRONT-MONTH VIX FUTURES: 17.86
- The at-the-money got cheaper and the tail got dearer. VIX fell 4.08% to 14.81 and VIX1D 12.96% to 11.42, while CBOE SKEW rose 2.40 points to 148.10.
- Volatility changed asset class rather than disappearing. MOVE rose 5.80% to 80.64 with the 10-year yield at 5.00%, on a session when every equity volatility measure on the board fell.
- Correlation made another low. COR3M fell 5.18% to 10.98 with dispersion at 33.19, and the index closed 0.17% higher while its equal-weighted version fell 0.48%.
Where the week’s range sits
What the option market has priced for this week, before a single session of it has traded.
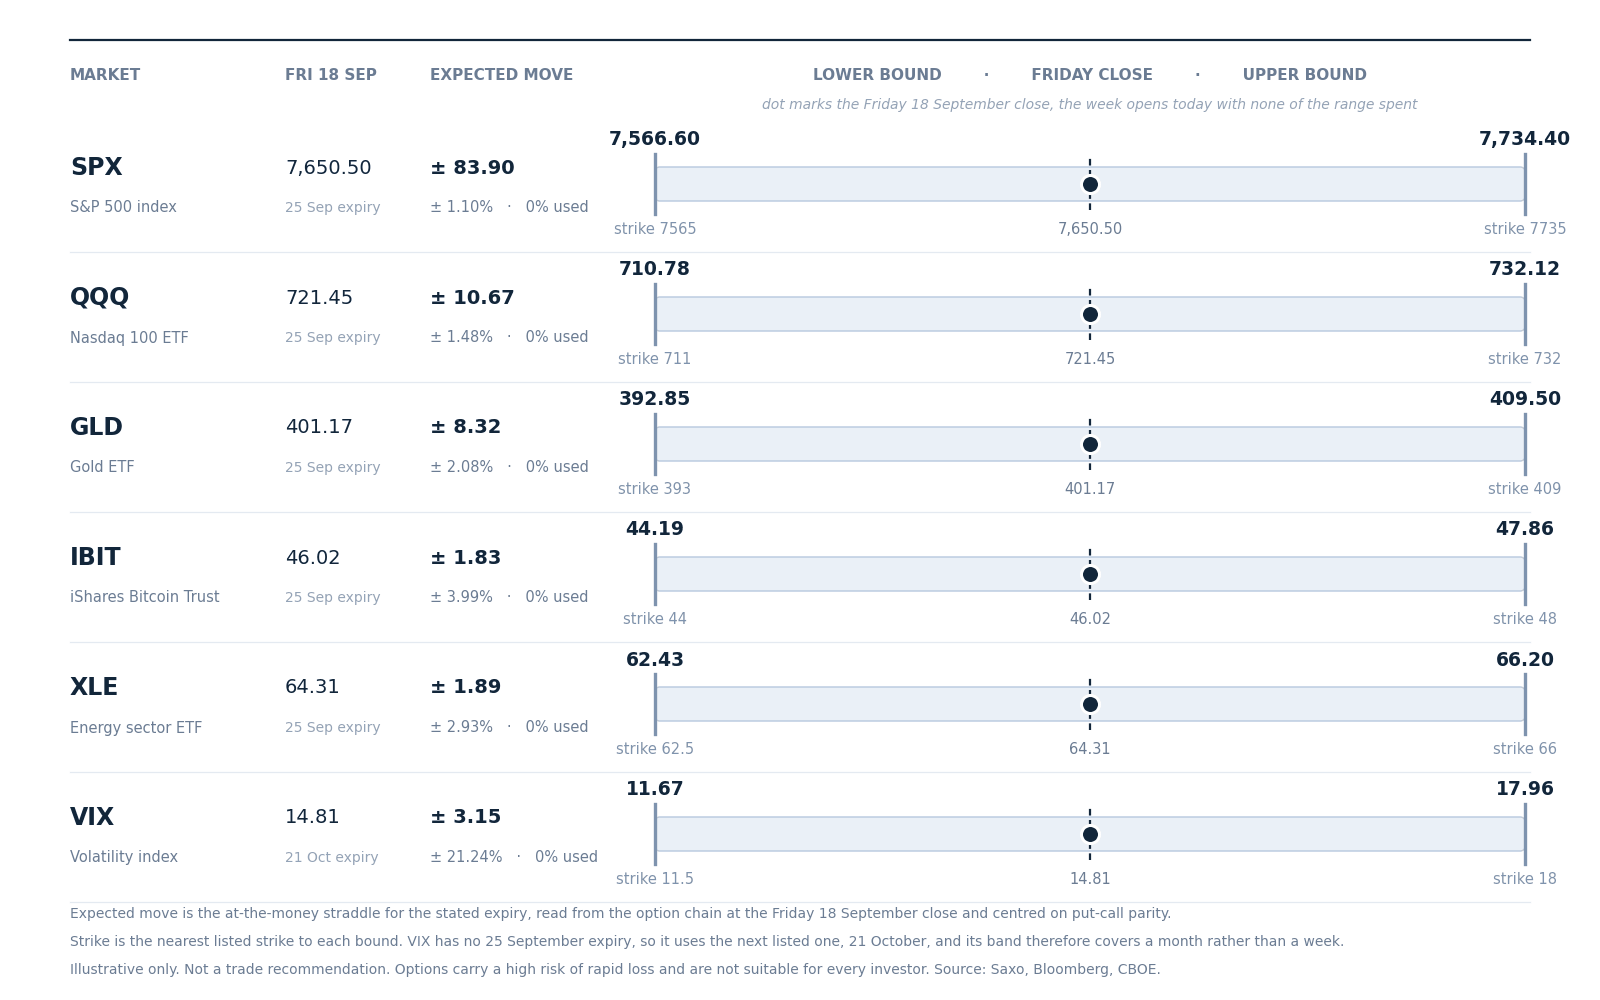 Expected move to the 25 September expiry, drawn around the Friday 18 September close, with the nearest listed strike at each bound. Volatility uses the 21 October expiry, the next one listed, so its band covers a month rather than a week. Read from the option chain at Friday’s close and centred on put-call parity, not a forecast.
- The equity bands have narrowed again. The S&P 500 has 83.90 points, or 1.10%, to work with and the Nasdaq 100 fund 1.48%, against 2.08% for gold, 2.93% for the energy fund and 3.99% for the bitcoin fund. A week ago the index band was 1.33%, and that week contained three rate decisions.
- Nothing has been spent, which is the point of showing it now. Every marker sits on its anchor because the week opens today. In our view a 1.10% band across a week holding global flash purchasing managers’ surveys and a US-China summit may prove thin, though a narrow band is the natural shape of a post-expiry week. Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply to exchange-traded fund trades; see Saxo pricing for costs and applicable charges.
Headline driver
US and Chinese officials began talks in New York to prepare for Thursday’s Trump-Xi summit, and the US Treasury Secretary described discussions on artificial intelligence, trade and investment as very successful.
Middle East supply fears eased in parallel, with oil and LNG flows through the Strait of Hormuz reaching a six-month high. More in Saxo’s macro coverage and today’s Market Quick Take.
Market snapshot
- US (Friday 18 September close): S&P 500 7,650.50, up 0.17%. Nasdaq 100 29,644.17, up 0.67%. Dow 51,688.16, down 0.18%. The equal-weight S&P 500 lost 0.48% and the Russell 2000 0.50%, a three-month low. Semiconductors carried the tape, the SMH fund up 2.21%, Broadcom 2.97% and AMD 2.70%, against Meta down 2.43% and Microsoft 0.80%.
- Europe (Friday 18 September close): a third consecutive weekly decline. The Stoxx 600 fell 1.11% to 635.46, the DAX 1.60% to 25,304.06, the CAC 40 1.49% to 8,065.02 and the Euro Stoxx 50 1.37% to 6,236.21. Banks were the weakest major sector at 2.25% lower and Volkswagen fell 5.6% after cutting its profit outlook. The Germany-France 10-year spread widened past 104 basis points, a 14-year high.
- Asia (Monday 21 September session, in progress): Japan is closed for a public holiday. The Kospi leads at 7,020.23, up 1.83%, with the Hang Seng 0.56% higher at 24,889.76 and the CSI 300 up 0.42%.
- Commodities and rates: Brent trades near USD 102 in a fourth straight decline and November WTI at USD 94.00, with Hormuz shipments at a six-month high. Gold is near USD 4,355, held back by a US 10-year real yield that ended the week at 2.67%, the highest in more than twenty years. The 10-year nominal yield is back at the 5.00% area and the 2-year rose eight basis points to a fresh cycle high above 4.74%. EURUSD 1.1475, USDJPY 156.97 after Friday’s reported rate check.
- Market regime: Transitioning, VIX 14.81, with the S&P 500 within half a percent of its 50-day moving average and 20-day realised volatility at 9.1%, falling.
Data source: Saxo, Bloomberg, CBOE, as of 21 September 2026, approximately 06:00 CET. Past performance is not indicative of future results.
Options flow sentiment
Based on end-of-day 18 September, Friday’s positioning and not today’s price action.
- Single-name flow calls took 81% of confirmed-opening premium across the tape, and almost none of it is readable as direction. The largest lines were deep in-the-money calls struck years out, printed at the mid and stacked across nine expiries at the same second, which is exposure being rolled on the quarter’s biggest expiry rather than a view. Where a side could be read it pointed the other way, with premium sold in memory and across the metals names.
- Sector and ETF flow the defensive funds were the exception and the more informative part of the tape. Roughly nine-tenths of confirmed-opening premium there sat in puts, in long-dated multi-leg downside packages on staples, healthcare and utilities running to 2029, with the far strike partly sold back. Named funds are market context only. Costs and charges apply to exchange-traded fund trades; see Saxo pricing for costs and applicable charges.
Volatility surface - 21 September 2026, approx. 06:00 CET
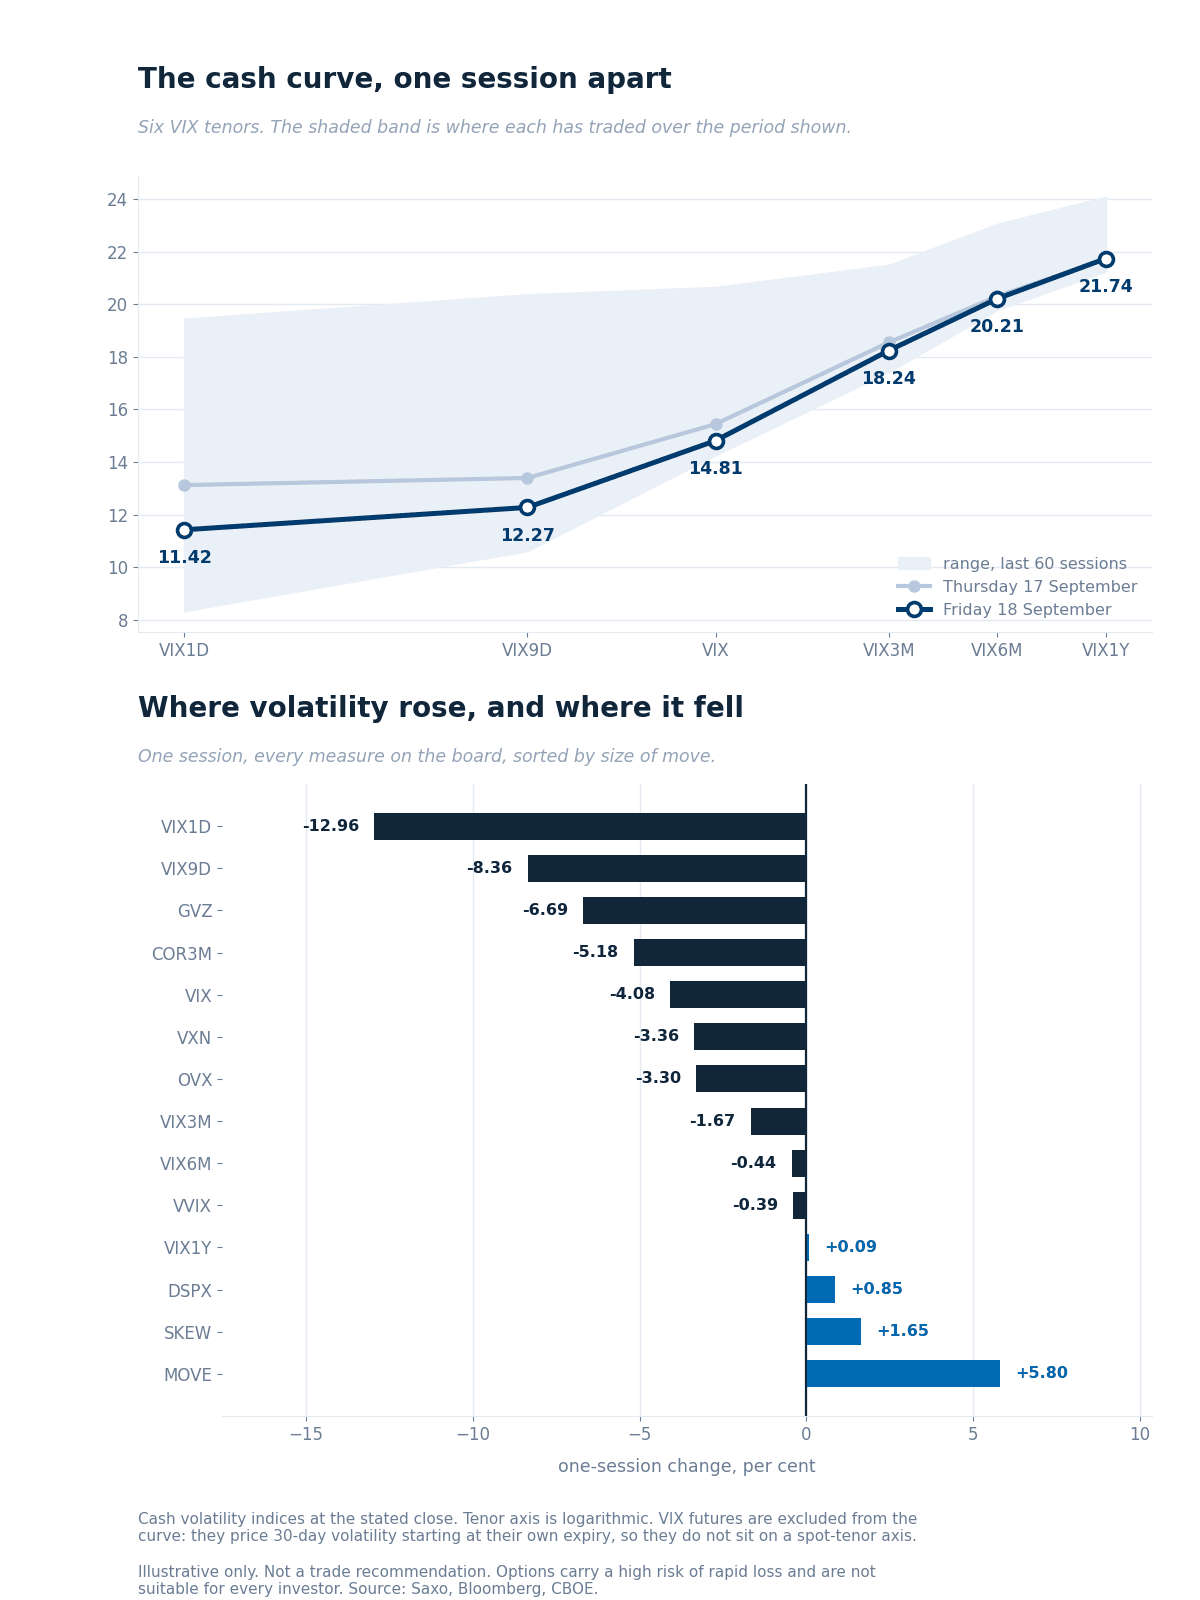 The six cash VIX tenors at Friday’s close against the previous session and the range each has held across 60 sessions, with the one-session change across every measure below.
Reading the curve
- The whole curve sits in the lower half of its three-month range and the front sits on the floor of it. VIX1D at 11.42 and VIX9D at 12.27 are the extremes; VIX1Y at 21.74 is the only measure on the board that closed higher.
- Ratios, which the graphic does not carry. VIX3M to VIX at 1.23, up 2.51%, and VXN to VIX at 1.30.
VIX futures
- Front-month 17.86, the October contract, confirmed by put-call parity at 17.99. Against a 14.81 cash close that is a premium of roughly 3.15 points, against 2.48 a session earlier.
- Second-month 18.53, ratio 0.965, contango. Neither future is in the graphic: both price 30-day volatility starting at their own expiry, so they do not sit on a spot-tenor axis.
Data source: Saxo, Bloomberg, CBOE, as of 21 September 2026, approximately 06:00 CET. Past performance is not indicative of future results.
Single-name volatility - where implied volatility sits against its own year
Saxo’s implied-volatility rank across 149 US and 328 euro-zone option underlyings. A rank of 0 is a one-year low, 100 a one-year high.
- Cheaper than a week ago, and cheapest on the index itself. The typical US name ranks 29.8, with only about one in nine above 50 and more than one in four sitting near a one-year low. Europe reads 31.7. The index group is again the cheapest corner of the list at a median rank of 10.2, which is the correlation reading told from the other side.
- Energy is the one rich sector. Energy ranks 53.8 at the median against technology at 29.8 and utilities at 26.0, after a fourth straight fall in crude. Exxon ranks 58, Chevron 54 and the energy sector fund 62.
- The rate funds are where this list disagrees with the index measures above. The 7-to-10-year Treasury fund ranks 26 on a level exceeded on only about two days in ten, and the 20-year fund ranks 38 against a percentile of 69. Rank measures distance from the year’s extremes, not how often a level has been seen, and on a session when bond volatility rose 5.80% that gap matters. Named funds are market context only. See Saxo pricing for costs and applicable charges.
Data source: Saxo, as of 21 September 2026, reflecting the 18 September close. Day counts are Saxo’s one-year implied-volatility percentile. Past performance is not indicative of future results.
What the market is pricing
- Session implied move. SPX options price about 0.50% to tonight’s close, roughly 38 points, derived from at-the-money option pricing rather than from any forecast. No scheduled US release lands inside a session that runs from 15:30 CET to the 22:00 CET cash close: the Chicago Fed activity index at 14:30 CET and the first Federal Reserve speaker at 12:30 CET both come before the opening bell.
- Event implied range. Friday’s expiry prices 1.13%, about 86 points. On Friday morning the same expiry carried 1.34% with six sessions to run, and flat volatility with one fewer session would have left roughly 1.22%. At 1.13% the market has taken a little under a tenth off the range on top of what the clock explains, which is a fall in implied volatility rather than decay.
- Tail risk signal. SKEW rose 2.40 points while the 30-day measure fell 4.08%, so the crash bid took no part in the unwind and firmed into it. In our view hedges may be being carried through the expiry rather than sold into the calm, leaving the surface cheaper at the money without being cheaper in the tail.
- Correlation and dispersion read. COR3M at 10.98, DSPX at 33.19 and index options at a median rank of 10.2 put a very low price on the index moving as one. In our assessment the index may look quiet because its components are cancelling each other rather than because any of them have stopped moving.
Options carry a high risk of rapid loss and are not suitable for every investor. Past performance is not indicative of future results.
Today’s catalysts
The Federal Reserve’s Goolsbee speaks at 12:30 CET, opening a heavy week of Fed appearances, and the US August Chicago Fed National Activity Index lands at 14:30 CET. Both fall before the 15:30 CET equity open. G7 foreign ministers meet on the sidelines of the UN General Assembly in New York.
Later this week: global flash purchasing managers’ surveys on Wednesday, the Trump-Xi summit on Thursday, and results from Autozone, Cintas, Paychex, Costco and H&M. Future outcomes are uncertain and may result in losses.
Conclusion
The expiry is behind us and roughly USD 7 trillion of notional has rolled off, removing the positioning that had been damping realised moves.
What is left is a surface that is cheap where most people look at it and not cheap where they do not: 11.42 at one day, 14.81 at thirty, and a crash measure at 148.10 that rose while both of those fell.
In our view the more useful question this week is not whether the index is calm but where the market has chosen to pay for insurance. It has paid in the tail, in rates, and almost nothing for the index moving as one. Options carry a high risk of rapid loss and are not suitable for every investor. Past performance is not indicative of future results.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it’s crucial to make informed decisions.
| More from the author |
|---|