
Access all our platforms from a single account.

Asia Market Quick Take – 21 September, 2026

Key points:
- Macro: BoJ raises rates to 1.25%. US-China officials in talks before summit.
- Equities: S&P 500 futures up this morning on lower oil prices
- FX: JPY slides to 157 after BoJ hike
- Commodities: Brent crude dips extending its losing streak to a fourth session
- Fixed income: 10-year Treasury yield rises back to 5%
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Trump said the Iran war will “end soon,” predicting US gasoline prices will fall, and confirmed talks with the Houthis, who “want a deal,” while not ruling out “annihilating” Iran. Tehran has told mediators it will resume talks only if fighting and the naval blockade end, its funds are unfrozen, and the Saudi‑Houthi war stops.
- BoJ lifted its key rate 25 bps to 1.25% in a 7–2 vote, the highest since 1995 and the quickest back-to-back hike since 1990, exposing divisions over the pace of tightening as inflation stays above its 2% target and is seen nearing 3% early next year.
- US and Chinese officials began talks in New York to prepare for the Trump–Xi summit, aiming to preserve and possibly extend the fragile trade truce.
- PBOC kept its key lending rates at record lows for a 16th straight month in September 2026, holding the 1-year LPR at 3.0% and 5-year at 3.5%, as it stayed cautious over Middle East conflict risks despite a stronger yuan and overseas rate hikes. Industrial output picked up, but retail sales and new loans disappointed, while housing prices fell again, albeit at the slowest pace in eight months on policy support.
- Trump said he would “probably” be open to meeting Iranian President Masoud Pezeshkian at the UNGA, alongside possible talks with other Gulf leaders and a planned summit with China’s Xi. Qatar’s prime minister urged Gulf cooperation and confirmed US‑Iran message exchanges, while US Central Command reported oil and LNG flows through the Strait of Hormuz at a six‑month high.
- US industrial production was flat in August, missing a 0.3% forecast after July’s 0.2% gain. Manufacturing fell 0.3%, while mining edged up 0.1% and utilities rose 1.8%. Capacity utilisation was unchanged at 76.3%, 3.1 points below its long-run average.
- US manufacturing output fell 0.3% in August, ending a seven‑month run and missing a 0.3% gain forecast, as durable goods slid 0.5% while nondurables were flat. Capacity utilisation dipped to 75.7%, 2.5 points below its long‑run average.
- Euro area inflation expectations in August 2026 rose to 3.0% for the next 12 months, 2.9% in three years, and 2.5% in five years. Lower-income and older households still see higher inflation than richer and younger groups. Income growth is expected at 1%, GDP growth at -1.2%, unemployment at 11%, and home prices and mortgage rates are seen up 3.4% and 4.9% over the next year.
Equities:
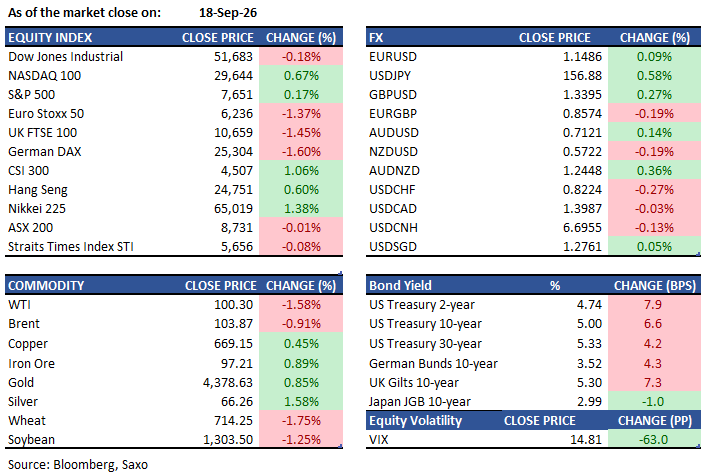
- US -S&P 500 (7,650) eked out a small gain, led by Information Technology and Industrials, while the Dow Jones (51,683) and Russell 2000 (2,860) fell to three-month lows. The Nasdaq 100 (29,644) rose modestly amid sector rotation in growth stocks. The 10-year yield hitting 5% weighed on sentiment. Steel names were notable laggards — Steel Dynamics fell ~3.8% and Nucor dropped ~4.8% after both issued below-consensus Q3 guidance. Automakers also slid after Volkswagen cut its profit outlook, with GM down ~4.9% and Ford off ~3.9%. SpaceX's Nasdaq 100 weighting was confirmed at 2.82% effective today's quarterly rebalance, up from ~1.28%. S&P 500 futures are up 0.3% and Nasdaq 100 futures up 0.4% in early Asia trade this morning.
- EU - European equities fell sharply on Thursday 18 September, marking a third consecutive weekly decline. The Stoxx Europe 600 dropped 1.1% to 635.45, the DAX fell 1.6% to 25,304, the FTSE 100 lost 1.5% to 10,659, and the Euro Stoxx 50 ended the week 1.4% lower at 6,236. Volkswagen was the standout mover, falling 5.6% after cutting its operating margin forecast due to a sharp contraction in the Chinese car market and a writedown on its Porsche stake. Nestle fell 2.6% after Russia took over its assets in the country. Banco Santander was the largest drag on the Stoxx 600, declining 3.3%. Greece's reclassification as a developed market takes effect today, with nine stocks including four banks entering the Stoxx 600.
- Asia - Asian equities are edging higher this morning with the MSCI Asia Pacific gauge up ~0.2%, supported by optimism around the upcoming US-China summit. Japan's Nikkei (65,019) is closed for a public holiday. The Hang Seng (24,751) closed up 0.6% on Friday, its best day since 4 September, led by Alibaba (+4.0%) and Lenovo (+9.5%), with mainland investors recording a 10th consecutive day of net purchases via Stock Connect. The Kospi (6,988) is the standout performer in Asia this morning, up 1.4%, with tech names leading after foreign selling snapped a seven-day streak on Friday. The STI (5,656) is flat. Grab's acquisition of a 60% stake in BNPL platform Atome Financial for US$1.5 billion is a notable Singapore corporate development this morning. Hong Kong property stocks remain under pressure following the HKMA's rate hike in lockstep with the Fed, with Sun Hung Kai and Hang Lung Properties down over 3.4% last week.
Earnings this week:
- Tuesday: AutoZone (Q4 2026), KB Home (Q3 2026), Worthington Enterprises (Q1 2027)
- Wednesday: Cintas (Q1 2027), General Mills (Q1 2027)
- Thursday: Darden Restaurants (Q1 2027), Costco Wholesale (Q4 2026, after market)
Key Events:
- Thursday, 24 September: Trump-Xi Summit
FX:
- USDJPY is hovering near 156.95 after Friday’s 1.3% yen slide on a BOJ hike with dissent and scant guidance, leaving the currency vulnerable amid thin holiday liquidity and reported BOJ rate checks. The dollar is broadly firm, with the Bloomberg Dollar Spot Index up 1.1% last week, its best since June.
- AUDUSD is steady around 0.7123 after a 0.7% weekly drop as traders weigh Middle East risks and US‑China talks and NZDUSD at 0.5220.
- Asian FX remains under pressure from the Fed’s hawkish stance, led by a weaker won (USDKRW 1,386.6).
- USDCNH is stable near 6.6947, with the yuan increasingly eyed as an alternative funding currency as yen carry returns shrink.
Commodities:
- Brent crude is at $103.41/bbl, down ~0.4% this morning and falling for a fourth consecutive session. WTI is at $99.70/bbl. Supply concerns are easing as Hormuz shipments hit a six-month high and Saudi Arabia works to restore its East-West pipeline. Diplomatic efforts to end the US-Iran conflict are also reportedly intensifying.
- Spot gold is at $4,371/oz, marginally softer today (-0.2%) but holding near historically elevated levels. The metal has been supported by geopolitical risk, inflation concerns, and central bank demand. Real 10-year US yields rose 5bps to 2.67% on Friday, which may cap near-term upside.
Fixed income:
- The US 10-year yield is at 4.998%, having breached 5% for the first time since 2023 last week. The move was driven by the Fed's hawkish hike, elevated oil prices, and fiscal supply concerns. KKR has raised its year-end 10-year yield target to 5.1%, citing Chair Warsh's persistent inflation concerns.
- The 2-year yield is at 4.748%, near multi-year highs, as markets price in further Fed hikes. The 2s10s spread has flattened toward year-to-date lows near 24bps, and the 5s30s spread compressed to its lowest since March 2025. Investors are increasingly shifting into shorter-dated Treasuries as a bet on the Fed eventually winning its inflation fight. The 30-year Treasury yield is at 5.328%, near levels last seen in 2007.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.