
Access all our platforms from a single account.

Asia Market Quick Take – 07 October, 2026

Key points:
- Macro: Japan real wages up 8th month, longest in nearly a decade
- Equities: S&P 500 closes at record high, up 0.6% as Nvidia approaches $6T
- FX: Dollar eases from highs; GBP, CAD lead G10; EUR, JPY stay pressured
- Commodities: Brent crude recovers losses to settle above $100
- Fixed income: French bonds rally on Le Pen’s deficit-cut plan
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Vitol CEO warns that tanker shortage is disrupting Gulf oil flows, pushing charter costs higher, resulting in $200 a barrel oil scenario.
- The US trade deficit widened 13.7% month-on-month to $105.6 billion in August, above the consensus estimate of $102.1 billion and the largest shortfall since early 2025. Imports rose 4.3% to a record $420.8 billion, while exports gained 1.4% to $315.2 billion. US goods exports to China fell 12.5% month-on-month.
- ADP data showed US private payrolls rose an average of 23,750 per week in the four weeks ending September 19, consistent with a cooling labour market following last Friday's nonfarm payrolls print of just 29,000 — below all economist estimates.
- US same-store retail sales rose 8.6% year-on-year in the week ending October 3, boosted by Amazon Prime Big Deal Days and competing promotional campaigns from major retailers.
- Treasury Secretary Scott Bessent sought to reassure markets that US debt is manageable through a combination of economic growth and spending restraint, though market strategists were broadly sceptical. Ray Dalio warned that China and Japan may pull back from US Treasuries, noting the US relies on foreign capital for roughly a third of its debt.
- Japan real wages rise eighth straight month, longest in nearly a decade; August real earnings +1.5% YoY on 3.8% base-pay gains, aided by PM Sanae Takaichi’s inflation relief.
Equities:
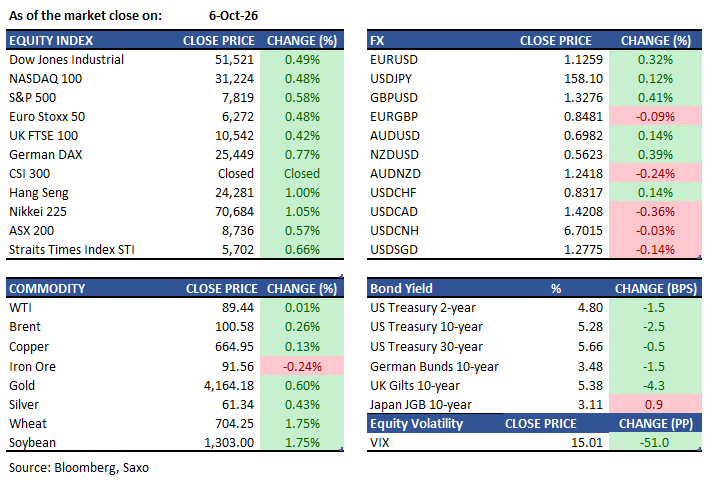
- US — S&P 500 closed at a record high on Tuesday for the first time since August, rising 0.6% to 7,818.93, its fourth consecutive advance. The Nasdaq Composite gained 0.5% to 27,599.79, its 24th record close of 2026 and fifth straight up day. The Dow Jones rose 0.5% to 51,521.28. Nvidia approached a $6 trillion market cap after SpaceX seeks $40b financing to buy Nvidia chips, while AMD's Lisa Su predicted "very high" chip demand. Alphabet's 20-year nuclear power deal with Constellation Energy lifted utility stocks, with Constellation gaining 12.2%. Lennar rose 4.0% after Berkshire Hathaway disclosed a $193 million purchase of its shares.Apple partners LG in a push for smart home devices including a doorbell, thermostat and other accessories.
- EU — European equities rose for a third consecutive session on Tuesday. The Stoxx 600 gained 0.5% to 636.63, led by banks, with SAP (+1.9%) the largest contributor and Valeo (+5.5%) the top individual mover. The DAX rose 0.8% to 25,449.19, with Continental (+2.8%) leading. The FTSE 100 climbed 0.4% to 10,541.69, with AstraZeneca (+1.7%) and Whitbread (+5.2%) outperforming. The SMI added 0.6% to 13,788.93. Softer oil prices and a rally in French government bonds — after Marine Le Pen proposed bringing France's deficit below 3% of GDP by 2032 — supported sentiment. Goldman Sachs reiterated an underweight stance on European equities, citing political risks in France, Italy and Spain.
- Asia — Asian markets are taking their cue from Wall Street's record-breaking session, though the handoff is uneven. Japan's Topix rose 0.4% to 4,160.75 on Tuesday, supported by US tech gains and lower oil prices, with Advantest and Chiba Bank hitting record highs. The Nikkei advanced 0.4% to 70,258.02. Topix futures are set up for further gains, with SpaceX's reported plans to raise funds to buy Nvidia chips adding fuel to AI themes. The Hang Seng climbed close to 1% on Tuesday, with TSMC, Alibaba and Tencent among the leaders. The Kospi is opening on the back foot this morning, dragged by memory heavyweights SK Hynix and Samsung Electronics tracking overnight weakness in US memory peers, with the DRAM ETF having dropped 3.5% overnight. The STI is broadly steady. Equity-index futures for South Korea and Taiwan edged lower, while Japan and Hong Kong futures pointed to modest gains.
Earnings this week:
- Thursday: PepsiCo, Seven & i Holdings, Fast Retailing
- Friday: Delta Air Lines
FX:
- USD eased slightly from recent highs as US yields and oil pulled back, leaving the USD broadly steady in early Asia.
- USDJPY traded above 158, with the yen near multi‑month lows and the 55‑day moving average key for a potential move toward 160.
- GBP outperformed, with cable posting its biggest daily gain since August and holding near 1.3260 on improved risk sentiment and a softer dollar.
- EURUSD recovered modestly but remains pressured by French fiscal and wider European political worries, even as French bonds rallied on Le Pen’s deficit‑cut pledge; EURJPY stays heavy amid reported Japanese repatriation from French bonds.
- CAD was the best G10 performer as USDCAD fell to 1.4210, though further loonie upside is seen as limited given fair value versus rate differentials.
- In Asia, KRW gained slightly with USDKRW around 1,340, supported by the weaker dollar but constrained by cautious equity sentiment, while USDSGD remains range‑bound near 1.278 ahead of the MAS meeting.
Commodities:
- Brent crude settled near $101 a barrel on Tuesday after swinging sharply intraday, at one point dropping as much as 3.3% before recovering. Prices are being pulled in opposite directions by rising Middle Eastern export flows through the Strait of Hormuz and Iran's refusal to fully reopen the strait until the US meets seven conditions. Saudi Aramco cut the price of Arab Light to Asian buyers to $5 below the regional benchmark for November — the lowest since 2020 — signalling ample physical supply.
- Gold futures rose 0.9% to $4,194.80 per troy ounce on Tuesday, continuing to benefit from geopolitical uncertainty and elevated inflation concerns stemming from the US-Iran conflict and the global bond rout.
Fixed income:
- The 10-year Treasury yield fell 3.8 basis points to 5.271% on Tuesday, while the 30-year yield eased 2.2 basis points to 5.644%, pulling back from Monday's peaks of 5.34% and 5.70% respectively — the highest levels since 2002. The rally was supported by lower oil prices and a bid in European government bonds. Traders, however, continue to reload short positions, with open interest rising and signalling the selloff may resume.
- The US Treasury sold $58 billion in 3-year notes at a yield of 4.932%, stopping through the when-issued level and drawing a bid-to-cover of 2.62. The solid result provided some reassurance ahead of heavier duration supply: a $39 billion 10-year note sale is due Wednesday and a $22 billion 30-year bond reopening on Thursday.
- French, Italian and Greek government bonds sharply outperformed on Tuesday, with the French bond rally driven by Le Pen's deficit reduction proposal. Japan's 10-year auction saw stronger-than-average demand as elevated yields attracted buyers, with the 10-year JGB yield edging up 1 basis point to 3.095%. Ray Dalio's warning that China and Japan may reduce Treasury holdings added a longer-term overhang to the market.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.