
Access all our platforms from a single account.

Asia Market Quick Take – 06 October, 2026

Key points:
- Macro: France political gridlock deepens; Spain PM calls snap election.
- Equities: Nasdaq Composite gains 1.05% to close at record high
- FX: USD gains on European fiscal, political stress; EUR hits 17‑month low
- Commodities: WTI extends losses dipping below $90
- Fixed income: US Treasuries sinks further in a bear-steepening move
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- US 10-year real yields rose to 2.94%, heading for an 18-year closing high, as the bond selloff extended despite the soft jobs print. August CPI held at 3.4% year-on-year; the next release is due 14 October.
- France's fiscal and political gridlock deepened, with OAT-Bund spreads widening to multi-year highs before domestic real money buyers stepped in. Spain's Prime Minister called a snap election, adding to European political risk.
- Germany's composite PMI for September rose to its highest level since just before the Middle East conflict began in February, offering a rare bright spot for the eurozone.
- Iran's parliament speaker stated Tehran will not fully reopen the Strait of Hormuz until the US meets seven conditions, keeping geopolitical risk elevated in energy markets.
- Brazil’s right wing candidate Bolsonaro leads election,
- Saudi Aramco cut the price of Arab Light crude to Asian buyers to $5/bbl below the regional benchmark for November — the lowest since 2020 — signalling loosening physical supply as Gulf exports recover.
- OpenAI is reportedly in talks with multiple UAE investment funds to anchor a $30 billion financing round.
Equities:
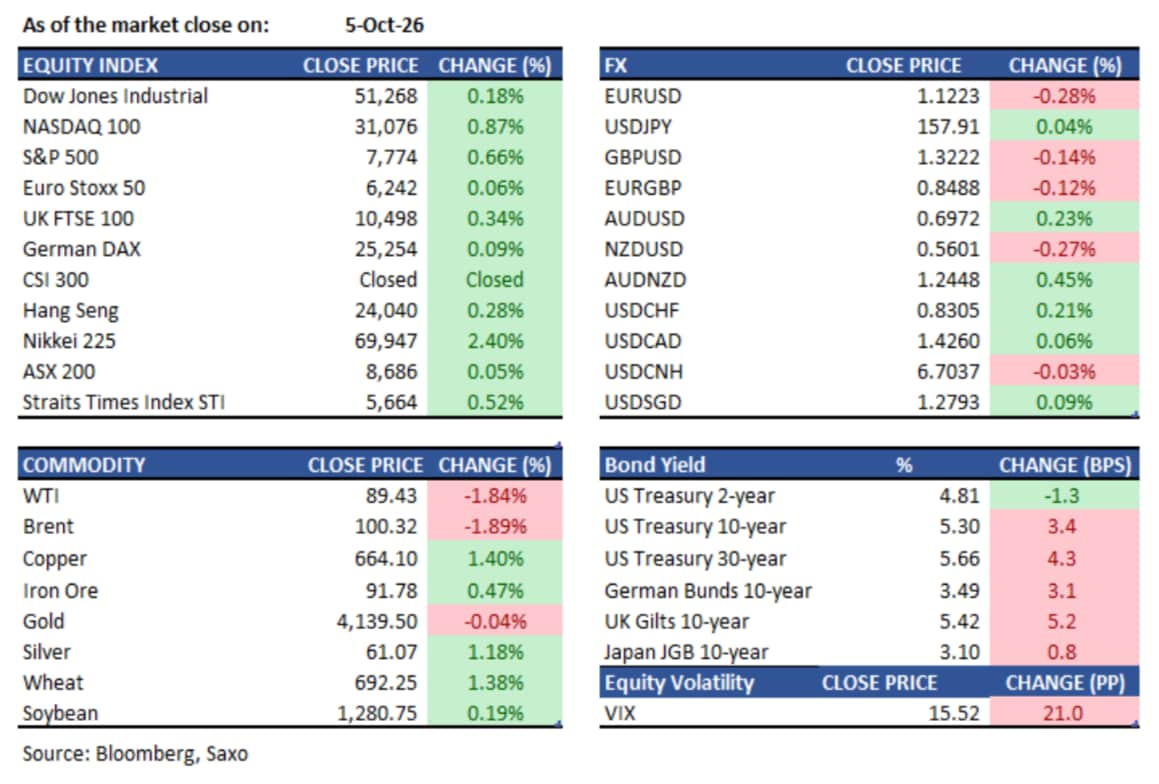
- US — On Monday, the S&P 500 rose 0.7% to 7,773.95, closing near its all-time high, while the Nasdaq Composite hit a record close of 27,477.31 (+1.05%), its 23rd record close of 2026. The Dow added 0.2% to 51,267.90. Nvidia (+2.1%) and Microsoft (+1.6%) led gains; Meta (+2.1%) and Tesla (+2.5%) also outperformed. PTC surged 33.5% after Schneider Electric agreed to acquire it for ~$22.6 billion. Nike price targets were cut by an average of 20% across 24 analysts post-earnings. In after-hours, Option Care Health (OPCH) surged ~22% on reports McKesson and Clayton Dubilier & Rice are closing in on an acquisition.
- EU — European stocks closed mixed on Monday. The Stoxx 600 rose 0.4% to 633.62, led by banks and commodity stocks. The FTSE 100 gained 0.3% to 10,497.94, with HSBC and Standard Chartered among top performers. The DAX was little changed at 25,254.21, with Rheinmetall up 2.4%. The CAC 40 fell 0.8%, dragged by Schneider Electric (-10%) on its PTC acquisition announcement. French bank credit risk surged, with Societe Generale CDS rising above Deutsche Bank levels. Euro Stoxx 50 ended marginally higher at 6,242.14.
- Asia — Asian markets rallied on Monday, tracking the US tech-led advance and softer payrolls data. Japan's Nikkei surged 2.5% to 70,001.80, led by AI and semiconductor names tracking the Philadelphia Semiconductor Index's 2.4% gain. South Korea and mainland China were closed for holidays; the Kospi is expected to play catch-up today with room to run following Friday's strong EWY performance. Hong Kong's Hang Seng is set to open higher — the Nasdaq Golden Dragon China Index rose 1.7% on Monday. The ASX 200 rose 0.4% to 8,720.30, led by real estate and materials. Hon Hai (Foxconn) beat Q3 revenue estimates with NT$3.03 trillion in sales, up 47% YoY, signalling sustained AI infrastructure demand. STI data was not separately reported overnight; broader ASEAN markets were mixed with the rupiah slipping on dollar strength.
Earnings this week:
- Thursday: PepsiCo, Seven & i Holdings, Fast Retailing
- Friday: Delta Air Lines
FX:
- USD broadly firmer, particularly against European currencies, as mounting fiscal and political risks in Europe drove safe-haven demand into USD.
- EUR was the main underperformer, with EURUSD dropping intraday to a 17‑month low around 1.1161 before closing at 1.1222, pressured by France’s worsening fiscal crisis and reports of possible snap elections in Spain; this weakness also prompted banks such as Citigroup to cut their EURUSD forecasts.
- GBP softened in sympathy, with GBPUSD edging lower to 1.3222, while USDCHF also climbed, reflecting the broader pressure on European FX.
- AUD outperformed G10 peers, with AUDUSD up to 0.6972 as investors viewed Australia as relatively insulated from Europe’s fiscal troubles; NZD, CAD and CHF were all weaker versus the dollar.
- USDJPY was little changed, leaving the yen broadly range‑bound around 157.9.
Commodities:
- Oil extended its decline, with WTI settling near $89/bbl (-1.8%) and Brent near $100 on Monday, as Saudi Aramco's deep price cut to Asian buyers and rising Persian Gulf export volumes through the Strait of Hormuz reinforced signs of a loosening physical market. WTI has shed 3.7% over the prior two sessions.
- Gold steadied near $4,140/oz on Monday, paring earlier gains as a stronger dollar weighed. The metal remains well-supported above $4,100 but faces headwinds from rising real yields and dollar strength tied to European political uncertainty.
- Copper edged higher on Monday, tracking the pullback in Fed rate hike expectations following the weak payrolls print. Copper futures were up ~1.2% at $14,434.50/mt during the session, though a stronger dollar and European debt concerns capped the upside.
Fixed income:
- US Treasuries sold off further on Monday in a bear-steepening move. The 10-year yield rose to 5.34% and the 30-year touched 5.70% intraday — both fresh 24-year highs since 2002 — before paring slightly into the close. The 5s30s spread widened to 60bps from 56.8bps. This week's key duration risk events include 10-year ($39bn) and 30-year ($22bn) auctions on Wednesday and Thursday respectively.
- European sovereigns saw the OAT-Bund 10-year spread narrow 4bps to 137bps on Monday after domestic real money buyers stepped in for a second consecutive day. BTP-Bund spread held steady at 114bps. ECB rate hike pricing eased to ~23bps by year-end from 25bps on Friday.
- US T-bill auctions on Monday showed buyers preferring the 6-month tenor ($82bn at 4.165%) over the 3-month ($95bn at 4.05%), suggesting investors are more willing to extend duration as Fed hike bets recede. Goldman Sachs strategists noted that ingredients for yields to move lower — weak jobs, dovish Fed commentary, and widening credit spreads — are beginning to emerge.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.