
You can access both of our platforms from a single Saxo account.

Fed day prices like a month - Options Brief - 16 September 2026
Summary: One session of S&P 500 volatility now costs the same as thirty days, and the Federal Reserve has not spoken yet. Two sessions have already spent most of the range priced for the whole week.
MARKET REGIME: TRANSITIONING | VIX 17.20 | TERM STRUCTURE: CONTANGO | SKEW: ELEVATED (146.61) | FRONT-MONTH VIX FUTURES: 18.45
- The front of the volatility curve closed its gap overnight. VIX1D rose 42.60% to 17.14, the nine-day measure 1.77% to 17.21 and the 30-day 0.58% to 17.20. Three tenors now sit within 0.07 of one another.
- Friday’s window took on premium for a second night. The 18 September expiry prices 1.29%, roughly 98 points, where one fewer session at unchanged volatility would have left about 87.
- Two sessions have spent most of a five-session range. The S&P 500 has used 70% of the 101.65 point move priced for the week around Friday’s close, the Nasdaq 100 fund 79%, and the VIX 121%.
Where the week’s range sits
What the option market priced for this week around Friday’s close, and how much of it the first two sessions used.
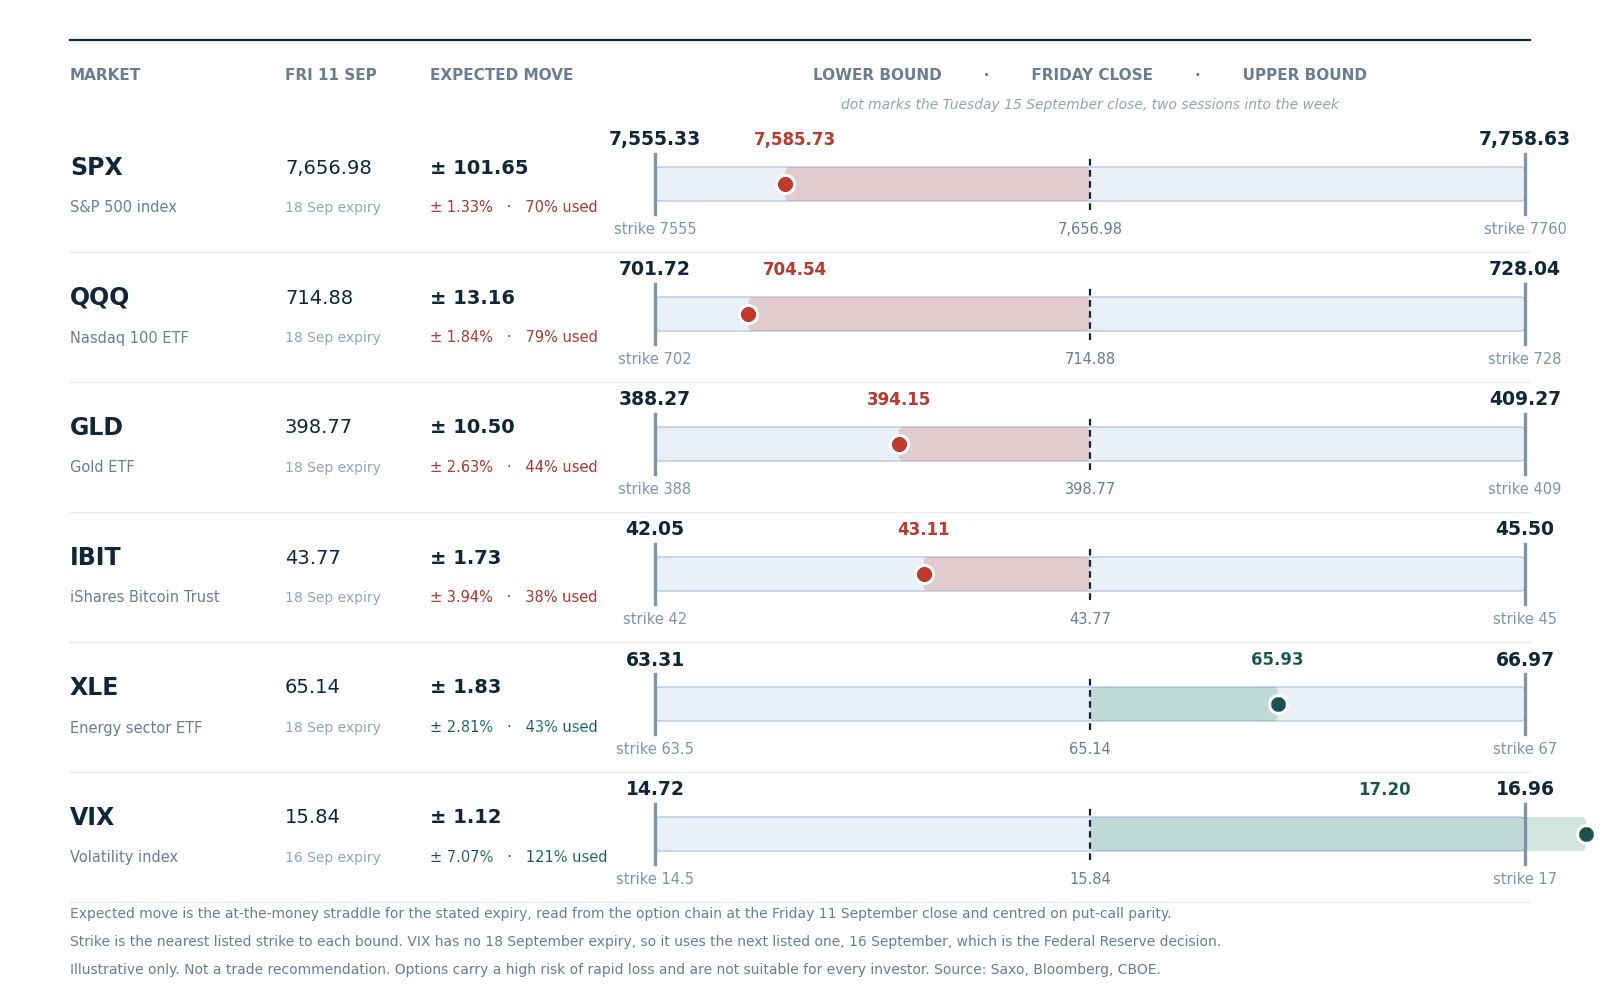
Expected move to the 18 September expiry, drawn around the Friday 11 September close, with the nearest listed strike at each bound. Volatility uses the 16 September expiry, the next one listed. Read from the option chain at Friday’s close and centred on put-call parity, not a forecast.
- Equities are three quarters spent with the decision still ahead. The S&P 500 has travelled 70% of its band and the Nasdaq 100 fund 79%, both to the downside, with three sessions and a Federal Reserve decision left to run. Gold has used 44%, the bitcoin fund 38% and the energy fund 43%, the last of those upward.
- Volatility is the row that has already left the band. The VIX has covered 121% of the 1.12 point move the chain priced for the full week, and it did so before the event the week was built around. In our view a market that spends its equity range ahead of the catalyst rather than on it may be saying the adjustment happened in the bond market first. Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply to exchange-traded fund trades; see Saxo pricing for costs and applicable charges.
Headline driver
The Federal Reserve decides today, with rate markets pricing roughly a 94% chance of a 25 basis point increase that would lift the target range to 3.75% to 4.00%.
Ahead of it the US 10-year Treasury yield briefly cleared 5% for the first time since 2007, peaking just under 5.04% before easing back below 4.99%, while Brent held near USD 108 after a September gain of almost 20%. More in Saxo’s macro coverage and today’s Market Quick Take.
Market snapshot
- US (Tuesday 15 September close): S&P 500 7,585.73, down 0.45%. Nasdaq 100 28,937.84, down 0.65%. Dow 52,093.11, down 0.63%. Chevron and ExxonMobil each rose 2.6% on firmer crude, while Coinbase fell 10.1% and Circle Internet 11.4% after the US Senate failed to advance digital asset market-structure legislation.
- Europe (Tuesday 15 September close): Stoxx 600 634.19, down 0.28%, with financials leading the decline. HSBC lost 2.2% and London Stock Exchange Group 3.2%. LVMH fell 2.6%, letting L’Oréal overtake it as France’s most valuable listed company.
- Asia (Wednesday 16 September session): the Nikkei 225 gained 0.3% and the Kospi 1.15% as Samsung Electronics and SK Hynix recovered from recent weakness. Hong Kong stayed softer after Tuesday’s 1% decline.
- Commodities and rates: Brent USD 108.15 and WTI USD 104.73, easing as flows through the Strait of Hormuz picked up. Gold near USD 4,320 and silver USD 65.12. The US 10-year yield trades 4.99% and the 2-year 4.65%. EURUSD 1.1542, USDJPY 155.38.
- Market regime: Transitioning, VIX 17.20, with the S&P 500 sitting 0.33% below its 50-day moving average and 20-day realised volatility at 8.8% and falling.
Data source: Saxo, Bloomberg, CBOE, as of 16 September 2026, approximately 06:00 CET. Past performance is not indicative of future results.
Options flow sentiment
Based on end-of-day 15 September, yesterday’s positioning and not today’s price action.
- Single-name flow the semiconductor tape carried the session’s largest confirmed-opening total at USD 880.7m and split 81.8% to calls, but the size sat in deep in-the-money contracts into Friday’s quarterly expiry, printed at mid with no aggressor side attached. The mega-cap tape ran USD 162.8m with 60.8% in puts and the same deep in-the-money character. In our view this is expiry-week position management rather than a directional statement, and the one clean event-dated purchase on the tape was a single day of downside in one social media name.
- Sector and ETF flow the index complex carried USD 2.22bn and leaned 55.6% to puts, but the repeated shape was long-dated index downside financed by selling nearer-dated downside, which is protection being built and paid for rather than a bet on a lower market. Energy ran close to balanced at USD 43.0m, with crude fund downside bought outright against producer upside supplied. Named funds are market context only. Costs and charges apply to exchange-traded fund trades; see Saxo pricing for costs and applicable charges.
Volatility surface - 16 September 2026, approx. 06:00 CET
VIX term structure
- VIX 17.20, up 0.58%.
- VIX1D 17.14, up 42.60%, and VIX9D 17.21, up 1.77%.
- VIX3M 19.36 · VIX6M 20.76 · VIX1Y 21.88.
VIX futures
- The September contract settles today, so the continuous front-month series at 18.450 now represents October and no session comparison is drawn from it.
- The second-month series reads 19.000, leaving the front-to-second ratio at 0.970 and the listed curve in contango above spot.
Skew and correlation
- CBOE SKEW 146.61, down 5.48 points.
- COR3M 12.41, up 3.16%. DSPX 31.81, up 0.38%.
Other vol measures
- VVIX 94.91, up 0.02% · MOVE 83.71, down 0.23%.
- VXN 22.26, up 0.95%.
- GVZ 26.90, up 1.36%.
Data source: Saxo, Bloomberg, CBOE, as of 16 September 2026, approximately 06:00 CET. Past performance is not indicative of future results.
What the market is pricing
- Session implied move. Today’s expiry prices 0.80%, about 61 points, against 0.51% quoted for the equivalent session yesterday morning. The decision lands at 20:00 CET and the press conference at 20:30 CET, both after the cash close, so the priced range covers a session that ends before the news.
- Event implied range. The 18 September expiry prices 1.29%, roughly 98 points, against 100.90 points quoted yesterday morning, where one fewer session at unchanged volatility would have left about 87. Roughly 11 points went in overnight, the second consecutive night of addition. In our assessment paying to hold a window open while the clock runs against it remains the clearest thing the option market has said this week.
- Term-structure read. One session of volatility rose 42.60% while thirty days rose 0.58%, collapsing a gap of more than five points into 0.06. In our view a curve that flat at the front may be treating the decision as the whole of the week’s risk rather than the start of a broader repricing.
- Cross-asset read. Oil volatility sits at 61.73, up 3.82% and 3.59 times the equity measure, while three-month implied correlation rose 3.16% to 12.41 from a historically low base. In our assessment the market may be pricing the energy complex, not the index, as the live source of risk.
Options carry a high risk of rapid loss and are not suitable for every investor. Past performance is not indicative of future results.
Today’s catalysts
The UK published August inflation at 08:00 CET. The eurozone reports July industrial production at 11:00 CET and the US August retail sales at 14:30 CET, with weekly US crude and fuel stocks at 16:30 CET.
The Federal Reserve decision follows at 20:00 CET and the press conference at 20:30 CET. Friday brings the quarterly expiration inside the same window. Future outcomes are uncertain and may result in losses.
Conclusion
In our assessment, the option market spent the night doing two things at once: pulling a single session up to the price of a month, and adding premium to a Friday window that should have been decaying.
The pairing of a 0.80% same-day range with a 1.29% range to Friday suggests the market may be treating today’s announcement as an event whose consequences are felt after it, in the two sessions that follow, rather than in the hours around it, though that reading could change on a single headline and options carry a high risk of rapid loss and are not suitable for every investor. Past performance is not indicative of future results.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it’s crucial to make informed decisions.