
Access all our platforms from a single account.

Global Market Quick Take: Asia – August 5, 2025

Global Market Quick Take: Asia – August 5, 2025
Key points:
- Macro: US threatens higher tariffs on India and Swiss looks to present a better offer
- Equities: Palantir shares rose 4.6% post-market after surpassing $1 billion revenue
- FX: CHF impacted by Trump's tariffs; Switzerland seeks better US trade terms
- Commodities: Oil steadied after a three-day drop amid Russian supply risks
- Fixed income: Treasuries extend gains while yield curve flattens
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- US manufactured goods orders fell 4.8% in June 2025, nearly matching expectations, marking the largest decline since April 2020. Transportation equipment orders dropped 22.4%, civilian aircraft orders fell 51.8%, and ship and boat orders decreased 20.0%, reversing large gains from May.
- Trump threatens a substantial tariff hike on India for buying Russian oil and selling it for large profits.
- The Swiss government stated it isn't contemplating countermeasures against the US right now and is prepared to present a more appealing offer.
- A Japanese Labour Ministry panel suggested a 63 yen, or 6.0%, increase in the average minimum hourly wage for this fiscal year, the largest since at least 2002, compared to last year's 50-yen hike.
- Bessent said Washington is hopeful for a deal with China after trade talks in Stockholm. Meanwhile, China's leaders pledged economic support and to curb "disorderly competition." Beijing announced its fourth plenum in October, likely addressing the next five-year plan.
Equities:
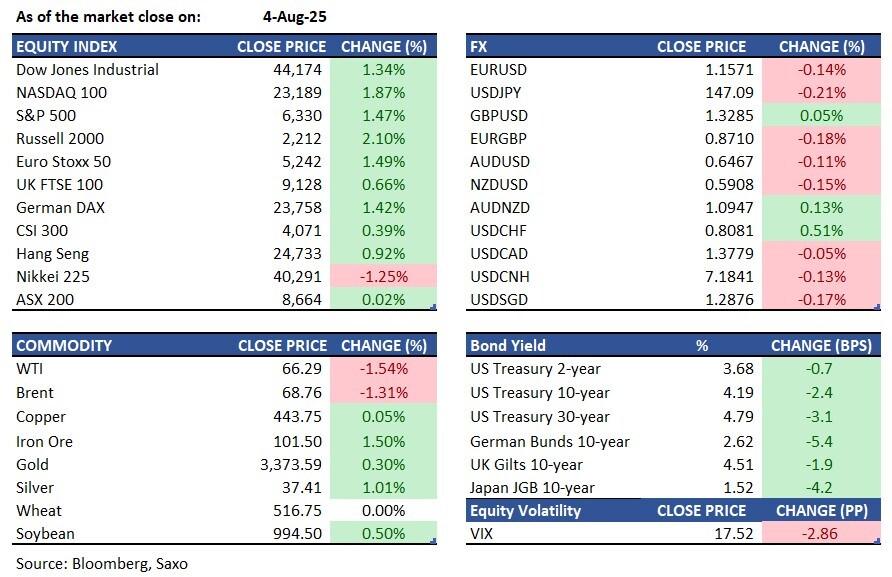
- US - U.S. stocks rebounded sharply on Monday, with the S&P 500 up 1.5%, breaking a four-day losing streak, the Dow climbing 585 points, and the Nasdaq rising 1.9%. Hopes for a Fed rate cut in September were revived by a weak July jobs report. President Trump dismissed the Bureau of Labor Statistics head and plans to appoint a successor, along with a new Fed Governor, this week. Despite updated tariffs of 10% to 41%, Switzerland and the EU showed willingness to negotiate. Tech giants led gains as 82% of S&P 500 companies reported better-than-expected earnings. Palantir rose 4.2% before the market closed, and gained a further 4.5% after reporting strong earnings and raised its full year revenue outlook. Berkshire Hathaway dropped 3% after its weekend earnings report.
- EU - Frankfurt’s DAX 40 rose nearly 1% to 23,660 points on Monday, trying to recover from last week’s sharp drop to a five-week low. STOXX 50 increased by 1.5%, while the STOXX 600 rose 0.8%, with Swiss stocks lagging due to new US tariffs. Gains were led by banks and insurers, bolstered by strong bonds and narrowing spreads. UniCredit, Santander, Intesa Sanpaolo, BBVA, and Allianz all rose between 3.2% and 4.5%, while industrial leaders Safran and Schneider Electric showed gains over 2%. British banks also climbed after favorable auto finance rulings, but Swiss stocks fell amid trade talks with the US.
- HK - Hong Kong shares gained 0.4%, to 24,607 on Monday morning, ending a four-day losing streak with broad gains led by property and tech sectors. Sentiment improved after China's leaders pledged economic support and tackled "disorderly competition." Optimism arose as U.S. Treasury Secretary Scott Bessent suggested progress in U.S.-China trade talks in Stockholm. Gains were cautious before upcoming July services PMI and China’s trade figures. Early movers included Zhaojin Mining (7.1%), Lenovo (2.6%), SMIC (2.9%), and Sun Hung Kai Properties (2.0%).
Earnings this week:
- Tuesday: Pfizer (PFE), Amgen (AMGN), AMD (AMD), Super Micro (SMCI)
- Wednesday: DoorDash (DASH), Instacart (CART), Uber (UBER), Lyft (LYFT), Walt Disney (DIS), Airbnb (ABNB), DraftKings (DKNG), Global Payments (GPN), Honda (7267), Novo Nordisk (NOVO), UOB (U11)
- Thursday: DBS (D05), Eli Lilly (LLY), Kenvue (KVUE), Warner Bros (WBD), Block (XYZ), US Foods (USFD), Semiconductor Manufacturing (SMIC), SoftBank (9984), Sony (6758), Toyota (7203)
- Friday: Wendy’s (WEN), McDonald's (MCD), Restaurant Brands (QSR)
FX:
- USD remained stable, with the Dollar Index below 99.00 amid mixed movements against G10 currencies. Markets await President Trump's announcements on new appointments for the heads of the Bureau of Labor Statistics and Fed Governor Kugler. Trade-wise, Trump plans to increase tariffs on India due to its oil purchases from Russia.
- CHF fell, alongside the EUR and NZD, influenced by Trump's tariff increase to 39% on Switzerland. In response, Switzerland aims to offer improved trade terms to the US. Currently, USDCHF and EURCHF trade close to their 50-day moving averages at 0.8072 and 0.9347, respectively.
- EUR was volatile below 1.1600 as the EU delayed trade countermeasures against the US, awaiting Trump’s actions on car tariffs. Germany’s Finance Minister commented on the EU's weak negotiation position.
- JPY strengthened against the dollar, USDJPY fell below 147 due to a softer US yield environment.
Economic Calendar – China Caixin Service PMI, France Industrial Production, Canada Balance of Trade, US Balance of Trade, US ISM Service PMI
Commodities:
- Oil stabilized after three days of decline as investors assessed risks to Russian supplies, with President Trump threatening higher tariffs on Indian exports for buying Russian oil. Brent traded below $69 a barrel, and WTI hovered near $66. India criticized the tariff move as unjustified.Gold maintained a slight gain as traders anticipated a Federal Reserve rate cut in September. Bullion remained steady near $3,375 an ounce in early Asian trading.
Fixed income:
- Treasury prices increased alongside stock gains. The rise in U.S. government debt was tempered by anticipation of a $125 billion supply of new three-, 10-, and 30-year bonds this week. The yield premium on 30-year notes over five-year counterparts surged 14 basis points on Friday, the highest since the 2023 banking crisis, reaching 106 basis points, and peaked at 108 basis points on Monday before settling around 105. Meanwhile, yields on UK and most euro-zone 10-year debts fell by two to five basis points.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.