
Access all our platforms from a single account.

Global Market Quick Take: Asia – May 08, 2025

Key points:
- Macro: Fed holds rates and Trump administration plans to revoke AI chip restrictions
- Equities: Alphabet fell 7.5% as Apple considers other AI search alternatives
- FX: Dollar index up; USD strength impacts GBP ahead of BoE decision
- Commodities: Gold and crude fell ahead of US-China tariff talk
- Fixed income: Treasuries saw modest gains, resulting in a flatter yield curve
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- The Fed held rates at 4.25%–4.50%, cautious about tariffs impacting inflation and growth. Policymakers noted rising uncertainty and risks of higher unemployment and inflation. Fed Chair Powell said there's no rush to change rates, and the Fed will monitor data, noting solid economic activity despite export fluctuations.
- The Trump administration plans to revoke Biden-era AI chip restrictions, potentially easing global semiconductor trade rules. The AI diffusion rule, aimed at limiting China's access to AI chip technology, will not be enforced.
- The Manheim Used Vehicle Value Index for the US rose by 2.7% month-on-month in April 2025, marking its first increase in three months and the largest since July 2024, following the early April tariff announcement.
- US mortgage applications increased by 11% in the week ending May 2nd, reversing three weeks of declines due to falling mortgage rates. New home purchase and refinancing applications both rose by 11%, with Veterans Affairs loans up 26%.
Equities:
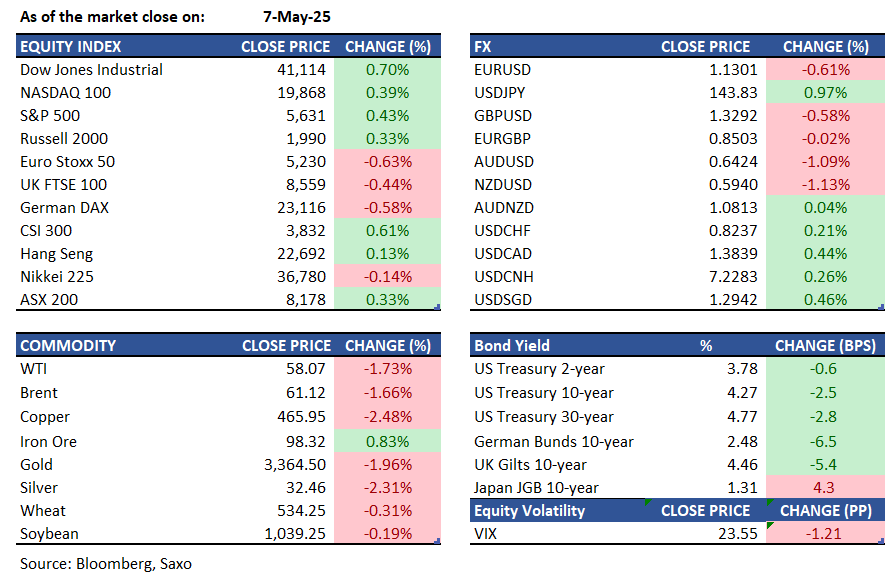
- US - US stocks climbed on Wednesday, as investors reacted to the Federal Reserve's decision to maintain interest rates. The S&P 500 gained 0.4%, Nasdaq 100 increased 0.3%, and the Dow advanced 297 points. The Fed kept its rate steady at 4.25%-4.5%, with Chair Jerome Powell adopting a cautious approach citing rising risks to inflation and unemployment. He noted high uncertainty, indicating no immediate rate cuts without clearer economic indicators. Expectations for US-China trade talks in Switzerland were subdued, as President Trump refused to relax tariffs ahead of negotiations. Nvidia rose 2.4% following speculations about easing chip trade rules, while Disney surged 10.9% on robust streaming growth, and Alphabet dropped 7.5% as Apple (-1.4%) considered AI search alternatives.
- EU - European shares fell on Wednesday, with the STOXX 50 and STOXX 600 both down 0.6% as investors remained cautious before the Federal Reserve's monetary policy announcement. The Fed is expected to keep the federal funds rate unchanged, but attention is on future policy signals. Traders also evaluated corporate earnings, while US-China trade talks in Geneva later this week did little to boost confidence. Novo Nordisk shares rose over 1% on stronger-than-expected net profit, despite cutting its full-year sales growth forecast, while BMW gained 2% despite a 23% drop in Q1 earnings. Fresenius and Siemens Healthineers fell as their results disappointed investors.
- HK - The Hang Seng rose 29 points, or 0.1%, to 22,692 on Wednesday, marking its fifth consecutive gain, driven by strong property and financial stocks. Investors considered the PBOC’s 50bps RRR cut as an effort to boost growth amid trade challenges. U.S. Treasury Secretary Bessent and Trade Representative Greer are set to meet China's economic officials in Switzerland this weekend for trade discussions, which led to initial gains but analysts noted the absence of significant fiscal stimulus from Beijing. Leading gainers included SITC Intl. Hlds. (3.2%), AIA Group (3.1%), J&T Global Express (2.5%), and Li Auto (2.4%).
- SG - DBS reported a Q1 net profit of S$2.9 billion, down 2% due to higher taxes from the global minimum tax. Profit before tax rose 1% to S$3.44 billion. The bank declared a dividend of S$0.75 per share, with total income up 4% to S$5.54 billion.
Earnings this week:
Thursday: Peloton, Shopify, ConocoPhillips, D-Wave, Hut 8, Coinbase, Cloudflare, DBS
Friday: Terawulf, 1stDibs, Enbridge, ANI Pharmaceuticals, Telos, OCBC
FX:
- Dollar index rose above 99.7 as the USD strengthened post-FOMC meeting. The Fed maintained rates at 4.25-4.50%, citing increased economic uncertainty and risks. Chair Powell stressed a cautious approach, avoiding pre-emptive actions.
- Post-FOMC, the EUR declined against the USD, testing support at the 1.13 level. Meanwhile, the EU plans to announce a provisional list of tariffs against the US on Thursday, contingent on trade talks.
- GBP fell below 1.33, influenced by the stronger USD and anticipation of a BoE rate cut on Thursday.
- JPY weakened against major currencies, though USDJPY gains were limited by resistance at the 144.00 level.
- CNH weakened against the USD after the PBoC cut several rates, including the 7-day reverse repo, RRR, and Standing Lending Facility, effective by May 15th. These moves aim to support consumption and tech sectors through relending programmes.
- Economic data: Germany Balance of Trade, BoE Interest Rate Decision, US Initial Jobless Claims, US Nonfarm Productivity
Commodities:
- Oil remained down ahead of US-China trade talks, with Trump noting the challenges in reaching a deal. Brent was near $61 after a 1.7% drop, and WTI was around $58. Trump won't lower tariffs before the talks in Switzerland this week.
- Gold stayed down as Powell said rate changes aren't urgent despite trade war. Sustained tariffs could lead to inflation and slower growth. Spot gold fell 1.7% to $3,373.04.
- Copper fell 0.8% to $9,465.50 per ton on the London Metal Exchange after China's expected rate cuts. Iron ore rose 0.8% to $98.30 per ton in Singapore, following a 2.4% increase earlier, despite oversupply concerns.
Fixed income:
- Treasuries gained modestly, with a flatter yield curve, returning to pre-Fed levels. Initial yield drops followed the FOMC statement highlighting economic uncertainty but later recovered. Swaps suggest three 25bp rate cuts by year-end. The Fed noted risks of tariff-induced inflation and unemployment, while Powell affirmed current policy remains appropriate until conditions change.
For a global look at markets – go to Inspiration.