
Access all our platforms from a single account.

Asia Market Quick Take – October 2, 2025

Asia Market Quick Take – October 2, 2025
Key points:
- Macro: US ADP Private payrolls fell 32,000
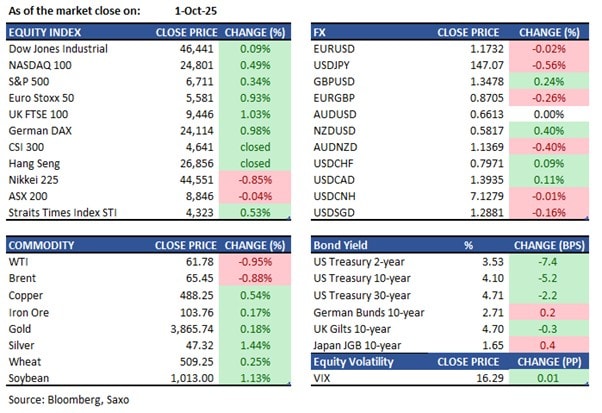
- Equities: S&P 500 and Nasdaq 100 rose a fourth day to record highs
- FX: Loonie lagged G10 peers, while yen extended its winning streak to four days
- Commodities: Gold hit records for five days; ETF inflows at a three-year high
- Fixed income: Treasuries rose; the curve steepened on growing Fed cut bets
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- US manufacturing shrank for a seventh straight month in September as orders softened. The ISM factory index rose 0.4 points to 49.1, still signalling contraction and remaining stuck in a narrow range this year.
- ADP said US private payrolls fell by 32,000 in September, after a revised 3,000 drop in August, missing all forecasts and partly reflecting data‑analysis issues. ADP periodically recalibrates to the Bureau of Labor Statistics series; the latest benchmark revision reduced September by 43,000 compared with pre‑benchmarked data.
- Fitch Ratings stated the US government shutdown likely won't impact its sovereign rating soon, while S&P Global Ratings sees shutdowns as having minor economic effects. Fitch expects the deficit to narrow to 6.8% of GDP in 2025, boosted by $300 billion in tariff revenues. S&P cautions prolonged shutdowns could reduce GDP growth by 0.1%-0.2% weekly due to secondary effects.
- The S&P Global Canada Manufacturing PMI fell to 47.7 in September 2025 from 48.3 in August, marking eight months of contraction due to US tariffs and Canada's retaliatory measures. New orders and output declined sharply, leading to reduced staffing levels, though job losses slowed. Input and selling price inflation eased. Firms face uncertainty from policy changes and tariffs, with confidence dipping from August's high.
- In the week ending September 26, 2025, US average rates for 30-year fixed mortgages with conforming balances rose to 6.46% from 6.34%, ending a four-week decline, per the Mortgage Bankers Association. Higher Treasury yields led to fewer refinance applications, according to MBA's Joel Kan. Jumbo loans increased to 6.54%, and FHA-backed mortgages rose to 6.24%.
- Euro area consumer inflation rose to 2.2% in September 2025, up from 2.0%, surpassing the ECB's 2.0% target. The rise was mainly due to a smaller energy cost decline of 0.4% compared to August's 2%. Services inflation increased to 3.2%, while food, alcohol, and tobacco inflation slowed to 3.0%. Non-energy goods inflation stayed at 0.8%. Core inflation remained stable at 2.3%.
Equities:
- US - The S&P 500 and Nasdaq 100 rose for a fourth consecutive session, setting new record highs. US equities rose as investors looked past the onset of a government shutdown, focusing on data that reinforced expectations for rate cuts and a second day of gains in drugmakers. The S&P 500 added 0.3%, led by health care as pharma shares extended gains on optimism that the Trump administration’s deal with Pfizer could spur more agreements. The Nasdaq 100 climbed 0.5% at the New York close. Lithium Americas jumped 23% after US Energy Secretary Chris Wright said the government had agreed to take a 5% stake. AES rose 17% amid reports BlackRock’s Global Infrastructure Partners is in advanced talks to acquire the company. Reddit fell as much as 11.5% on analyst reports of fewer OpenAI citations, while Tesla gained 3.3% ahead of expected quarterly sales.
- HK - BYD’s monthly sales fell for the first time in over 18 months, with shipments down 5.5% to 396,270 last month—the first year-on-year drop since February 2024 and, excluding Lunar New Year effects, the first since 2020. JPMorgan lifted Alibaba’s targets to HK$240 (+45%) and $245, citing stronger cloud and AI–e-commerce synergies, and kept its overweight rating.
Earnings this week:
- Thursday – Angiodynamics
- Friday – N/A
FX:
- The loonie underperformed G10 peers, with USDCAD up 0.2% to 1.3944. The Bank of Canada weighed holding rates in September amid trade uncertainty and stronger consumption but chose to cut on signs of a weakening economy and cooler core inflation, a deliberations summary showed Wednesday.
- USDJPY fell 0.5% to 147.10 as confidence among large manufacturers improved for a second straight quarter, strengthening the case for a BOJ rate rise as soon as this month.
- EURUSD was little changed at 1.1730, with euro-area inflation accelerating in September and cementing expectations the ECB will keep rates on hold for now.
- AUDUSD was steady at 0.6613 after a 0.5% gain, with the Aussie firm ahead of the RBA’s Financial Stability Review.
- NZDUSD was little changed at 0.5817 after a 0.4% rise, with focus on next week’s RBNZ meeting.
Commodities:
- Oil dipped after a choppy session amid speculation OPEC+ might accelerate output hikes, even as US crude inventories rise. West Texas Intermediate fell nearly 1% to settle near $62 a barrel, its third straight decline. Despite trader bets on a larger increase at this weekend’s meeting, the alliance says it has no such plans.
- Australian gold miners rose as gold steadies near $3,860 after a five-day record run, with the US shutdown and weak ADP data boosting Fed cut bets. September saw the biggest monthly ETF inflows in three years.
Fixed income:
- Treasuries advanced, led by the front end and belly, after ADP private payrolls missed estimates. The curve steepened as Fed rate‑cut bets grew, with 5s30s above 103bp and on track for its biggest one‑day widening since late August. Front‑end and belly yields were 6–7bp richer and 10s–30s by less than 5bp.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.