
Access all our platforms from a single account.

Asia Market Quick Take – November 28, 2025

Key points:
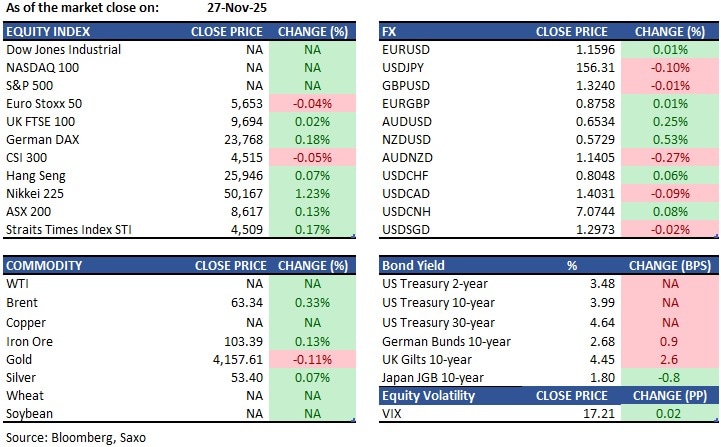
- Macro: UK’s budget less severe than expected
- Equities: Nikkei 225 rises more than 1% above 50,000
- FX: USD weakens across the board
- Commodities: Gold nears 2-week high
- Fixed income: Gilts rises after UK’s budget release
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Turbulence arose after the UK’s Office for Budget Responsibility released its report early, showing weaker growth and higher inflation forecasts. Investors were reassured by Chancellor Rachel Reeves expanding the fiscal buffer to £22 billion and bond issuance below expectations at £303.7 billion. Despite concerns over delayed fiscal tightening, traders found the package less severe than expected.
- Core consumer prices in Tokyo rose 2.8% year-on-year in November, slightly above expectations, fueling speculation of a December rate hike by the Bank of Japan amid persistent inflation and a weak yen. However, Governor Kazuo Ueda warns that global trade volatility may affect growth, leaving the timing uncertain.
- Germany's GfK Consumer Climate Indicator rose to -23.2 for December 2025 from -24.1. Buying willingness improved, and saving willingness decreased. Economic expectations and income expectations both declined. Consumer sentiment is stable compared to last year, suggesting strong Christmas sales, but no significant near-term recovery is expected.
- During the October 29–30 meeting, ECB policymakers opted to keep interest rates unchanged due to uncertainty, with some suggesting no further easing is needed. The policy was deemed appropriate, thanks to a strong economy and inflation near target. They highlighted the 2% deposit rate as robust enough for managing shocks. With conditions meeting projections, some thought rate cuts might be finished, while others recommended staying open to future changes.
- The Eurozone Economic Sentiment Indicator rose to 97.0 in November 2025 from 96.8 in October. Confidence improved in services, retail, and construction, while manufacturing declined and consumer confidence stayed unchanged. Inflation expectations rose, with consumer expectations up 1.2 points to 23.1, and manufacturers’ up 2.1 points to 9.9. ESI improved in Spain, Italy, and France, and remained stable in Germany and the Netherlands.
Equities:
- US – Closed
- Europe - Germany's DAX rose 0.2% to 23,778 on Thursday, its highest since November 14, marking four sessions of gains. This was driven by expectations of a December Fed rate cut and hopes for an end to the Ukraine war. Infineon Technologies and Siemens Energy led gains, rising 2.6% and 2%, respectively. Deutsche Börse rose 1.8% after JPMorgan upgraded the stock. Puma shares surged nearly 19% due to takeover speculation involving China's Anta Sports, with reports also mentioning Li Ning and Asics as potential bidders.
- Hong Kong – HSI rose 18 points to 25,946 on Thursday, marking its fourth straight gain, driven by financials. Sentiment improved with Beijing’s consumption boost plan and optimism in AI, but China's October industrial profits fell. U.S. Thanksgiving led to subdued trading. China Vanke delayed a bond payment, raising property concerns. Key movers included Pop Mart International (7.1%), Smoore Holdings (4.3%), Laopu Gold (4.1%), and Akeso Inc. (3.8%).
- Japan - Nikkei 225 rose 1.22% to 50,165 on Thursday, driven by Wall Street gains and expected Fed rate cuts. Japan plans to issue 11.5 trillion yen in bonds for economic support. Technology stocks like SoftBank Group led gains, rising 0.4% to 7.9%, with advances in financial, consumer, and resource sectors.
Earnings this week:
FX:
- The dollar index fell below 99.5 on Thursday, its lowest in nearly two weeks, amid expectations for Fed rate cuts. Markets now see an 85% chance of a December cut, up from 30% a week ago, and anticipate three more by 2026. This sentiment grew as Kevin Hassett emerged as a leading contender for Fed chair, aligning with Trump's preference for lower rates.
- NZDUSD rose to 0.5710, a near one-month high, after the Reserve Bank cut rates by 25bps to 2.25%, hinting at an end to its easing cycle. The guidance suggests a slight rate drop to 2.2% by mid-next year, reducing the likelihood of further cuts to about 20%.
- The JPY strengthened past 156 per dollar on Thursday amid potential intervention threats and a possible Bank of Japan rate hike next month. The yen also gained from dollar softness due to bets on further US Fed rate cuts.
- AUDUSD climbed toward 0.6530, a two-week high, after higher-than-expected inflation boosted hawkish RBA outlook. October's headline inflation rose to 3.8%, and trimmed mean inflation hit 3.3%, both above forecasts. A tight labor market previously led the RBA to hold rates steady.
Commodities:
- Brent crude hovered around $63 per barrel on Thursday after a 1% gain, amid uncertainties about supply due to Russia-Ukraine talks. A US envoy's Russia visit may affect sanctions. Traders await the OPEC+ meeting for market signals after a pause in planned output increases.
- Gold prices trades near $4160 per ounce on Thursday near a two-week high, with investors anticipating a Fed rate cut next month. Despite low jobless claims and strong durable goods orders, there is an 80% chance of a 25 bps cut at the Fed’s final meeting of the year.
- Copper futures hovered near a four-week high of $5.1 per pound after Chilean producer Codelco offered record-high prices to Chinese buyers, prioritizing US consumers. Codelco's offers included a $350 per ton premium over LME prices, emphasizing a bullish long-term copper outlook due to expected deeper supply deficits.
Fixed income:
- UK government's recent Budget announced a slightly increased gilt issuance target of £303.7 billion for the 2025/26 fiscal year, a figure lower than market expectations that led to a positive reaction from investors, causing gilt yields to fall. Finance Minister Rachel Reeves's fiscal consolidation plans increased the government's fiscal headroom, easing investor concerns and leading the Debt Management Office to strategically shift borrowing towards shorter and medium-dated gilts to manage costs.
- Japan’s 10-year bond yield rose above 1.8%, nearing 17-year highs, as expectations grow for a December rate hike by the Bank of Japan due to high inflation and a weak yen. BOJ officials and Governor Kazuo Ueda have highlighted inflationary pressures and the need for more data on wage growth.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.