
Access all our platforms from a single account.

Asia Market Quick Take – 16 June, 2026

Asia Market Quick Take – 16 June, 2026
Key points:
- Macro: BoJ and RBA rate decision this morning. US-Iran deal details unclear.
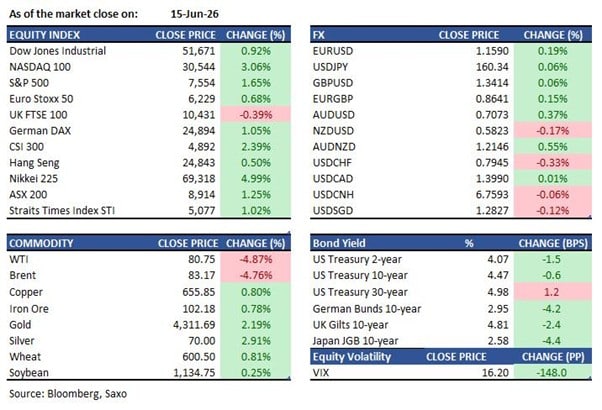
- Equities: Nasdaq 100 gains 3.1% with chip stocks leading; SpaceX gains a further 19%
- FX: US-Iran deal weakens dollar broadly; while yen weakness keeps USDJPY elevated
- Commodities: Silver remains near $70 and WTI holds above key level $80
- Fixed income: JGBs seen subdued ahead of BOJ decision, Uchida presser
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- A prospective US-Iran peace deal to reopen the Strait of Hormuz has eased fears of an energy-driven inflation shock and rate hikes. The interim accord is slated to be signed in Switzerland on Friday, though the unreleased text of the memorandum is keeping investors cautious.
- The NAHB Housing Market Index fell to 35 in June from 37, below expectations. Current sales dipped to 38, expectations stayed at 45, and buyer traffic remained weak at 25. More builders cut prices (35%) with 6% average reductions, and incentives edged up to 62%.
- US industrial production rose 0.1% in May, below the 0.3% forecast and after a revised 0.9% gain in April. Manufacturing was flat, mining rose 1.3%, and utilities output fell 0.4%. Capacity utilization edged up to 76.2%, still 3.2 points below its long-run average.
- The Empire State Manufacturing Index fell to 5.7 in June from 19.6, well below expectations, signaling a sharp slowdown. Still, new orders, shipments, and unfilled orders rose, employment and hours increased, price pressures stayed elevated, and firms remained broadly optimistic about the outlook.
Equities:
- US — US equities surged on Monday, with the S&P 500 rising 1.7% to 7,554.29 — its third consecutive gain and highest close since June 4. The Nasdaq 100 jumped 3.1% and the Dow Jones Industrial Average hit an all-time high. The Philadelphia Semiconductor Index (SOX) surged 5.4% to a record. Nvidia led S&P 500 gains, up 3.5%, while Western Digital was the top mover, rising 16.1%. SpaceX (SPCX) added 19% in its second day of trading, extending Friday's 19% debut surge. Fiserv slumped to a 10-year low following its CEO's sudden departure. VIX fell 9.1% to close at 17.68.
- EU — European stocks closed modestly higher on Monday, with the Stoxx 600 rising 0.2% to 634.44 and briefly touching a record intraday high before fading. The DAX outperformed, gaining 1.1% to 24,894.01, with Deutsche Bank rising 4.3%. The FTSE 100 underperformed, falling 0.4% to 10,430.62, dragged by Shell (-4.4%) and BAE Systems (-4.7%) as energy and defence stocks sold off on the Iran deal. Santander was the top contributor to Stoxx 600 gains, rising 3.9%. Cyclicals — autos, construction, and travel — led the advance while defensives lagged.
- Asia — Asian markets surged on Monday on the US-Iran deal news. Japan's Nikkei 225 rose 5% to a record high, led by a broad rally in tech and electronics. South Korea's Kospi soared 5.2% to 8,545.98, led by SK Hynix (+6.4%), with the electronics sector driving gains across 16 of 18 sectors. The Straits Times Index (STI) rose 1.0% to 5,077.29, with Jardine Matheson the top gainer at +4.4%. Hong Kong and Shanghai also closed in the green. This morning (June 16), the Kospi has extended gains, rising a further 1.8% to 8,696.55 in early trade. The MSCI Asia Pacific Index climbed as much as 3.2% on Monday, on track for its biggest two-day rally since March 2022.
Events this week:
- Tuesday: BOJ policy decision, RBA rate decision
- Wednesday: FOMC rate decision
- Friday: US Juneteenth holiday. China, Hong Kong and Taiwan observe Dragon Boat Festival. Markets closed.
FX:
- USD weakened broadly as the interim US‑Iran deal to reopen the Strait of Hormuz boosted risk sentiment and pushed oil lower, with the Bloomberg Dollar Spot Index falling 0.3% and DXY stalling at key technical resistance. The dollar slipped against majors such as the EUR, AUD, and NZD, but remained firm against the JPY.
- USDJPY only dipped about 0.1% before rebounding above 160, reflecting persistent structural yen weakness and heavy speculative short-yen positioning ahead of the BOJ meeting.
- EUR and commodity currencies benefited, as EURUSD rose about 0.3% to 1.1597, AUDUSD gained 0.4% to 0.7075, and NZDUSD advanced 0.3% to 0.5850.
Commodities:
- Brent crude fell sharply on Monday, dropping around 4%–5% to below $84 a barrel — a three-month low — following the US-Iran interim deal to reopen the Strait of Hormuz. WTI settled below $81. Oil prices remain elevated relative to pre-war levels, however, as shipowners and traders await further clarity before resuming transits. The US Strategic Petroleum Reserve has fallen to its lowest level since 1983 at roughly 340 million barrels, as the Trump administration releases reserves to tame prices.
- Gold jumped as much as 3.6% on Monday to nearly $4,370 an ounce, with bullion holding near $4,315 in early Tuesday trade. The rally was driven by the Iran deal easing inflation fears and tempering rate-hike expectations. Silver also surged, rising as much as 4.9% on the session.
- The LME copper cash-to-three-month spread fell by $22.67 to -$75.34 per ton on June 15, reflecting shifting inventory dynamics. The LME approved Detroit as a new copper delivery point, as US tariff expectations continue to reshape global copper trade flows and inventories.
Fixed income:
- US Treasuries advanced as the Iran peace deal led traders to dial back Fed rate-hike expectations. Yields fell across the curve, led by the front-end: the 1-year yield fell ~1.6bp to 3.842%, the 10-year fell ~1.5bp to 4.467%, and the 30-year was little changed near 4.969%. The curve steepened modestly, with the 5s30s spread widening to 78.6bp from 76.4bp.
- The June 16–17 FOMC meeting — Kevin Warsh's debut as chair — is the key event for rates this week. BNP Paribas described it as "a pivotal moment for the US rates market," with the dot plot expected to signal whether the Fed leans toward hikes later in 2026. The 10-year real yield stands at 2.14%, having risen 22bp year-to-date.
- Japanese government bonds are expected to trade cautiously ahead of the BOJ decision today. JPMorgan's private banking arm warned that any dovish interpretation of BOJ communication could reignite yen and JGB shorts, making market stabilisation increasingly costly. The BOJ is widely expected to raise its benchmark rate.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.