
Access all our platforms from a single account.

Asia Market Quick Take – 1 April, 2026

Key points:
- Macro: US plans to leave Iran in 2-3 weeks
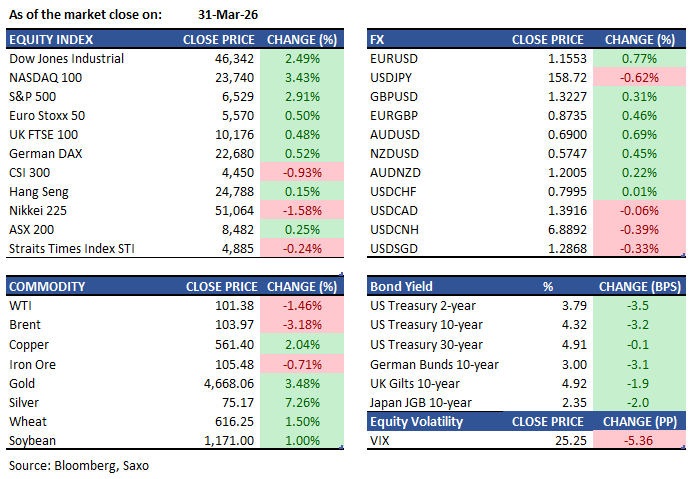
- Equities: Nasdaq 100 gains 3.8%, S&P 500 rallies 2.9% on Iran comments to end war
- FX: Dollar drops as Iran de-escalation; USDJPY below 159
- Commodities: Gold extended a three‑day advance pushing above $4,700.
- Fixed income: US Treasuries rally, paring their biggest monthly loss in over a year
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- President Trump said the US could leave Iran within two to three weeks and indicated a deal with Tehran may be close, raising hopes the war that has jolted global markets may be nearing a conclusion.
- Iran's official news agency said the country's president was willing to end the conflict but wants guarantees against further attacks. Trump also urged Straits users to secure it themselves.
- US job openings fell by 358,000 to 6.88 million in February 2026, below expectations, with declines across all regions and in accommodation, food services, and mining. Hires slipped to 4.8 million, while separations held at 5.0 million, with quits at 3.0 million and layoffs and discharges at 1.7 million.
- US job quits fell to 2.97 million in February 2026, the lowest since August 2020, down from 3.13 million in January and 3.15 million a year earlier. The quits rate eased to 1.9%, with declines across all regions and most major sectors.
- Japan’s large manufacturers grew more confident for a fourth straight quarter, with the Tankan index rising to 17 from 16, beating forecasts and supporting the BOJ’s ongoing rate-hike stance.
- South Korea's exports continued to surge in March with shipments adjusted for working-day differences soaring 41.9% from a year earlier, driven by robust semiconductor demand.
Equities:
- US: US equity indexes surged on Tuesday with the Dow Jones Industrial Average jumping more than 1,125 points, the S&P 500 up 2.9% to 6,528.52, and the Nasdaq Composite catapulting almost 800 points or 3.8% to 21,590.63 amid optimism that the Iran war is about to end. Communication services, technology, and consumer discretionary led the gains. S&P 500 futures were up 0.3% as of 8:04pm Tuesday in New York, while Nasdaq 100 futures gained 0.5%. Nike shares sank 9% after hours after the company forecast more falling sales and conceded its turnaround efforts were taking longer than expected.
- EU: European stock index futures climbed sharply with contracts on the Euro Stoxx 50 up about 1.9% as of 1:18am in London on hopes for an end to the Iran war. The FTSE 100 rose for the second day on Tuesday, climbing 0.5% or 48.49 points to 10,176.45 in London, reaching the highest closing level since March 18, with Rolls-Royce contributing the most to the index gain.
- Asia: Asian stocks jumped at the open, tracking a Wall Street rally, with equities in Japan, South Korea and Australia rising and sending the broader MSCI Asia Pacific Index up 1.6%. Japan's Nikkei climbed more than 3% to 52,792.66 while the Topix rose 3.1% to 3,607.25. South Korea's Kospi surged nearly 5% at the open to 5,330.04, snapping a four-day loss, with the Korea Exchange briefly halting program trading after Kospi 200 futures jumped more than 5%, triggering a sidecar. Samsung Electronics and SK Hynix jumped as much as 7.1% and 9.5% respectively. Recruit Holdings shares rose 7.6% after announcing a buyback plan. KDDI shares fell 3.3% after cutting fiscal year earnings forecasts.
Earnings this week:
- Wednesday: SAIC Motor
FX:
- USD softened on Tuesday, trimming its strong monthly gain as reports of possible de‑escalation in the Iran conflict reduced safe‑haven demand The Bloomberg Dollar Spot Index fell 0.6% on the day but still ended March up about 2.4%, its best month since July.
- Intervention worries persisted in Japan as USDJPY slipped 0.6% to 158.69 but remained up 1.7% on the month, with TD Securities flagging higher intervention risk only on sustained moves toward 162–164.
- USDCAD edged lower as Canadian GDP showed modest early‑year growth, and EURUSD rebounded 0.9% to 1.1563 despite a 2.1% monthly drop amid highly volatile European rates.
- AUDUSD climbed 0.7% to 0.6900, extending a five‑quarter winning streak, with the RBA highlighting uncertainty over its policy path.
Commodities:
- Oil steadied with Brent trading below $105 a barrel after losing 3.2% on Tuesday, while WTI was near $102, as President Trump signaled the potential end to the Iran war that has roiled markets, even after more troops arrived in the region and Tehran said no peace talks were taking place.
- Gold extended a three‑day advance, with bullion above $4,700 an ounce after a 3.5% jump, as President Donald Trump said the US could end the Iran war within two to three weeks and had largely met its military goals, while Iran’s President Masoud Pezeshkian signalled readiness to end the war if its demands are met.
Fixed income:
- Treasuries extended Monday’s belly‑led rally as oil fell on hopes of Iran de‑escalation and stocks rose with traders rebuilding Fed rate‑cut premia for this year and 2027, though 30‑year bonds erased gains. Month‑end rebalance and the market broadly trimmed its biggest monthly loss in over a year. The newest 10-year JGB yield fell 3 basis points to 2.325% after the Tankan survey beat forecasts across the board with a notable jump for the large manufacturing outlook, opening the door for a BOJ hike this month.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.