
Access all our platforms from a single account.

Asia Market Quick Take – October 9, 2025

Key points:
- Macro: Fed highlights employment risks, cautious on inflation; signals more cuts ahead
- Equities: S&P 500 & Nasdaq hit record highs; AMD gains 11.3%, up 40% this week
- FX: Dollar index up; RBNZ's rate cut pressures NZD
- Commodities: Gold falls from record above $4,000
- Fixed income: US Treasuries reduced gains post-10-year auction
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- The Federal Reserve expressed concern over employment risks while remaining cautious on inflation, per the latest FOMC minutes. Most officials supported moving to a neutral rate, yet inflation pressures remained a concern. Many anticipate additional easing this year, with half predicting two more cuts by 2025. Recently, the Fed cut rates by 25bps to 4.00%-4.25%, the first since December.
- Germany's industrial production fell by 4.3% in August, the largest drop since March 2022, driven by declines in automotive (-18.5%) and other key sectors. This exceeded expectations of a 1% decline. On an annual basis, output decreased 3.9%, reversing a 1.5% gain from the previous year.
- New Zealand's budget deficit for the year ending June 30 was NZ$9.31 billion, below the NZ$10.18 billion forecast. This marked an increase from NZ$8.77 billion the previous year. Net debt was 41.8% of GDP, better than the anticipated 42.7%. Finance Minister Nicola Willis highlighted fiscal improvements, with core Crown expenses down to 32.5% of GDP.
- Hamas declared a deal to end the Gaza conflict after indirect talks with Israel in Egypt, as reported on Oct. 8 by AFP. The agreement includes ceasefire terms, withdrawal of Israeli forces, humanitarian aid access, and prisoner exchanges. Hamas urged US President Trump to ensure Israel adheres to the deal without delays or evasion.
Equities:
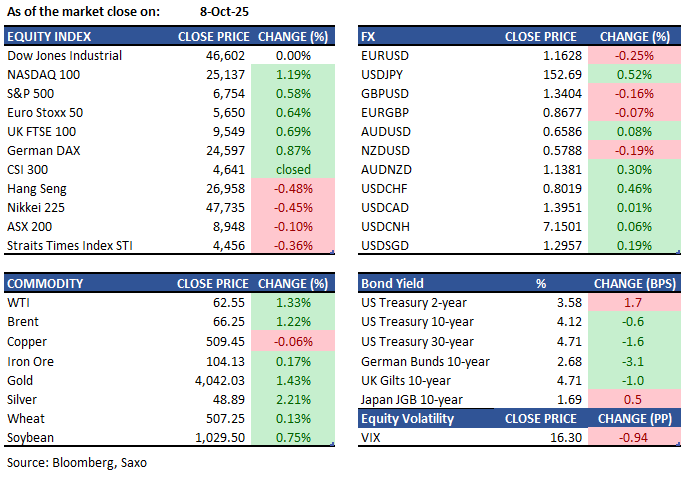
- US - US stocks closed at a record on Wednesday, powered by AI‑linked gains as traders digested September Fed minutes signalling openness to further rate cuts this year. The S&P 500 rose 0.6%, marking its 33rd all‑time high of 2025, while the Nasdaq 100 climbed 1.2%. Oracle added 1.5% after Tuesday’s sharp drop, a basket tracking the “Magnificent Seven” gained 0.8%, and Nvidia rose 2.2% as chief executive Jensen Huang told CNBC Blackwell chip demand is “really, really” high. Cisco stepped up competition with Broadcom in connecting AI data centres, and small caps added 1%. Semiconductor names including ASML fell after a US House committee said the industry is boosting China’s chip sector and supporting its military, raising the risk of further export controls. AMD shares log their best three‑day gain in nine years, up 43%; options trading highest since Aug 2021.
- CH - China’s markets reopen Thursday after Golden Week, with investors weighing AI enthusiasm against soft consumer spending. Holiday data point to caution, with cheaper road trips replacing flights and box office takings missing expectations. Global tech hit fresh highs on AI while China was shut, buoyed by firms touting OpenAI ties. A gauge of large mainland stocks listed in Hong Kong slipped 0.3% during the closure and the offshore yuan edged lower. Focus now turns to policy signals at the Communist Party’s 20–23 Oct meeting outlining the 15th five‑year plan, and a potential Trump–Xi meeting at next month’s APEC summit in South Korea if tariff talks resume.
- HK - Hang Seng dropped 0.5% to 26,829, its third straight decline, as broad sector weakness persisted. Tech stocks fell 0.6%, with Alibaba down 1.6% and Baidu hit by fears of expanded US export curbs. Financials and consumer stocks also fell amid China's slow recovery. Gold miners like Shandong Gold surged as bullion prices set records. The World Bank's upgraded China growth forecast to 4.8% from 4.0% offered slight relief.
- EU - DAX hit a record 24,597, gaining 0.9% on Wednesday, driven by EU's trade measures to restrict steel imports. Despite weak German industrial output and French political uncertainty, sectors like industrials and banks pushed higher, with Thyssenkrupp surging 5%. BMW fell over 8% on a profit warning and steel cost concerns. Traders awaited Fed minutes amid the US government shutdown.
Earnings this week:
Asia
- Thursday: TCS, Fast Retailing, Seven & I, Sugi Holdings, Aeon Financial Service
- Friday: Zhaojin Mining, Ryohin Keikaku, Tsuruha Holdings, Rorze, Bic Camera
Outside Asia
- Thursday: PepsiCo, Levi Strauss, Aritzia, Applied Digital, Suedzucker
- Friday: Tryg, Atrium Ljungberg, Transcorp Power, Gerresheimer
FX:
- USD strengthened across peers despite scant news, buoyed by FOMC Minutes revealing Governor Miran as the sole dissenter at the September meeting, with some members advocating for keeping rates unchanged amidst possibly non-restrictive financial conditions. The DXY climbed to 98.9.
- AUD and CAD traded largely unchanged against the USD, while CHF and JPY lacked haven appeal amid the US government shutdown.
- EURUSD saw modest relief, lifting to 1.1620 as France neared a new PM appointment. German data disappointed with a 4.3% drop in industrial orders, partly due to holiday closures.
- NZDUSD fell to 0.5780 following RBNZ's 50bps rate cut, leaving further easing possible to achieve the 2% inflation target.
Commodities:
- Oil fell for the first time in five sessions amid easing Middle East tensions and higher US inventories; WTI slipped below $62, while Brent held above $66. Trump said Israel and Hamas agreed terms to release all Gaza hostages.
- Gold dipped after a record above $4,000, falling up to 0.7% to around $4,015 in early Asia, as overbought signals and a four‑day surge prompted profit‑taking.
- Silver surged over 3% on Wednesday, nearing an all-time high of $50.
Fixed income:
- US Treasuries pared gains into and after the $39bn 10‑year soft reopening, with a slight tail despite solid demand. Earlier, a mild bull‑flattening mirrored Europe, and the FOMC minutes drew little reaction. On Thursday, the US Treasury is expected to unveil a second round of increases to weekly benchmark bill sizes, continuing this month’s expansion of short‑dated issuance.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.