
Access all our platforms from a single account.

Asia Market Quick Take – October 8, 2025

Asia Market Quick Take – October 8, 2025
Key points:
- Macro: US consumer inflation expectations rise 3.4%
- Equities: US stocks fall; Tesla slipped 4.4% on its low-cost Model Y launch
- FX: Carry trades support USDJPY to break 152 and EURJPY hit fresh record 177
- Commodities: Gold extends gains, setting a fresh record near $4,000
- Fixed income: Treasuries rose, extending modest gains after a strong 3‑year auction
------------------------------------------------------------------
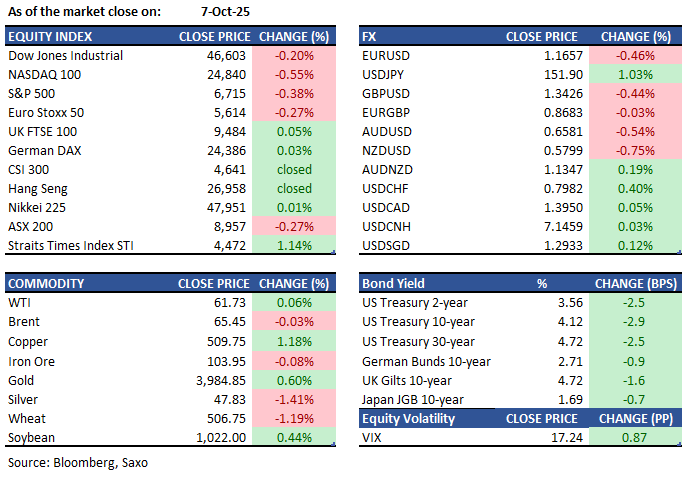
Disclaimer: Past performance does not indicate future performance.
Macro:
- US consumer inflation expectations rose to 3.4%, the highest in five months, up from 3.2% in August. Consumers anticipate higher prices for food, gas, medical care, and rent, while college cost expectations dropped. Home price growth expectations stayed steady at 3% for the fourth month. Five-year inflation expectations rose to 3% from 2.9%, and three-year stayed at 3%. Earnings growth expectations fell to 2.4%, while unemployment expectations rose to 41.1%. Household income growth expectations remained at 2.9%.
- The US RealClearMarkets/TIPP Economic Optimism Index fell to 48.3 in October 2025, below expectations and the neutral 50 mark, indicating continued consumer pessimism. The Six-Month Economic Outlook dropped to 42.8, while Confidence in Federal Economic Policies fell to 46.4. Conversely, the Personal Financial Outlook improved, rising to 55.6 from 53.4 in September.
- The US Manheim Used Vehicle Value Index fell 0.2% in September 2025, marking the third consecutive month of subdued prices. Luxury, pickups, SUVs, and compact cars saw declines, while mid-sized sedans increased 0.2%. EV values rose 0.8%; non-EVs fell 1%. Annually, used car prices grew 2% led by luxury and EV gains. Despite declines, wholesale values remain elevated, noted Cox Automotive's Jeremy Robb.
- Canada’s trade deficit widened to C$6.3 billion in August 2025 from C$3.8 billion in July, exceeding expectations of C$5.6 billion, marking the second-widest deficit on record. Exports dropped 3% to $60.6 billion, affected by US tariffs, with significant falls in minerals and lumber. Imports rose 0.9% to C$66.9 billion, driven by a surge in metal purchases, despite energy import declines. Canada’s surplus with the US fell from C$7.4 billion in July to C$6.4 billion.
- US Logistics Manager’s Index dropped to 57.4, its lowest in six months, down from 59.3. This decline indicated slower logistics sector growth amid economic uncertainty. Transportation utilization decreased to 50, marking the weakest September on record. Transportation prices (54.2) slipped below capacity (55.1). Inventory levels slowed (55.2), but costs stayed high (75.5). Warehousing utilization (65.3) and capacity (51.6) increased, while warehousing prices fell sharply to 66.
Equities:
- US - US stocks fell from record highs Tuesday, with the S&P 500 down 0.4%, Nasdaq dropping 0.8%, and Dow losing 99 points amid the ongoing government shutdown and AI growth optimism. Oracle shares tumbled 2.5% after weak cloud margins, Tesla slipped 4.4% on its low-cost Model Y launch, and Ford fell 7.6% due to a supplier fire. Economically sensitive sectors lagged, while tech stocks were mixed; AMD rose 3.8% on an OpenAI deal, and IBM advanced on an AI partnership. With new economic data stalled, investors focused on secondary indicators and Fed hints at potential rate cuts. Elon Musk's AI startup xAI is expanding its funding round to $20 billion. Bloomberg reports Nvidia will invest up to $2 billion, with the financing linked to Nvidia GPUs for xAI's Colossus 2 data center.
- EU - European stocks fell slightly on Tuesday, continuing losses as political turmoil in France raised concerns about the Eurozone's fiscal stability. Following Prime Minister Lecornu's resignation, President Macron gave him 48 hours to negotiate with political parties resisting budget cuts. Major banks and insurers, including BNP Paribas, AXA, ING, and Santander, saw declines of 1% to 3%. In contrast, luxury brands rebounded, with LVMH rising 3.4% and Kering jumping 6% after Morgan Stanley upgraded their ratings to "overweight." Shell saw a 1.4% increase following an announcement that its Q3 gas trading would outperform Q2 levels.
- SG – The Straits Times Index (STI) rose by 1.1% to close at 4,472.26. Yangzijiang Shipbuilding led gains, up 4.1% to $3.52, and was the most actively traded stock. DBS increased by 3% to a new high of $54.80. Other banks gained as well: UOB rose 0.3% to $35.49, and OCBC climbed 0.4% to $16.91. Mapletree Logistics Trust was the biggest decliner, down 0.8% to $1.28.
Earnings this week:
Asia
- Wednesday: ABC-Mart, Welcia
- Thursday: TCS, Fast Retailing, Seven & I, Sugi Holdings, Aeon Financial Service
- Friday: Zhaojin Mining, Ryohin Keikaku, Tsuruha Holdings, Rorze, Bic Camera
Outside Asia
- Wednesday: AZZ
- Thursday: PepsiCo, Levi Strauss, Aritzia, Applied Digital, Suedzucker
- Friday: Tryg, Atrium Ljungberg, Transcorp Power, Gerresheimer
FX:
- The yen’s post‑LDP vote slide deepened as carry trades returned, with USDJPY up 1.1% to 151.93 (strongest since 19 Feb) and now above 152 handle. Hedge funds added longs above 150.70 and there was OTC demand for short‑dated topside.
- EURJPY hit a record 177.13, while EURUSD fell 0.4% to 1.1659 near its 50‑day average (1.1683) and one‑week risk reversals turned bearish amid French political risk.
- The kiwi led G‑10 losses, with NZDUSD down 0.8% to 0.5798 after weaker business confidence; the RBNZ is expected to cut on Wednesday, though the size is in debate.
- USDCAD was little changed at 1.3949 as Canada posted its second‑largest trade deficit on record on weaker gold exports and surging imports.
Commodities:
- Oil edged higher on mixed US inventory data and a supply outlook shaped by OPEC+ output hikes and rising US production. WTI topped $62, Brent hovered near $65. API reported a 1.8m bbl Cushing draw and product declines, but nationwide crude stocks rose.
- Gold set a fresh record near $4,000 as the US shutdown and a tech wobble lifted haven demand; spot peaked at $3,992.27 after a 0.6% rise, while December futures ticked higher after topping $4,000 Tuesday. Silver edged up, platinum was flat and palladium rose.
Fixed income:
- Treasuries advanced, extending modest gains on a strong 3‑year note auction, with intermediates leading as attention turns to Wednesday’s 10‑year sale. Futures volumes rose after filling Monday’s gap lower, and yields were at session lows into the bidding deadline. JGB futures fell three ticks to 135.87 on Tuesday, while the 10‑year benchmark yield eased to 1.675%.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.