
Access all our platforms from a single account.

Asia Market Quick Take – November 25, 2025

Asia Market Quick Take – November 25, 2025
Key points:
- Macro: Fed Governor Waller backs Dec rate cut
- Equities: Alphabet gains 6.3%; Broadcom up 11% as tech recovers.
- FX: USD Index above 100; EUR gains, JPY weakens as USDJPY trades around 156.90
- Commodities: Gold rallies 2%, breaks above $4,100
- Fixed income: Money markets price ~90% odds of a Fed rate cut
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Federal Reserve Governor Christopher Waller backs a December interest‑rate cut amid labour‑market concerns and expects a meeting‑by‑meeting approach from January, while futures put the odds at about 70% for the 9–10 December meeting.
- San Francisco Fed President Mary Daly backs cutting rates next month amid a deteriorating labour market she sees as vulnerable to a non‑linear shift, views an inflation breakout as a lesser risk, and says the Fed can return inflation to 2% without higher unemployment—failure to do so would be a policy failure.
- Germany's Ifo Business Climate Index fell to 88.1 in November, missing forecasts and signaling limited recovery prospects. Expectations declined, manufacturers and traders grew more pessimistic, and construction confidence dropped. Meanwhile, service sector sentiment improved, boosted by strong tourism.
- Trump and China’s Xi held their first talks since last month’s tariff truce; Trump called it “very good,” citing trade, farm purchases and fentanyl, while rare‑earth sales talks aim for “general licences” by month’s end.
Equities:
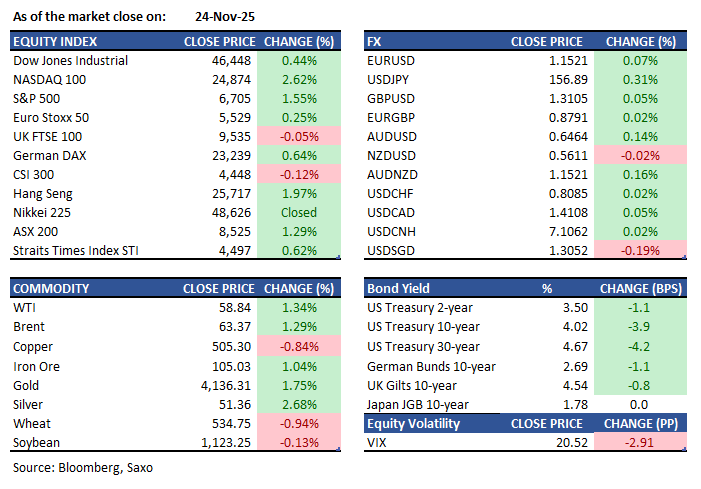
- US - US stocks rallied Monday as Fed officials signaled a possible December rate cut. The S&P 500 rose 1.6%, Nasdaq jumped 2.7%, and Dow added 240 points. Futures now price a 79% chance of a 25bp cut at the Dec 9–10 meeting. Tech led gains: Broadcom surged 11.1% on revived AI infrastructure trade with Alphabet, Alphabet climbed 6.3% after Gemini 3 news pushed its value past Microsoft and a further 2.5% in the post market after it was reported that Meta is spending billions to integrate Google’s TPU, and Tesla rose 6.8% on progress with next-gen AI chips. Traders await delayed retail sales and PPI data, which could influence the Fed’s final call.
- EU - European stocks closed slightly higher Monday, trimming last week’s losses on dovish Fed signals. The STOXX 50 rose 0.4% to 5,540 and STOXX 600 gained 0.3% to 564. Tech rebounded strongly, with ASML up 3% and Infineon up 3.5%, while Siemens and Schneider also advanced. Banks were mixed: Nordea and BBVA rose 1.5%, but UniCredit and Intesa slipped as Italian banks detached from dividends. Novo Nordisk plunged 6.5% after its pill version of Ozempic failed to slow Alzheimer’s progression in a major trial.
- HK - Hang Seng jumped 496 points (1.97%) to 25,716 on Monday, snapping a six-day losing streak as Fed rate-cut bets lifted sentiment. Tech led gains, with the index up 2.7% after reports the U.S. may allow Nvidia to sell H200 chips to China. Alibaba surged 5.3% on strong Qwen chatbot downloads, while Leapmotor (+6%) and Innovent (+5%) rallied ahead of their inclusion in Hang Seng indexes. JD.com added nearly 2% amid IPO plans for its supply-chain tech unit. Optimism also grew ahead of Beijing’s policy signals, though caution lingered before China’s industrial profits and Hong Kong trade data.
Earnings this week:
- Tuesday
Alibaba, Chow Tai Fook Jewellery, Nio, Abercrombie & Fitch, Tongcheng Travel, Robosense Technology, Analog Devices, Dell, Workday, Compass Group, Zscaler, Best Buy, HP, Kohl’s
- Wednesday
Li Auto, Alibaba Health Information, Envision Greenwise, Rockwool, CD Projekt, Aroundtown, Tiger Brands, Strauss Group, Deere
- Thursday
Bosideng International, Sime Darby, Luk Fook Holdings, Ryman Healthcare, Oberbank, Asseco Poland, Remy Cointreau, CPI Europe, Grenergy Renovables
- Friday
Meituan. Chagee, China Gas, China Water Affairs, CPI Property, Dottikon ES, 4iG, Kernel Holding, Electrica
FX:
- USD Index, despite starting the week lower, remains above 100, influenced by dovish expectations for a December rate cut from Fed officials Waller and Daly, who cited labor market concerns.
- EUR strengthened to approximately 1.1530 against the USD, driven by optimism over a simplified 19-point U.S.-proposed Ukraine peace plan, despite Kremlin rejection of EU alternatives.
- JPY weakened, with USDJPY trading around 156.90 as increased risk appetite and market optimism contributed to currency pressure.
- AUD hovers near $0.645 as the Reserve Bank reviews policy, considering post-pandemic pricing and housing strength. Strong PMI data reduces chances of rate cuts. Focus shifts to CPI figures, with inflation expected at 3.6%.
- GBP is trading higher at near 1.3110 against the USD. UK Chancellor Reeves' upcoming budget announcement is expected to focus on reducing living costs and NHS waiting times.
- The market awaits updates from Germany and scheduled releases of U.S. PPI and Retail Sales data, potentially influencing currency movements further.
Commodities:
- Oil steadied as risk-on sentiment offset Ukraine peace-talk progress that could boost supply, with WTI near $59 after Monday’s 1% rise and Brent above $63. Equities and most commodities advanced on expectations of further Fed rate cuts, while Trump and Xi held their first talks since last month’s tariff truce.
- Gold steadied around $4,140 after Monday’s near 2% surge on expectations of a December US rate cut signalled by Fed Governor Christopher Waller amid a soft labour market, rising 0.1% to $4,140.66, while silver edged lower and platinum and palladium were steady.
Fixed income:
- Long-end Treasuries outperformed, flattening the curve and holding after a solid 2‑year auction that stopped at the when‑issued yield, with upcoming 5‑ and 7‑year sales reinforcing the move as a December rate‑cut premium built on dovish remarks from Mary Daly and money markets priced about a 90% chance. Japan’s rates market reopens after a holiday, with focus on the 40‑year JGB auction on 26 Nov.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.