
Access all our platforms from a single account.

Asia Market Quick Take – November 19, 2025

Key points:
- Macro: The US plans to approve AI chip sales to Saudi firm Humain
- Equities: Microsoft and Nvidia will jointly invest up to $15 billion in Anthropic
- FX: JPY weakens, affected by domestic issues; trades above 155.50
- Commodities: Gold rebounds, holding $4,000 level
- Fixed income: Global holdings of US Treasuries fell; Japan's rose
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- The Labor Department's website revealed 232,000 new unemployment claims for the week ending October 18. Due to a technical issue, this data was released early. Remaining jobless claims data from the shutdown will be posted by Thursday's end.
- The US will approve advanced AI chip sales to Saudi firm Humain as part of a broader AI deal with Riyadh. This move allows favorable US review of AI chip exports to Saudi Arabia, requiring US permission since 2023. The agreement involves specific chip tiers, benefiting companies like Nvidia and AMD seeking to enter Middle Eastern markets.
- ADP Research reports companies shed 2,500 jobs weekly in the four weeks ending November 1. This data bridges gaps from delayed official employment reports due to the government shutdown. October's economic data release is still uncertain despite restored funding.
Equities:
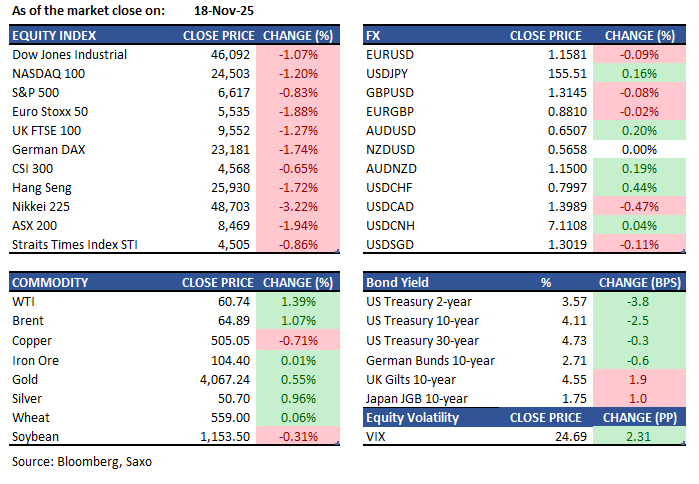
- US - US stocks fell sharply Tuesday, with the S&P 500 down 0.8%, Dow off 1%, and Nasdaq losing 1.1% as investors unwound AI trades ahead of Nvidia’s earnings and questioned tech valuations after heavy debt issuance. Mega caps led declines: Nvidia (-2.8%), Microsoft (-2.7%), Amazon (-4.4%), Tesla (-1.9%). Home Depot dropped 6% after cutting its profit outlook. Nvidia and Microsoft committed to invest $15b in Anthropic, while Anthropic commits to buying $30b worth of computing capacity from Microsoft’s Azure cloud service. Bitcoin briefly dipped below 90K, adding to risk aversion. Markets braced for delayed macro data and stronger labour signals that could limit Fed easing. PDD also reported earnings that beat estimates while revenue growth moderated to 9%. The stock fell 7% in US ADR trading.
- EU - European stocks fell to one-month lows Tuesday, extending recent losses as global equity sentiment weakened amid concerns over tech valuations and persistent high rates. The STOXX 50 dropped 1.9% to 5,540 and STOXX 600 slid 1.8% to 561. Banks led declines, with Santander, Intesa Sanpaolo, and ING down over 3%. Consumer cyclicals and tech also struggled, with Adidas, Ferrari, Adyen, and Infineon losing more than 2%. Tech shares faced added scrutiny ahead of Nvidia’s earnings, expected to gauge AI demand. In contrast, Roche surged 6.8% after positive late-stage trial results for its breast cancer drug Giredestrant.
- HK - Hang Seng dropped 1.7% on Tuesday to 25,930, its sharpest fall since mid-October and a two-week low. Tech stocks fell nearly 2% as the recent rally faded, while property, financials, and consumer sectors also declined ahead of China’s loan-prime-rate decision. XPeng plunged 10.9% on weak margins and guidance, China Hongqiao sank 6.4% on a discounted share sale, and Leapmotor lost 4.7% despite strong revenue. Xiaomi warns of rising smartphone prices due to soaring memory chip costs, driven by AI demand. Despite challenges, Q3 revenue grew by 22.3% to 113.1 billion yuan. Xiaomi's EV business posted its first profit, significantly boosting overall earnings. Baidu reports a 7% revenue decline in Q3, struggling in advertising and AI sectors.
Earnings this week: Wednesday Thursday Friday
US: Nvidia, Palo Alto, Lowe’s, Target, Viking
Asia: Kuaishou, Lenovo, ZTO Express, Tokio Marine, SOMPO, MS&AD Insurance
US: Walmart, Warner Music Group, Intuit
Asia: Webull
US: BJ’s Wholesale Club
Asia: Meituan
FX:
- USD remained largely unchanged with DXY trading around 99.60 as lackluster job data indicates potential for additional Fed easing. Initial claims hit 232k, aligning with diminished labor strength, while ADP reported a loss of 2.5k jobs over four weeks.
- In G10 FX, CAD, AUD, and NZD gained, buoyed by stronger commodity prices, while GBP and EUR were flat. Despite the RBA’s nuanced take on potential caution and data dependency, AUDUSD above 0.6500. USDCAD dipped to 1.3980.
- JPY struggled despite US equity sell-offs due to domestic pressures and geopolitical tensions with China affecting tourism. Verbal intervention from Japan’s finance minister gave JPY modest overnight strength, USDJPY trading above 155.50.
- EURUSD and GBPUSD stayed range-bound with minimal currency-specific newsflow. As the UK budget approaches, the market awaits potential catalysts.
Commodities:
- Gold rose 0.1% to $4,071.89, stabilizing as investors weighed a decline in global equities, concerns over tech valuations, and fading hopes for a US rate cut. While gold often acts as a safe haven in market turmoil, it may temporarily dip as leveraged positions are unwound. Silver edged higher, while palladium and platinum moved lower.
- Oil steadied as traders weighed rising US stockpiles against concerns about Russian sanctions. WTI held below $61 a barrel after a 1% gain Tuesday, with Brent near $65. The American Petroleum Institute reported a 4.4 million barrel increase in US crude inventories, suggesting the highest levels in over five months if confirmed by official data.
Fixed income:
- Treasuries ended mixed with a steeper curve; gains were in the front-end while long-end tenors stayed unchanged due to high corporate issuance and an upcoming $16 billion bond auction. Yields rose from session lows, with $12 billion in corporate bonds led by Pfizer's $6 billion offering. Australian bonds saw gains ahead of a $1 billion sale and wage data. Japan plans an 800 billion yen JGB issue. Global US Treasury holdings dipped from $9.26 trillion in August to $9.25 trillion in September; Japan's holdings rose, while the UK's fell by $39.3 billion to $865 billion.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.