
Access all our platforms from a single account.

Asia Market Quick Take – December 2, 2025

Key points:
- Macro: US ISM Manufacturing PMI drops to 48.2, indicating sector contraction
- Equities: US stocks fall; Synopsys rises 4.9% following investment from Nvidia
- FX: Yen rallies on BOJ hike bets; USDJPY sees significant intraday swing
- Commodities: Silver holds near record; Oil gains amid Trump Venezuela actions
- Fixed income: Treasury futures decline following JGB selloff after BOJ hawkish remarks
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- The US ISM Manufacturing PMI fell to 48.2 in November 2025, its lowest in four months, signaling deeper sector contraction. Key declines were seen in supplier deliveries, new orders, and employment, while workforce management focused on maintaining headcounts.
- The S&P Global US Manufacturing PMI reached 52.2 in November 2025, slightly above estimates but down from October's 52.5, indicating moderating sector improvement. Output increased strongly, aided by new orders, while demand growth was modest amid uncertainty. Record inventory surges reflected softer sales.
- BoJ Governor Kazuo Ueda provided a clear indication of a potential interest rate hike, suggesting such a move might occur at the BOJ's December meeting on Monday.
- US Commerce Secretary Howard Lutnick confirmed that tariffs on South Korean imports, including autos, will drop to 15% retroactive to November 1, following South Korea’s legislative actions supporting strategic U.S. investment commitments. This aligns with their trade agreement under President Trump.
Equities:
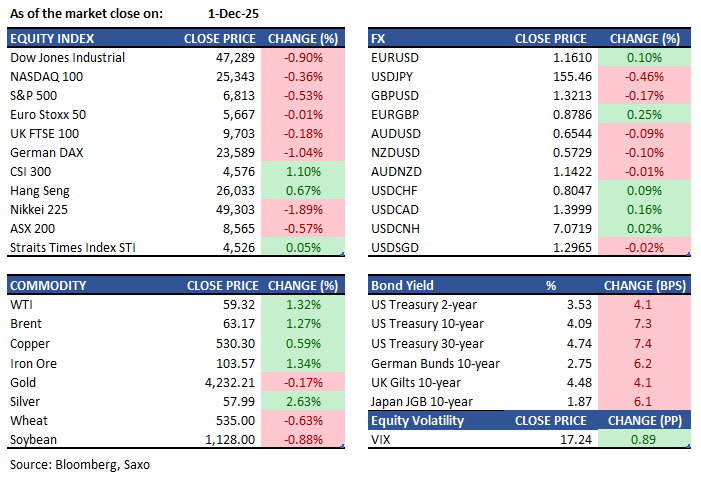
- US - U.S. stocks retreated at December’s start, ending a five-day winning streak. The S&P 500 slipped 0.4%, Nasdaq eased 0.3%, and Dow fell 0.8% as caution prevailed ahead of key data, including the delayed September PCE report and next week’s FOMC meeting. Bitcoin plunged over 6% below 86,000, extending its decline and weighing on risk sentiment, dragging crypto-linked names like Coinbase (-4.8%). Broadcom dropped 4.3% amid profit-taking in AI leaders, while Microsoft, Alphabet, and Meta lost about 1%. Synopsys surged 4.9% after Nvidia’s investment, with Nvidia up 1.7%. Retailers gained as holiday shopping momentum lifted Home Depot and Walmart.
- EU - European equities started December on a cautious note, with the STOXX 50 finishing flat at 5,669 and the STOXX 600 slipping 0.2% to 575 after a volatile November. Airbus plunged 5.7%, having dropped over 10% intraday, on reports of a new quality issue affecting A320-family jets, following recent software glitch fixes. Defense stocks weakened amid optimism for Ukraine peace talks, with Rheinmetall (-2.4%), Rolls-Royce (-1.3%), and BAE Systems (-2.1%) lower. ASML gained 2.6% after Fitch reaffirmed its rating, while miners outperformed: Fresnillo jumped 4.7%, Anglo American rose 1.4%, and Glencore added 2.1%, providing some support to the broader market.
- HK - Hang Seng climbed 174 points, or 0.7%, to 26,033 on Monday, rebounding from the prior session’s drop. Gains were supported by optimism over potential U.S. rate cuts and hopes for fresh Chinese stimulus after weak November PMI data signaled continued manufacturing softness. Chinese equities rose for a third day, fueled by AI enthusiasm, though upside was capped by a sharp decline in U.S. futures ahead of key economic releases and Trump’s Fed pick. Property stocks led advances, with Sun Hung Kai up 1.9%. ZTE surged 10% on 5G deals in Vietnam, while Meituan fell 3% after reporting its first quarterly loss since 2022.
Earnings this week:
- Tuesday: Scotiabank, Marvell Technology, CrowdStrike, TD Bank
- Wednesday: Royal Bank of Canada, Salesforce, Dollar Tree, Macy's, Snowflake, C3.ai
- Thursday: Kroger, Dollar General, DocuSign, Ulta Beauty, Hewlett Packard Enterprise
- Friday: Victoria's Secret, MoneyHero
FX:
- The yen rallied against major peers as traders ramped up bets on a Bank of Japan rate hike this month, helping spark a global bond selloff; USDJPY jumped nearly 1% intraday to 154.67—the biggest move in six weeks—before giving back about half in New York. BOJ Governor Kazuo Ueda flagged the possibility of a December hike, framing it as an adjustment to the degree of easing with real rates still very low.
- EURUSD rose 0.1% to 1.1608, aiming for a sixth straight daily gain, with resistance at 1.1634 (55-DMA) that hasn’t been closed above since October; EURGBP climbed 0.3% to 0.8787, up a third day after support around 0.8740 held.
- USDCAD reversed losses to gain 0.2% at 1.3999, poised to snap its longest losing streak since May; AUDUSD was steady at 0.6544 after Monday’s dip broke a six-day rally; NZDUSD eased 0.1% to 0.5723 and may range before the next leg higher, using sub 0.5700 as a base and 0.5845 (October high) as an initial target.
Commodities:
- Oil held gains as traders awaited President Trump’s moves on Venezuela and assessed Black Sea terminal damage; WTI stayed above $59 after a 1.3% rise and Brent near $63, following his Monday meeting as US forces massed and rhetoric intensified.
- Silver steadied around $57.90, within a dollar of a record, after an 8% two‑day surge and amid speculative bets on tightening supply, with record October inflows into London easing a squeeze as SHFE‑linked inventories hit a decade low; in Asian early hours silver was little changed at $57.8879, gold was steady, and palladium and platinum edged lower.
Fixed income:
- Treasury futures fell, extending losses after a sharp JGB selloff on BOJ Governor Ueda’s hawkish remarks, with yields near session highs as investors awaited nearly $16bn of supply led by Merck’s $8bn eight‑part deal; the US 10‑year was 8bp cheaper at 4.09%, marginally underperforming bunds and gilts, as higher oil and a busy IG calendar kept pressure on rates, with Monday’s issuance already over three‑quarters of the $20bn weekly target.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.