
Access all our platforms from a single account.

Asia Market Quick Take – 27 August, 2026

Key points:
- Macro: Core PCE matches expectations; Headline PCE at 0.2% vs 0.1% expected
- Equities: Nvidia rose 5% after raising 2028 revenue guidance to 70% growth
- FX: PCE print boosts Fed hike bets and USD; AUD leads, JPY firms
- Commodities: Gold ended a five-day rally as yields and the dollar climbed
- Fixed income: Yields rose, with short-dated Treasuries underperforming
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- The US PCE price index rose 0.2% month-on-month in July 2026 after a 0.1% drop in June, above the 0.1% forecast. Services inflation climbed 0.3% while goods prices fell 0.1%. Core PCE also rose 0.2%. Year-on-year, headline PCE stayed at 3.7% and core at 3.3%.
- US personal spending rose 0.2% in July 2026, above the 0.1% forecast but down from 0.3% in June, as higher services outlays offset a drop in goods. Real consumer spending was roughly flat after a 0.4% gain in June.
- US durable goods orders rose 1.1% m/m in July 2026, the strongest since April and above the 0.5% forecast, driven by transportation and gains in capital goods, metals, and machinery. Ex-transport, orders rose 0.4%, while core non-defense capital goods ex-aircraft, a capex proxy, increased 0.2%.
- Iran and Oman agreed on how to share Strait of Hormuz waters and revenues, but Tehran said reopening the waterway needs more than this deal. Trump said 10 million barrels moved through Hormuz Tuesday and reiterated that mines were cleared. Oil prices fell as new US sanctions on Iran were milder than feared, even as reports of a planned Russian escalation in Ukraine kept energy risks in focus.
- The US economy grew at a 1.5% annualized rate in Q2 2026, down from 2.1%. Consumption rose 3.4% and fixed investment 7.0%, including a 1.3% rebound in residential investment, while government spending fell 1.0% and net exports weighed on growth as imports far outpaced exports.
Equities:
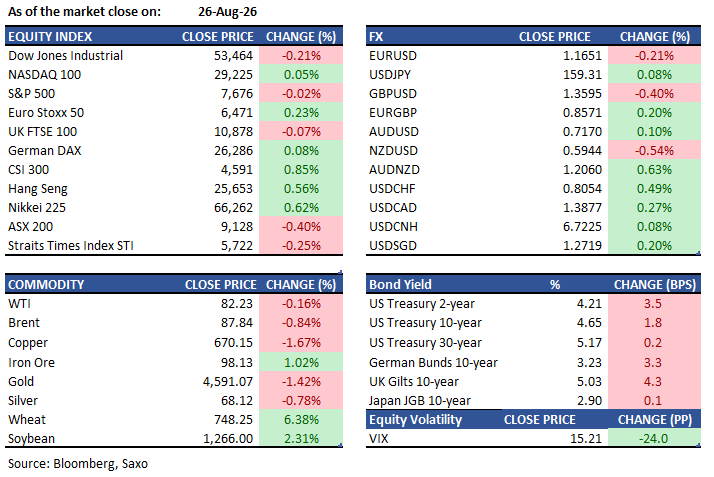
- US — S&P 500 closed little changed at 7,675.70 on Wednesday, while the Dow Jones fell 0.2% to 53,463.88 and the Nasdaq Composite edged down less than 0.1% to 26,130.20.Meta rose 1% on news of a social media litigation settlement, but weighed on peers Alphabet, Snap and Reddit as this sets the precedence for other social media platforms to undergo similar penalties. After hours, Nvidia rallied 5% on a Q3 revenue forecast of $105.84–110.16bn (vs. $105.15bn estimate) and bullish FY28 guidance, raising it to ~70% revenue growth from 44%. CrowdStrike surged 11% post-market after beating earnings estimates, with revenue growing 26% from a year earlier and raising full-year guidance to $5.99b - $6.01b. Salesforce gained 12% after beating earnings estimates (grew 87%) and raised revenue forecasts to $46.1-$46.4b this year. They also announced a partnership with Anthropic called Claudeforce which will launch plugins integrating with the Salesforce software. S&P 500 futures gained 0.6% and Nasdaq 100 futures climbed 1.2% in extended trading.
- EU — European equities were broadly steady on Wednesday. The Stoxx 600 closed little changed at 656.41, with the Euro Stoxx 50 edging up 0.23% to 6,470.74 and the CAC 40 gaining 0.27% to 8,462.39. The DAX rose 0.19% to 26,285.96, led by Heidelberg Materials (+5.2%). The FTSE 100 dipped slightly to 10,878.12, with AstraZeneca (-1.9%) and Sage Group (-3.8%) leading declines, though the index briefly touched an all-time intraday high of 10,912.60. SAP fell 2.9% and Ferrovial dropped 5.0%. Danish medical device maker Ambu sank as much as 18% after an earnings miss and a Nordea downgrade. Swiss Gurit surged 20.8% after upgrading full-year guidance.
- Asia — Asian equities opened sharply higher on Thursday, driven by Nvidia's bullish FY2028 revenue outlook. The Kospi surged 2.8% to 6,996.12 at the open, approaching the psychologically significant 7,000 level for the first time this month, with SK Hynix, Samsung Electronics and SK Square leading gains. The Bank of Korea's expected back-to-back 25bp hike is seen as priced in. Japanese equities also firmed in early trade. Kioxia announced plans to invest over ¥1 trillion to build a new NAND flash memory facility in Iwate Prefecture. Chubu Electric Power came under scrutiny after Nikkei reported its decommissioning procedures at the Hamaoka nuclear plant may have been improper. Haidilao jumped up to 6.1% after 1H results showed stronger‑than‑expected operating profit growth, margin expansion and a surprise increase in payout to 100% of earnings.
Earnings this week:
- Thursday (27 Aug) — Marvell, IREN, Affirm
- Friday (28 Aug) — BYD, China Construction Bank, ICBC, Agricultural Bank of China, Bank of China
FX:
- USD strengthened on Wednesday, with the Bloomberg Dollar Spot Index rising 0.2%—its biggest daily gain since August 10—as a firm PCE inflation print pushed US yields higher and widened rate differentials versus Europe and Canada.
- EURUSD slipped to 1.1651 as the recent rally stalled on wider US‑EU spreads, overbought signals and option-related caps.
- GBPUSD underperformed, dropping 0.37% to 1.3595, hit by the stronger dollar and UK‑specific concerns around the higher energy price cap and inflation, with September seasonality and BOE risks flagged as additional headwinds.
- USDJPY firmed to 159.31 within a 158.88–159.45 range, still capped below 160 amid intervention worries, while options pricing shows reduced demand for topside protection.
- AUDUSD held up best among majors, closing at 0.7170 in a tight range, whereas NZDUSD fell to 0.5944, widening AUDNZD.
- USDCAD rose to 1.3877 as sticky US core PCE (3.3% y/y) reinforced Fed–BoC divergence, and USDCHF climbed to 0.8054 as gold, rather than CHF, captured more of the haven bid.
Commodities:
- WTI traded below $82 a barrel and Brent closed below $88, taking the week's decline to approximately 6%. Futures initially rose on reports of a potential Russian escalation in Ukraine before reversing after Iran's military reportedly reached a revenue-sharing agreement related to Hormuz shipping. Cushing, Oklahoma stockpiles rose for the third time in four weeks to 22.4 million barrels. The Trump administration has also reportedly depleted the Strategic Petroleum Reserve by about 30% since the start of the Iran conflict.
- Gold is up 7.8% year-to-date at $4,657.17 an ounce. ETFs added 205,710 troy ounces in the last session — the fourth straight day of inflows — equivalent to $958 million. Combined gold and Bitcoin ETF inflows totalled a record $7 billion over the past five trading days, reflecting a simultaneous scarcity trade in both assets.
Fixed income:
- Yields edged higher across the curve after the July PCE print came in above expectations. The 2-year yield rose ~4–5bps to 4.21%, while the 10-year climbed ~3bps to 4.65–4.66% and the 30-year rose less than 2bps to 5.18%. Short-dated Treasuries underperformed as money markets moved to fully price a December Fed rate hike.
- The Treasury's $70 billion 5-year note auction was awarded at 4.393%, tailing the 4.391% when-issued yield at the bidding deadline — the tenth consecutive weak result for the tenor.
- The 30-year swap spread has narrowed to its tightest since February since Bessent's buyback announcement, and Morgan Stanley Investment Management has trimmed its curve steepener exposure, citing Bessent's apparent willingness to do "whatever it takes" to cap yields. Australian 3-year yields rose 7bps to 4.67% and 10-year yields climbed 6bps to 5.09%, tracking the overnight Treasury move.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.