
Access all our platforms from a single account.

Asia Market Quick Take – 23 September, 2026

Key points:
- Macro: Trump threatens Iran but also mentions productive talks
- Equities: Semiconductors up for 6th consecutive day
- FX: South Korean won led G10 and EM FX gains
- Commodities: Oil extends slide; copper nears record high
- Fixed income: US Treasury curve bear-flattening, 10Y near 5%
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Trump said US and Iranian officials held a “very productive” meeting and that he is weighing a deal versus “annihilating” the Islamic Republic, while a senior Iranian official signaled Tehran could reopen the Strait of Hormuz within seven days if Washington eases its oil blockade. At the same time, Saudi Arabia is working to restore flows through its East‑West pipeline, reviving an export route that bypasses Hormuz.
- Trump warned that the US would strike Pickaxe Mountain if any activity is detected there.
- Trump–Xi summit: Xi Jinping arrives in Washington for his first US state visit in 11 years, with talks set to cover trade, AI, and geopolitics. Wall Street expects few breakthroughs, and Xi is not bringing a large CEO delegation, unlike the sizeable US corporate contingent.
- Australia’s flash manufacturing PMI fell to 49.3 in September from 52.0, the first contraction since March, with output down to 46.4 on weaker new and export orders, worsening supply delays, and still-elevated energy and fuel costs.
- Euro area consumer confidence fell to -16.5 in September 2026 from -15.5, missing forecasts of -16 and breaking a four‑month improving trend amid geopolitical and inflation worries. EU-wide confidence also weakened, dropping to -15.8 from -15.
- The Fed’s Fifth District manufacturing index dropped to -2 in September 2026 from 4, its first contraction in six months and below expectations of 5, as shipments, new orders, and backlogs weakened even as employment improved; six‑month expectations for activity remain positive but have softened for capex, inventories, prices, and hiring.
Equities:
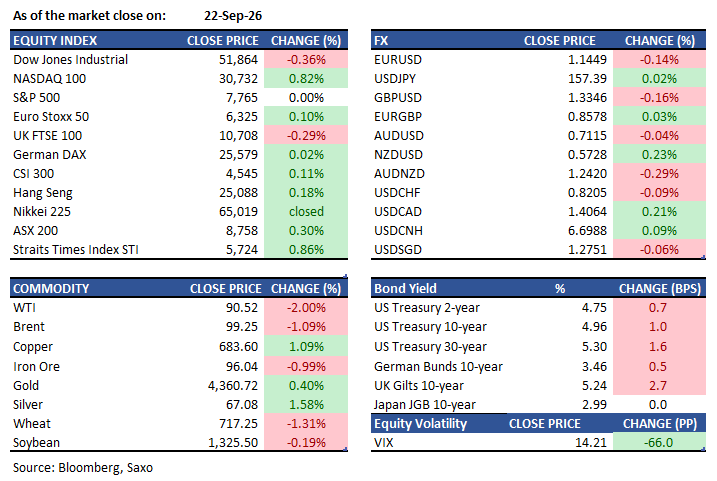
- US — The Nasdaq 100 rose 0.8% on Tuesday to close at 30,732, its first record since June, driven by a sixth consecutive day of gains in the Philadelphia Semiconductor Index. S&P 500 closed little changed at 7,764.64, while the Dow Jones fell 0.4% to 51,959.7. Financials were the worst-performing sector, dropping 2% — the most since March — on Meta Muse disruption fears, with JPMorgan and major insurers leading declines. This selling was absorbed by e commerce websites including Shopify (7%) who moved quickly to integrate into Muse and CPU & memory manufacturers like Intel, AMD and Arm holdings. Viking Therapeutics surged 36%, its best day since February 2024 after positive GLP drug trial results
- EU — The Stoxx Europe 600 rose 0.1% on Tuesday to 642.78, its highest close since September 8, led by the technology sub-index (+1.5%) tracking Nasdaq gains. ASML contributed the most to index gains (+1.8%). Kingfisher surged 12.4% — the largest single-stock move — after boosting its full-year adjusted pretax profit forecast. The FTSE 100 fell 0.3% to 10,708.33, dragged by HSBC (-1.6%) and BT Group (-3.8%). The DAX was little changed at 25,578.85, with Zalando gaining 3.7%. UBS weighed on the SMI, falling 3.4%.
- Asia — Asian equities rose for a sixth straight session on Wednesday morning, with the MSCI Asia Pacific Index up 0.4%. The Hang Seng Index closed Tuesday up 0.2% at 25,087.75, led by Tencent (+5.0%) on AI optimism, with mainland investors buying a net HK$12.7 billion via Stock Connect — the most in five weeks. The Kospi opened Wednesday up 1.9% at 7,153.99, primed to take the rally baton from US memory stocks Micron and Sandisk. The STI rose 0.9% on Tuesday ahead of the Trump–Xi summit. Japanese markets remain closed for a public holiday, with Nikkei futures and SoftBank ADRs trading higher in their absence. Asian bank and insurer stocks face headwinds at the open on Meta Muse disruption fears.
Earnings this week:
- Tuesday: AutoZone (Q4 2026), KB Home (Q3 2026), Worthington Enterprises (Q1 2027)
- Wednesday: Cintas (Q1 2027), General Mills (Q1 2027)
- Thursday: Darden Restaurants (Q1 2027), Costco Wholesale (Q4 2026, after market), H&M, BlackBerry
Key Events:
- Thursday: Trump-Xi Summit
FX:
- The euro fell for a second day, drifting toward 1.1445 and approaching the bottom of its Bollinger band. A break below 1.14 opens the path toward the July monthly low of 1.1353. ECB Chief Economist Philip Lane flagged inflation staying more elevated than expected, adding to ECB repricing risk.
- The yen traded around 157.56, with Japan closed for a holiday dampening liquidity. The pair saw a sharp intraday reversal earlier in the week — dropping 50 pips in one minute — as traders remain on alert for potential BOJ intervention. The BOJ raised rates to 1.25% last week but failed to provide clear guidance on the next move.
- The South Korean won was the best-performing G10/EM currency on Tuesday, strengthening 1.2% against the dollar, driven by the semiconductor rally and Kospi futures surging 2.6%.
- USDCNH rose 0.1% to 6.6983 and USDCNY closed at 6.7005, despite the PBOC setting its eighth consecutive stronger-than-expected fixing. Implied volatility on the offshore yuan slipped to its lowest in over two weeks. The yuan is seen as the biggest potential beneficiary from a positive Trump–Xi summit outcome.
Commodities:
- WTI fell below $90/bbl and Brent settled near $99.25, extending a roughly 10% decline over the prior five sessions. Progress in US–Iran talks at the UN and Saudi Arabia's move to restart a key pipeline drove the selloff. The drop in oil is providing a meaningful tailwind to risk assets and bonds.
- Gold spot last traded at $4,362.76/oz. Bullion pared earlier losses of as much as 1.2% as crude recovered from intraday lows, reflecting gold's high sensitivity to oil's influence on the Fed rate path. Real 10-year US yields rose 1.3bps to 2.63%, up 71bps year-to-date, maintaining headwinds for non-yielding assets.
- Copper neared records as LME prices rose a sixth day and NY futures hit an all-time high, driven by falling inventories and pre-holiday buying tightening China’s market as imports went straight to fabricators, keeping spot supplies tight. Separately, US retail diesel prices have surpassed $6.50/gallon for the first time, with Trump's endorsement of a potential export ban adding headline risk for refining stocks including Valero, Marathon Petroleum, and Phillips 66.
Fixed income:
- The 10-year yield closed at approximately 4.957% and is indicated at 4.965% this morning, while the 30-year sits at 5.303%. The front end has borne the brunt of Fed tightening expectations, with 2-year yields at 4.758% — up more than 50bps over the past month. Real 10-year yields rose to 2.63%, up 71bps year-to-date.
- Tuesday's 2-year note auction was awarded at 4.787%, tailing the when-issued yield by 0.2bps, indicating demand fell slightly short of expectations despite offering the highest yield since mid-2024. Treasuries ended the session lower as oil recovered from intraday lows. This week's supply schedule also includes $70 billion in 5-year notes (Wednesday) and $44 billion in 7-year notes (Thursday).
- Pimco CIO Daniel Ivascyn said the firm is taking a more balanced approach to US government debt as long-term yields trade near two-decade highs, trimming both its bullish stance on 5–7 year Treasuries and its bearish position on the long end. HSBC's new ML model (DUSTIN) points to conviction for lower US 10-year yields over the coming month, citing the recent front-end selloff and economic activity surprises.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.