
Access all our platforms from a single account.

Healthcare rotation: A timely diversification opportunity for tech-heavy portfolios

Key points:
- Healthcare was the best-performing S&P 500 sector over the past month, while information technology was one of the weakest.
- This divergence may indicate that markets are becoming more selective and are rewarding sectors with resilient earnings profiles.
- For tech-heavy portfolios, healthcare offers a second growth engine driven by demographics rather than chip cycles, though investors should remain mindful of drug-pricing uncertainty, trial risks, and policy headwinds.
A visible rotation: Healthcare outperforms while tech pauses
Over the past month, the S&P 500 Healthcare Index gained roughly 8+%, outperforming every major sector, while the S&P 500 Information Technology Index fell by approximately 3-4%. Eli Lilly, Cardinal Health, Regeneron, Biogen, and Merck were among the strongest contributors, with several delivering 20–30% monthly gains.
In our opinion, markets have been dominated by AI-driven leadership for much of the past two years, but the recent combination of AI-bubble concerns and rising macro uncertainty—including signs of softer US economic data—is encouraging investors to take a more defensive stance. At the same time, the healthcare sector’s outperformance should be viewed with caution: healthcare faces its own set of risks, including reimbursement pressure, regulatory scrutiny, and trial-driven volatility.
This shift does not signal the end of the AI theme. Rather, it highlights a more discerning market environment that demands clearer monetisation pathways and manageable balance-sheet commitments before rewarding AI-linked businesses with further gains.
Why healthcare strength makes sense now
Earnings resilience is attracting flows
Consensus expects S&P 500 healthcare sector earnings to grow 12-15% in 2025, versus 10-12% for the broader S&P 500, according to Bloomberg estimates. Meanwhile, large-cap pharma names such as Eli Lilly and Novo Nordisk have delivered double-digit revenue growth driven by GLP-1 obesity and diabetes treatments.
However, this resilience coexists with risks: drug-pricing debates are intensifying ahead of the US election cycle, and several large pharma names face patent expiries in the coming years. In our view, the sector’s relative stability is attractive — but not immune to headline-driven volatility.
Drug discovery successes are turning into commercial scale
- Global spending on GLP-1 drugs is projected to exceed USD 100 billion by 2030 (IQVIA).
- FDA drug approvals totalled 50 in 2024, above the 10-year average, indicating healthy R&D productivity.
- Oncology, neurology, and metabolic diseases remain the largest revenue pools, with several blockbuster drugs expected over the next five years.
These developments point to durable innovation cycles. Still, drug development remains inherently risky: trial failures can erase years of investment, regulatory approval timelines can shift, and safety concerns can materially affect valuations.
A catch-up move after multiple years of underperformance
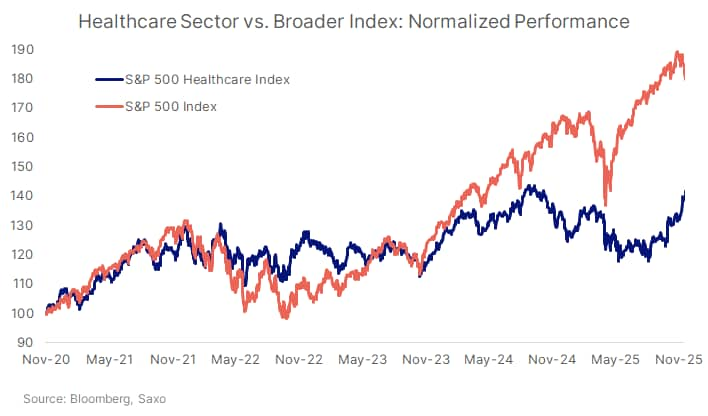
Energy and Information Technology have returned ~170% over the past five years, far outpacing healthcare’s ~60% performance. In our opinion, part of the recent strength reflects mean reversion from years of lagging returns.
Yet relative undervaluation is uneven. Some biotech and medtech names still trade at elevated multiples despite earnings uncertainty, while pharma appears more reasonably valued but faces patent-cliff risks.
Defensive qualities suited to late-cycle conditions
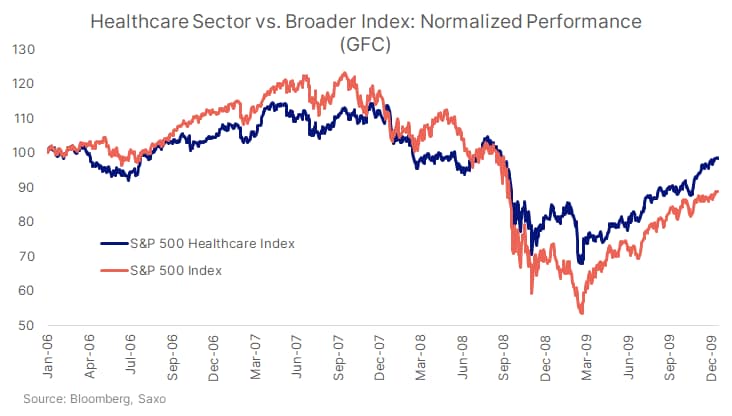
Historically, healthcare has tended to fall less and recover faster during major drawdowns, as shown during the dot-com unwind (2000–2002) and the Global Financial Crisis (2008–09). This behaviour often becomes valuable when growth slows. 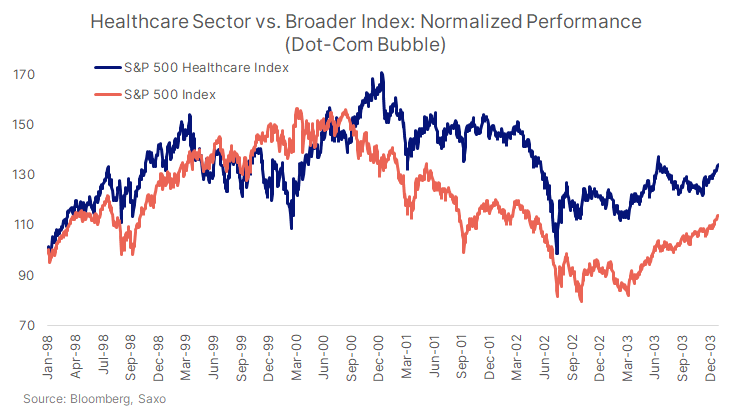
But defensiveness is not uniform. Managed-care stocks can be sensitive to policy shifts; medtech can be exposed to declines in elective procedures; and biotech is particularly vulnerable to funding cycles.
With US macro data showing early signs of softening and volatility rising around AI valuations and rate expectations, healthcare’s relative stability may appeal to investors — though policy and regulatory uncertainties remain key watchpoints.
Understanding healthcare: Key segments and drivers
Healthcare is not a monolith. It consists of several distinct industries with different risk and return characteristics.
1. Biopharma (Pharma + Biotechnology)
- Business model: Develop drugs, acquire pipelines, navigate patents.
- Drivers: Clinical trial success, regulatory approvals, drug pricing, patent cliffs.
- Risk: High R&D uncertainty; binary outcomes around trial data.
- Reward: Blockbuster drugs can generate billions in recurring revenue.
2. Medical Technology (MedTech)
- Includes: Surgical robotics (e.g., Intuitive Surgical), diagnostic equipment, implants, and devices.
- Drivers: Procedure volumes, hospital budgets, innovation cycles.
- Risk: Exposure to slowdown in elective surgeries during recessions.
- Reward: High switching costs and sticky customer relationships.
3. Healthcare Services & Managed Care
- Includes: Insurers, hospital operators, pharmacy benefit managers, distributors.
- Drivers: Policy changes, demographics, reimbursement rates.
- Risk: Regulatory shocks.
- Reward: More stable cash flows relative to biotech.
4. Life Sciences Tools & Diagnostics
- Includes: Lab tools, testing equipment, sequencing technologies.
- Drivers: Research budgets, biotech funding cycles.
- Risk: Sensitive to capital markets conditions.
- Reward: Picks-and-shovels to the biopharma industry.
Investor takeaway: Healthcare is diversified internally, offering growth (biotech), stability (pharma), cyclicality (devices), or cash flow (managed care). But each subsector carries distinct risks alongside its potential benefits.
Tactical vs structural drivers of healthcare
Healthcare sits in a rare sweet spot:
- Defensive: demand for drugs, devices and services is stable even when growth softens.
- Growth: new therapies, robotics, genomics and diagnostics are multi-year innovation cycles.
Tactical (6–12 months)
- Rotation into defensive growth as macro volatility increases.
- Greater scrutiny of AI-linked revenue in tech, increasing the appeal of earnings stability.
- Attractive relative valuations after multiple years of underperformance.
- Positioning normalization after crowded trades in tech.
Structural (multi-year)
- Ageing populations in the US, Europe, China, and Japan driving chronic disease prevalence.
- Rising middle-class healthcare consumption in emerging markets.
- Strong innovation in obesity, oncology, genetics, and neurology.
- Increased adoption of robotics and minimally invasive procedures.
- Long-term capital flows into real-world clinical data and precision medicine.
Risks that investors should keep in mind
To maintain a balanced view:
- Drug pricing risk in the US as election rhetoric builds.
- Patent cliff risk for major pharma names whose blockbuster drugs lose exclusivity.
- Clinical trial failures that can significantly impact biotech valuations.
- Valuation risk if recent inflows accelerate excessively.
- Regulatory scrutiny on M&A and pricing power in certain sub-industries.
Healthcare is therefore not a “low-risk” alternative but a differently structured risk.
Portfolio implications for tech-heavy investors
The goal is also not to replace AI exposure or step away from structural digital themes.
Instead, the focus is on diversifying growth sources and broaden the drivers of risk and return within a portfolio.
- Different risk engines: Tech is more exposed to liquidity and rate cycles; healthcare to demographics and regulation.
- Different factor profiles: Tech tends to be high-beta and momentum-driven; healthcare leans toward quality and lower volatility — though biotech is an exception.
- Different innovation paths: Tech innovation is concentrated in a few platforms; healthcare is more distributed across drugs, devices, data and services.
- Different macro sensitivities: Tech demand can slow quickly when budgets tighten; healthcare demand remains more stable, though policy risk can disrupt parts of the sector.
For investors who have benefited from the AI-led rally, introducing healthcare exposure can help reduce concentration risk while maintaining exposure to long-term innovation — provided investors remain aware of subsector-specific risks.
This material is marketing content and should not be regarded as investment advice. Trading financial instruments carries risks and historic performance is not a guarantee of future results.
The instrument(s) referenced in this content may be issued by a partner, from whom Saxo receives promotional fees, payment or retrocessions. While Saxo may receive compensation from these partnerships, all content is created with the aim of providing clients with valuable information and options..
The instrument(s) referenced in this content may be issued by a partner, from whom Saxo receives promotional fees, payment or retrocessions. While Saxo may receive compensation from these partnerships, all content is created with the aim of providing clients with valuable information and options..