
Access all our platforms from a single account.

Apple’s AI catchup: What’s powering the move to record highs

Key points:
- Record highs: Apple is back near record highs with a market cap of ~USD 4.2 trillion, close to reclaiming the top spot from Nvidia.
- AI lag turned tailwind: What was seen as an AI lag has become a positive, as Apple pursues a more capital-efficient AI path. A stronger iPhone 17 upgrade cycle has also signalled some front-loading of demand given smartphones could remain the main AI gateway.
- Earnings visibility: Record services revenue above USD 100bn and consensus expectations of ~10% EPS growth in FY26–27 underpin the earnings and cash-flow story, though these forecasts are not guaranteed.
- Risks: A rich ~35x forward P/E, potential cooling of iPhone 17 demand (especially in China), AI execution, and ongoing regulatory scrutiny all leave the stock sensitive to any negative surprise.
The backdrop: A laggard finally waking up
For most of 2025, Apple was the outlier among mega-cap tech. It underperformed the Nasdaq as investors rotated aggressively into AI infrastructure and semiconductor names. Concerns about a muted iPhone upgrade cycle, soft China demand, and a slower on-device AI roadmap kept sentiment cautious.
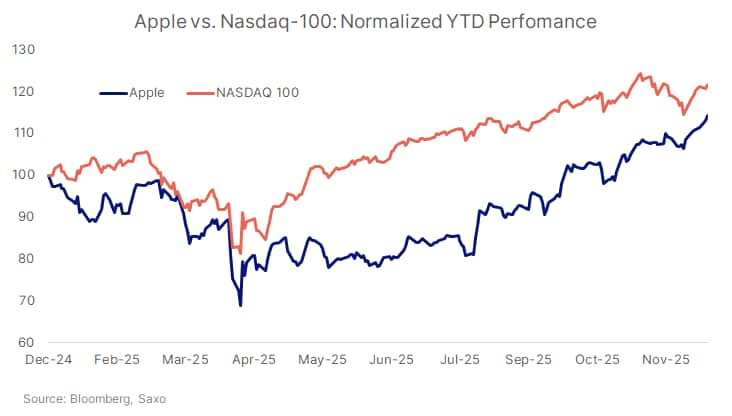
More recently, Apple’s resurgence toward record highs has been one of the more notable shifts in global equity leadership. The company’s market capitalisation has climbed to around USD 4.2 trillion, placing it within reach of overtaking Nvidia as the world’s most valuable publicly listed business. In our view, the combination of improving fundamentals and earlier underweight positioning has created fertile ground for a catch-up move.
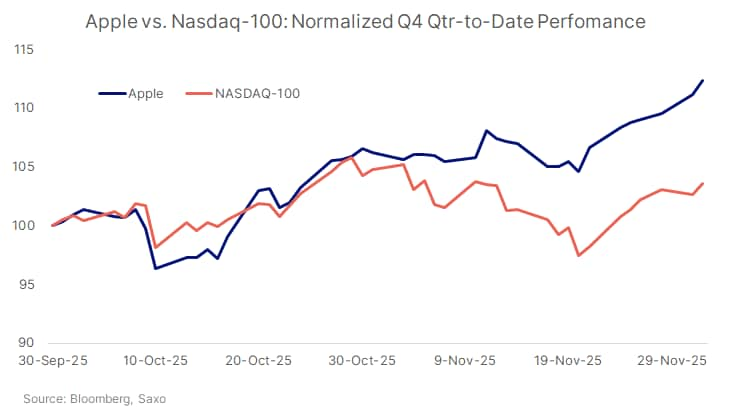
iPhone 17 is the turning point
The most important change has been evidence of a stronger-than-expected iPhone 17 cycle:
- Early sales data in the US and China show double-digit growth versus last year’s iPhone 16 launch.
- Research houses now see iPhone shipments rising around 10% in 2025, with Apple holding its regained lead over Samsung in global smartphone share.
- The revenue line is starting to reflect this: iPhone revenue has returned to growth after several soft quarters.
Given that the iPhone remains the core gateway into Apple’s services and software stack, a healthier upgrade trajectory supports the narrative that Apple is regaining product-cycle momentum. In our opinion, this is particularly important at a time when most consumers are expected to engage with AI primarily through their smartphones rather than dedicated devices.
Services strength supports the re-rating
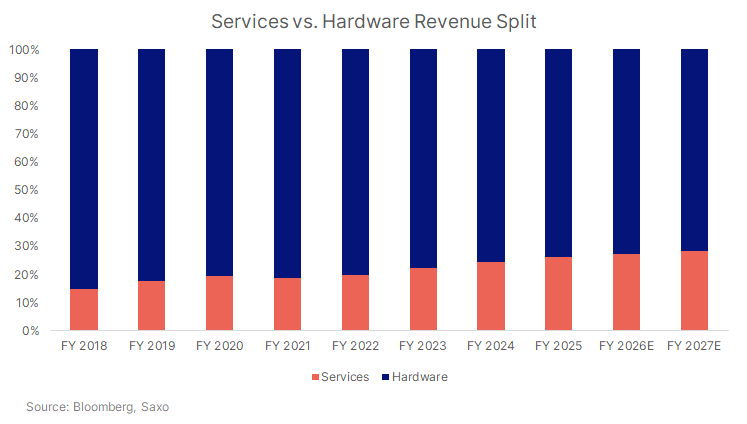
Apple’s services business — App Store, iCloud, Apple Music, TV+, payments — continues to expand at a high-margin clip. It crossed USD 100bn in annual revenue, with strong subscription momentum across regions.
In our view, this has several implications:
- Services are now large enough to stabilise earnings even when hardware cycles run slower.
- The growing installed base gives Apple flexibility to monetise features like AI-enabled on-device tools, cloud storage and content bundles.
Bloomberg consensus forecasts indicate EPS growth of roughly 10% in FY2026 and again in FY2027, alongside gradual margin improvement, reflecting the rising services contribution. These projections are based on Bloomberg analyst estimates, and are subject to change and carry no guarantees. However, the mix shift toward recurring revenue is an important support for valuation at a time when many investors are paying up for more predictable cash flows.
A more credible AI narrative is emerging
Being “late” to the AI race has, in our opinion, turned into an unexpected advantage for Apple. Apple sidestepped the extreme GPU-driven capex cycle that is now weighing on parts of the market, while still positioning itself to benefit from mass-market AI adoption.
Recent developments that have boosted confidence include:
- Management has stepped up its AI messaging, signalling deeper integration of “Apple Intelligence” across apps and devices.
- We think the focus has shifted from competing with hyperscalers to driving a multi-year device upgrade cycle — positioning AI as a reason to refresh iPhones, iPads and Macs, rather than trying to win the race for the biggest foundation model or the largest data centre footprint.
- Apple’s AI leadership has been refreshed. The company has appointed Amar Subramanya as vice president of AI, a veteran who spent many years at Google and most recently led AI at Microsoft. This signals an effort to accelerate the foundation-model, on-device intelligence and AI-safety roadmap.
- Apple is integrating Google’s Gemini AI model into Apple Intelligence and the new Siri, running on its own Private Cloud Compute infrastructure. In the emerging “Google vs Nvidia” AI dispersion story, Apple is increasingly perceived as being closer to the “Google camp”, emphasising more efficient, customised and increasingly on-device compute, rather than a strategy reliant on ever-larger fleets of Nvidia GPUs.
Compared to the tens of billions in incremental capex needed for AI data centres elsewhere, Apple’s approach is generally seen as more capital-efficient, leaning on its own silicon and on-device inference rather than chasing hyperscale GPU build-outs.
In short, many investors now see Apple as a way to participate in AI themes with less direct exposure to AI capex cycles — although this perception could change if the competitive landscape evolves.
Technical forces amplified the move
As fundamentals turned, flows amplified the price action.
- Analysts have upgraded earnings estimates and price targets as the iPhone and services trends improve.
- Apple is a top-15 holding in more than 400 ETFs globally, creating constant passive demand whenever investors rotate into large-cap quality or reduce exposure to higher-beta segments.
- Large buybacks continue to support EPS and reduce free-float supply.
With broader equity volatility rising and questions emerging over the sustainability of AI-infrastructure spending, some market participants appear to view Apple as a relative safe haven within mega-cap tech — though this is a perception, not a guarantee, and does not eliminate the risk of drawdowns.
What could sustain the rally
From here, the positive scenario for the stock in our view rests on several conditions being met:
- Holiday-quarter iPhone 17 sell-through confirming a stronger upgrade cycle.
- Services revenue continuing to compound at a mid-teens pace with high margins.
- AI features rolling out smoothly into 2026, supporting further device monetisation.
- Potential optionality around foldables and new form factors.
In our opinion, if Apple were to sustain >20% services growth and low-single-digit hardware growth, earnings visibility would remain relatively strong even if macro volatility rises. However, none of these outcomes are assured and they depend on both execution and the broader economic environment.
Key risks investors should monitor
To balance the picture, we highlight several key risks:
- Product-cycle risk: iPhone 17 demand could cool faster than current early-cycle indicators suggest, especially given China’s focus on local brands and intense competition in premium and mid-range segments.
- AI execution risk: Any delays in Siri revamps, Apple Intelligence rollouts or perceived gaps versus rival AI features could revive the “Apple is behind” narrative.
- Valuation sensitivity: Apple now trades at a forward P/E of around 34–35x, above its long-term average, leaving it more exposed to shifts in sentiment, interest-rate expectations or any disappointment in the product or earnings cycle.
- Regulatory and legal risk: Ongoing scrutiny over app-store fees, competition issues and digital-platform power could lead to changes in business practices, fee structures or fines over time.
Bottom line
Overall, we see Apple’s move to record highs as the product of stronger iPhone data, record services revenue, a more credible and capital-efficient AI strategy, and powerful passive flows, set against a backdrop of meaningful valuation and execution risks. How the balance between these forces evolves will determine whether the current re-rating proves durable.
Disclaimer: The author does not hold positions in Apple.
This material is marketing content and should not be regarded as investment advice. Trading financial instruments carries risks and historic performance is not a guarantee of future results.
The instrument(s) referenced in this content may be issued by a partner, from whom Saxo receives promotional fees, payment or retrocessions. While Saxo may receive compensation from these partnerships, all content is created with the aim of providing clients with valuable information and options..
The instrument(s) referenced in this content may be issued by a partner, from whom Saxo receives promotional fees, payment or retrocessions. While Saxo may receive compensation from these partnerships, all content is created with the aim of providing clients with valuable information and options..