
Access both platforms from your single Saxo account.

Up a fifth, still the cheapest session - Options Brief - 28 October 2026

Summary: The Federal Reserve decides this evening, and the option market prices today as the quietest of the three sessions left this week. One reading has stayed high while everything else drained.
One measure on the whole volatility board rose yesterday, the one that covers today, and it still prices the quietest of the three sessions left in the week.
MARKET REGIME: TRANSITIONING | VIX 17.52 | TERM STRUCTURE: CONTANGO | SKEW: ELEVATED (149.22) | FRONT-MONTH VIX FUTURES: 19.000
Today in brief
The Federal Reserve decides at 19:00 CET this evening, two hours before the US close, and is expected to leave rates unchanged. Today’s S&P 500 expiry settles at that close, so it contains the decision, and it prices 0.60%. The three sessions to Friday price 1.14% together, which leaves about 0.69% for each of Thursday and Friday. The decision day is the cheapest of the three.
In our view Thursday may carry more: US growth and inflation data, the European Central Bank, and the reaction to tonight’s results from Microsoft and Alphabet. Microsoft stands out. Its options price a move of 4.7% against an average of 7.0% over its last eight reports, the only one of the five companies still to report this season priced below its own average.
The one-day volatility gauge did jump 19% yesterday, the only measure on the board to rise, but even after the jump it sits near the middle of its own range and below every longer one. One reading has stayed high. Implied correlation, a gauge of how closely stocks are expected to move together, eased for a second session but remains at the 94th percentile of the readings we hold. In our view that level may matter: at it, a surprise in one large name is more likely to travel across the index.
The backdrop was firm. The S&P 500 closed at 7,722.60, up 0.60%, and the semiconductor index rose 3.6% after SK Hynix posted record profit, with the Kospi up 6.5%. The S&P 500 has already used 72% of the range priced for this week, upward, with three sessions still to run. Below the index, single-stock volatility drained for a second session, mostly in companies that have finished reporting. In yesterday’s flow the index premium carried no direction, and in the largest names long-dated calls were bought on the ask.
That is the whole brief in one read. The sections below hold the detail behind each paragraph, with the charts, the full set of readings and the sources, for when you want to go deeper on one part.
Headline driver
The Federal Reserve decides at 19:00 CET today, and the last session was spent deciding how little that is worth.
Tuesday was led from Asia. SK Hynix reported record quarterly operating profit of 83.3 trillion won, more than seven times last year’s figure, and the Kospi rose 6.51% to 6,005.33. The memory trade carried into New York, where the semiconductor index gained 3.6% and Broadcom rose 4% after a 63 billion dollar financing deal to supply chips to Anthropic.
Boeing went the other way, down 10.7%, its worst day in six years, on weak results and production delays. Meta eased 1.64%.
The decision itself is expected to change nothing: a hold after September’s 25 basis point increase, with the question left to December, where futures price an 82.5% chance of a higher rate by year end.
Market snapshot
- US (Tuesday 27 October close): S&P 500 7,722.60, up 0.60%. Nasdaq 100 29,651.44, up 1.29%. Dow Jones Industrial Average 52,383.25, up 0.03%. The semiconductor fund rose 3.02% to 557.98 and Tesla 4.04%, while Meta fell 1.64% and Microsoft 0.24%.
- Europe: the Stoxx 600 rose 0.47% to 643.69, the DAX 0.71% to 25,590.77 and the CAC 40 0.51%. The FTSE 100 fell 0.8% on weak results, HSBC down 5.4%.
- Asia (Wednesday morning): the Kospi rose 6.51% to 6,005.33 on SK Hynix, the Nikkei 225 1.1% and the Hang Seng 0.43%.
- Commodities and rates: WTI traded at 101.35 and Brent 110.94, both firmer on renewed warnings of military strikes. Gold eased to 4,056.60 after an Asian rebound stalled, silver to 54.10. The two-year Treasury yield sits at 4.75% and the ten-year back above five at 5.02%. Bitcoin traded near 81,000, the largest bitcoin fund at 45.70.
- Market regime: transitioning, the VIX at 17.52, the cash curve in contango and SKEW elevated at 149.22.
Index levels and volatility readings from the watchlist export taken at 05:00 CET on 28 October 2026, which carries Tuesday’s US closes; rates, oil and single-stock detail from the same-morning Saxo Market Quick Take. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
Volatility surface
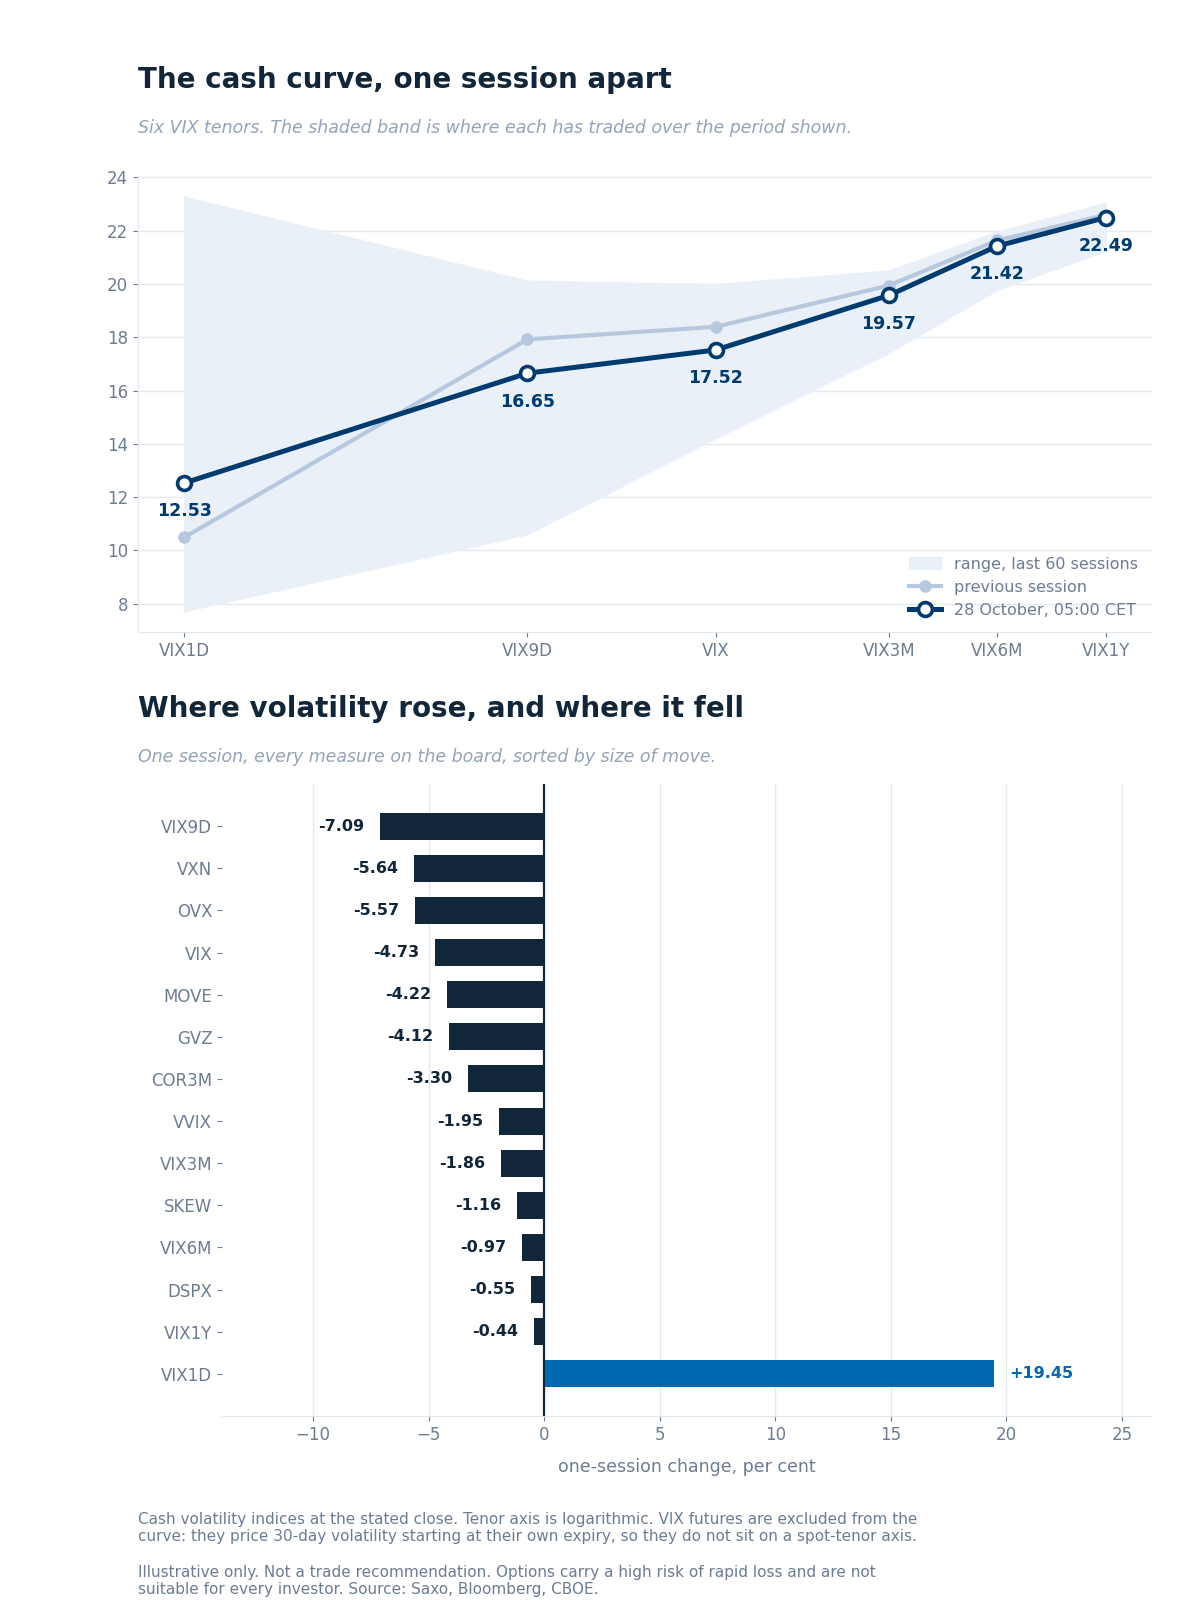
The cash curve against the previous session over each tenor’s 60-session range, with the one-session change across every measure. Illustrative only. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
Thirteen measures fell and one rose. The one-day gauge gained 19.45% to 12.53 while the nine-day fell 7.09% to 16.65, the Nasdaq gauge 5.64% to 24.91 and the small-cap gauge 5.44%. Against the 107 sessions in our store, though, that jump leaves the one-day reading at the 62nd percentile of its own range, below the nine-day at the 79th and the headline gauge at the 78th.
Ratios. VIX1D/VIX reads 0.72 from 0.57, recovering most of Monday’s collapse without reaching parity. VIX3M/VIX rose to 1.12 from 1.08. VXN/VIX eased to 1.42.
VIX futures. November leads at 19.000, a premium of about 1.48 to spot, widened from 0.73 as spot fell faster than the contract. Put-call parity on the 18 November options returns 18.955, consistent to four hundredths across the nearest strikes, so the contract identity holds and no roll has occurred. December sits a shade above at 19.080, so the two are effectively level.
Correlation and tails. Implied correlation fell 3.30% to 13.49, a second session lower, and still sits at the 94th percentile of the store. Dispersion eased to 37.81. SKEW at 149.22 holds above its 145.70 median, the bond gauge dropped below one hundred to 97.88, and gold volatility at 22.58 sits at the 6th percentile of its own year.
Single-name volatility
The index measures above kept draining and the names drained with them, a second session running. On an identical universe of 524 underlyings, so none of this is a composition effect, the median implied-volatility rank fell to 44.0 from 45.9. The mean fell to 46.9 from 48.8 and the median percentile to 60.3, so the whole distribution moved rather than its middle.
Almost all of the fall sits in names that have finished reporting. Beiersdorf lost 47.4 points of rank, PayPal 42.0, UPS 33.5 and American Tower 27.3. Boeing lost 31.0 points on the session it fell 10.7%, which is the cleanest illustration available of what this measure does: the share price moved hard, and the event the options had been pricing was over.
By group the spread is wide. Energy carries the richest volatility, a median rank of 63.6 with 83% of its names above 50, led by Marathon Petroleum at 97.0 and Valero at 89.3. Metals are cheapest at 17.9, with 71% below 20. The index funds sit near the bottom at 21.2, which in our view may be the correlation reading showing up in a second dataset.
Across almost every group the median rank sits below the median percentile. In our view that gap may point to names that are not spiking so much as sitting quietly expensive on a sustained basis.
Source: Saxo.
Options flow sentiment
Based on end-of-day 27 October, yesterday’s positioning, not today’s price action.
- Single-name flow gave one clean reading in the largest names. Long-dated calls were bought on the ask in Tesla, Meta, Alphabet and Apple, and the single largest put print was sold to open rather than bought, so a put-heavy tape need not be read as a bearish one. Away from the mega-caps the tape was unreadable: call buying in AMD printed at mid with no aggressor side, and Taiwan Semiconductor was bought on both sides of one expiry.
- Sector and ETF flow leaned to hedging rather than direction. The large index premium was structured mid-market blocks whose sided legs offset, so the headline totals carry no bet. The one clean-sided sector tape was energy, where puts were bought at the offer in the oil and gas funds and in Exxon Mobil, partly financed by selling further out. Rates, risk-off, financials and metals carried no readable direction.
Where the week's range sits
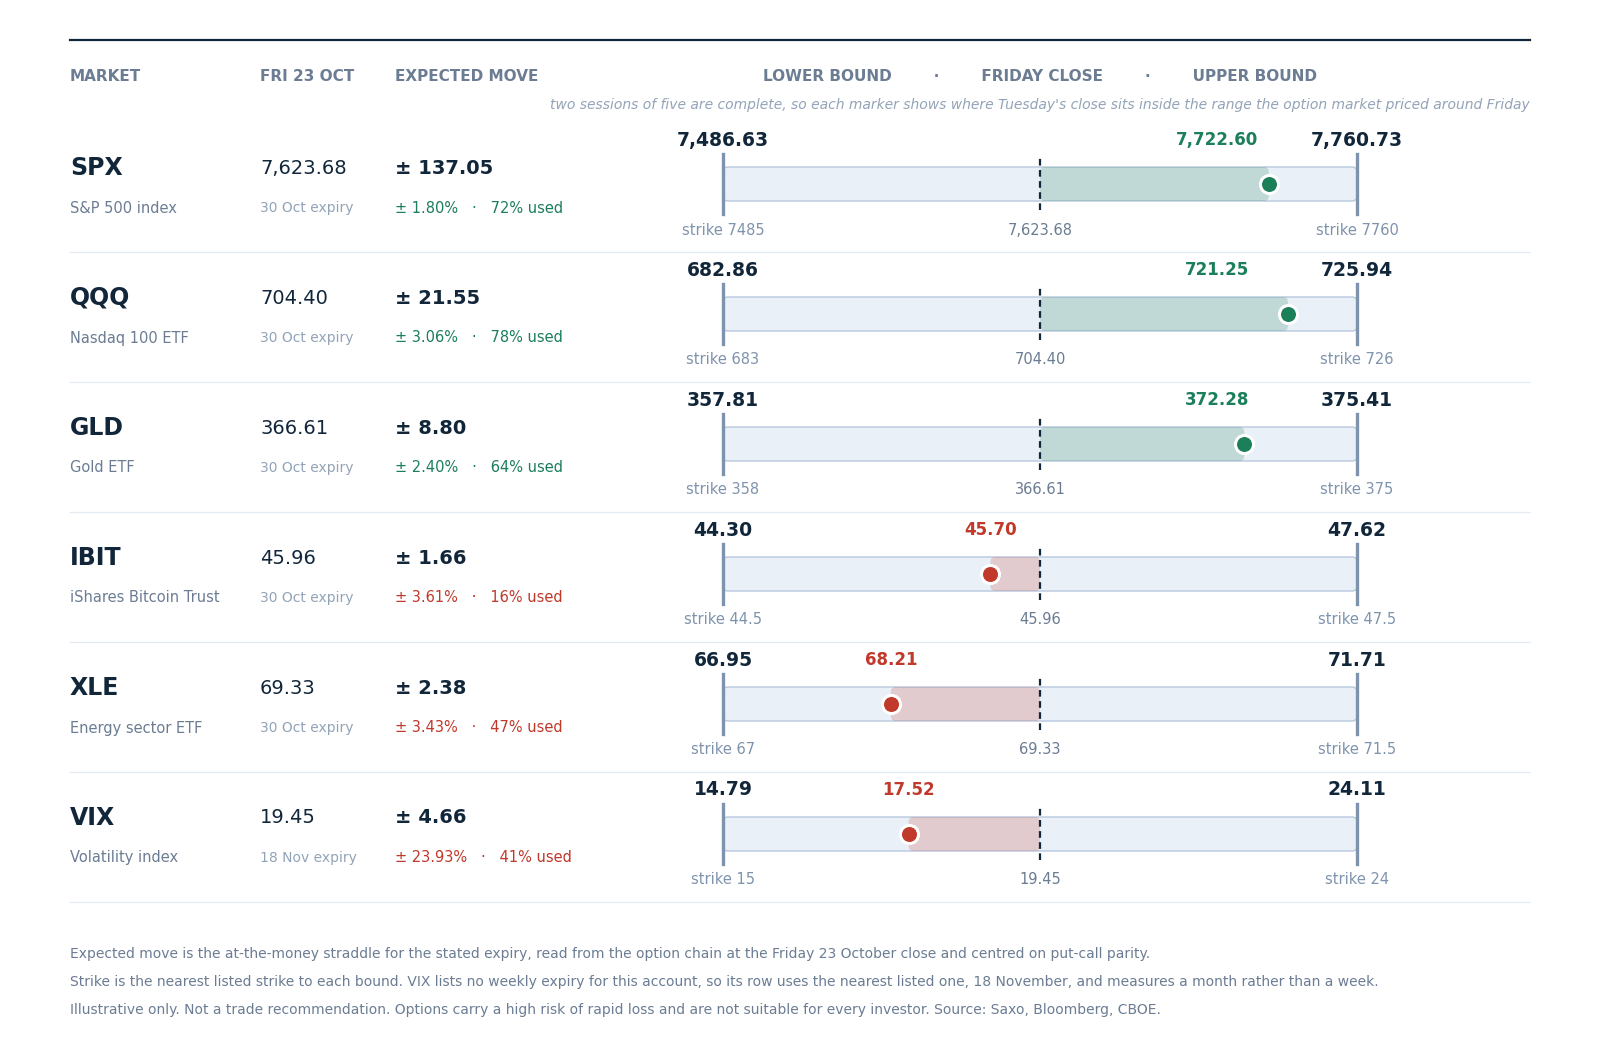
The range the option market priced for this week around Friday 23 October’s close, with Tuesday’s close marked inside it. Straddles are at-the-money, from the Saxo chain, centred on put-call parity. Illustrative only, not a trade recommendation. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
The S&P 500 began the week with 137.05 points priced around Friday’s close, 1.80%, from 7,486.63 to 7,760.73. Two sessions of five are done and Tuesday’s close at 7,722.60 has used 72% of that band upward, leaving 38 points to the top.
The Nasdaq 100 fund has used 78% of its 3.06% band, also upward, and gold 64% of 2.40%. Energy has used 47% downward and the bitcoin fund only 16%, the quietest row on the board. The volatility row uses the 18 November expiry, so it measures a month rather than a week, and sits 41% below its anchor.
Three sessions remain to absorb what is left, with the Federal Reserve still to speak. Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you.
Today's catalysts
- 13:30 CET the September advance goods trade balance.
- 14:45 CET the Bank of Canada rate decision, then at 15:30 CET weekly US crude and product inventories.
- 19:00 CET the Federal Reserve decision, with Chair Warsh’s press conference at 19:30 CET.
- Earnings today: Alphabet, Microsoft, SK Hynix, UBS, Airbus, T-Mobile US, ServiceNow, KLA and FedEx.
- Also today: the UK Autumn Budget, and overnight the European Central Bank and Bank of Japan meetings move into view for Thursday.
Europe left summer time on Sunday and the US has not, so the cash session runs 14:30 to 21:00 CET until 1 November. The decision at 19:00 CET therefore lands two hours before the close, inside the session, and today’s expiry settles at that close.
Earnings scorecard
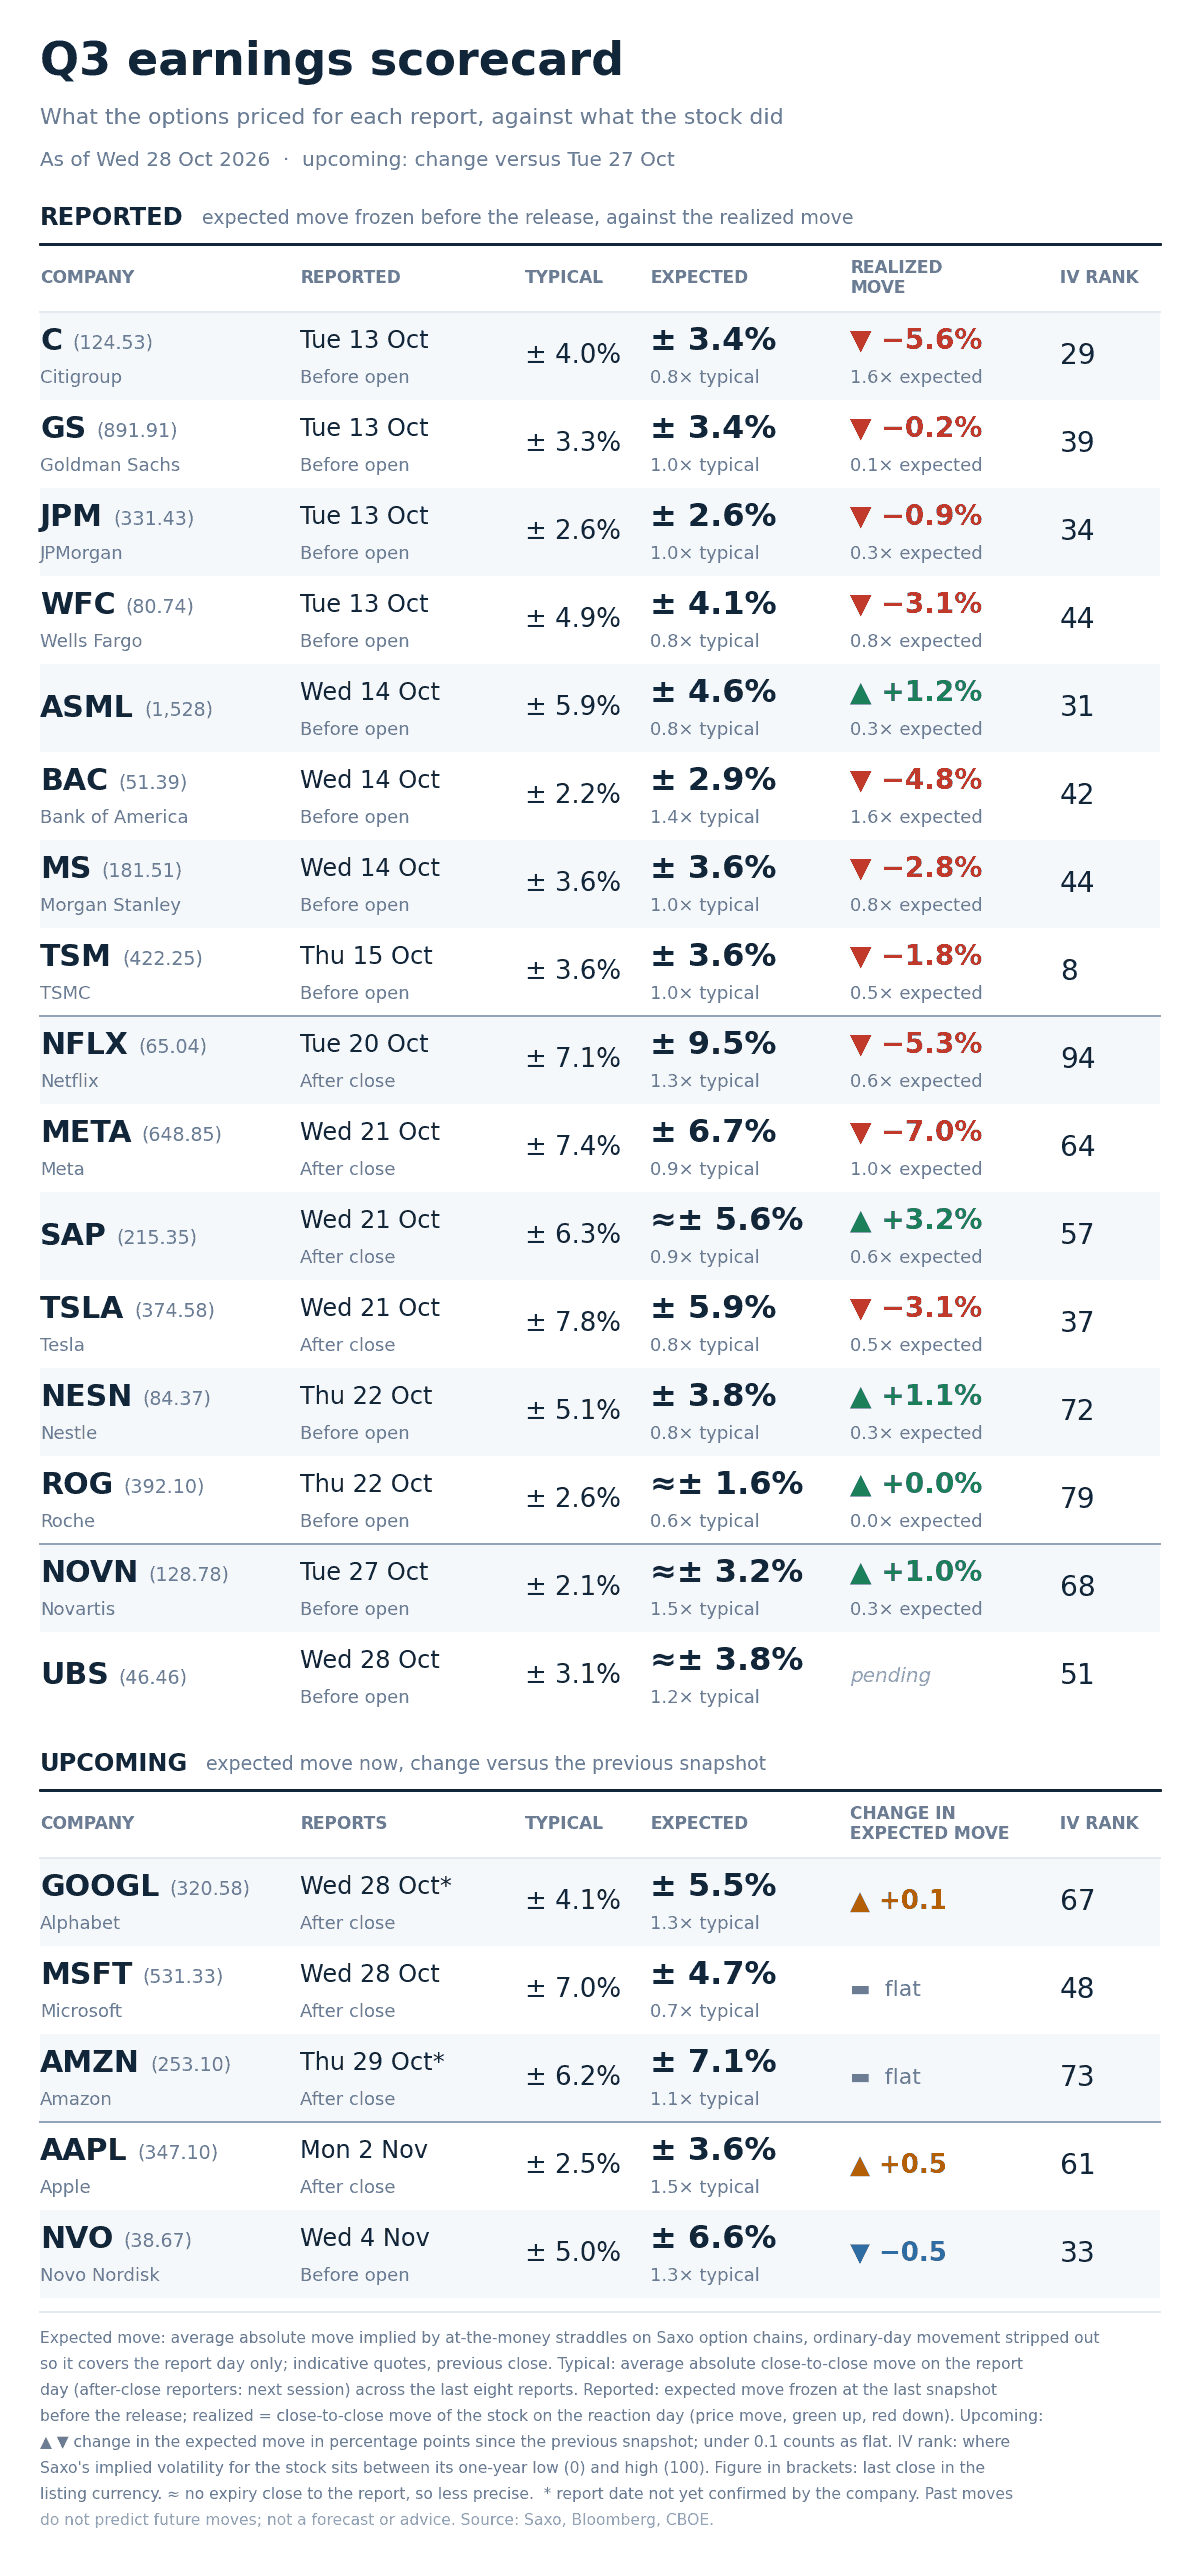
Option-implied expected move for each report day against the stock’s average move after its last eight reports, across the twenty-one names tracked this season. Past performance is not indicative of future results. Source: Saxo, Bloomberg, CBOE.
Five names are left to report and the spread between what is priced and what each has typically delivered runs from 1.5x to 0.7x. Apple is richest, 3.6% priced into 2 November against an eight-report average of 2.5%, and its premium rose half a point overnight. Alphabet sits at 5.5% against 4.1% and Novo Nordisk at 6.6% against 5.0%.
Microsoft is the exception, and it reports tonight. Its 4.7% sits against a 7.0% history, the only name of the five priced below what it has usually done, on a record that includes moves of 15.5% and 10.0% in the last four.
Rank and the event premium answer different questions, and Microsoft shows the gap. It carries a rank of 48 against a percentile of 73, so its volatility is unremarkable for its own year while sitting above most individual days in it. Rank describes a year. The event premium describes one evening.
Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you.
What the market is pricing
- Session implied range: S&P 500 options price 46.40 points, 0.60%, for today’s expiry, which settles at the 21:00 CET close and so contains the decision and the first reaction to it. Read before the US open, so indicative. The one-day gauge at 12.53 implies about 0.8%, a one-sigma figure rather than an expected move, so the two do not disagree.
- Event implied range: the 30 October expiry prices 88.30 points, 1.14%. Yesterday it read 104.90 with four sessions left, so decay alone would have left about 91. About 2.5 points came out beyond the clock, against 16 the day before, so on that measure the draining has nearly stopped.
- Where the week is priced: today’s 0.60% against 1.14% for all three sessions leaves about 0.69% for each of Thursday and Friday, so today is the cheapest. In our view the market may see the decision as the smaller event, with Thursday holding US growth and inflation data, the European Central Bank and the reaction to tonight’s results from two of the index’s largest companies.
- Correlation read: implied correlation fell for a second session to 13.49 and remains at the 94th percentile of our store. In our view the level, which has held, may matter more than the direction: at that level, a surprise in one large name is more likely to travel across the index.
In our view the two readings furthest from normal this morning, gold volatility at the 6th percentile of its year and implied correlation at the 94th of ours, are not about today. Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply and vary by account and venue; check the rates applicable to you. Past performance is not indicative of future results.
| More from the author |
|---|