
Access both platforms from your single Saxo account.

Rate vol clears, equity vol doesn’t - Options Brief - 17 September 2026
Summary: The Federal Reserve hiked for the first time since 2023, and bond volatility promptly went quiet while equity volatility did the opposite. The question now is which of the two has it right.
The Federal Reserve raised rates for the first time since 2023, and the two halves of the volatility complex went opposite ways. Anything priced off the rate path calmed down once the answer was known. Equity volatility did not.
MARKET REGIME: TRANSITIONING | VIX 17.71 | TERM STRUCTURE: CONTANGO | SKEW: ELEVATED (145.95) | FRONT-MONTH VIX FUTURES: 18.50
- Rate volatility compressed, equity volatility firmed. MOVE fell 3.56% to 80.73 and Treasury fund volatility 7.86%, while the VIX rose 2.97% to 17.71.
- The firming sits behind the front, not at it. VIX1D eased 0.76% to 17.01, while the 30-day measure added 0.51 points, the largest gain anywhere on the cash curve.
- The S&P 500 has spent its whole week in three sessions. It has travelled 103% of the 101.65 point range priced around Friday’s close, with two sessions and a quarterly expiry still to run.
Where the week’s range sits
What the option market priced for this week around Friday’s close, and how much of it the first three sessions used.
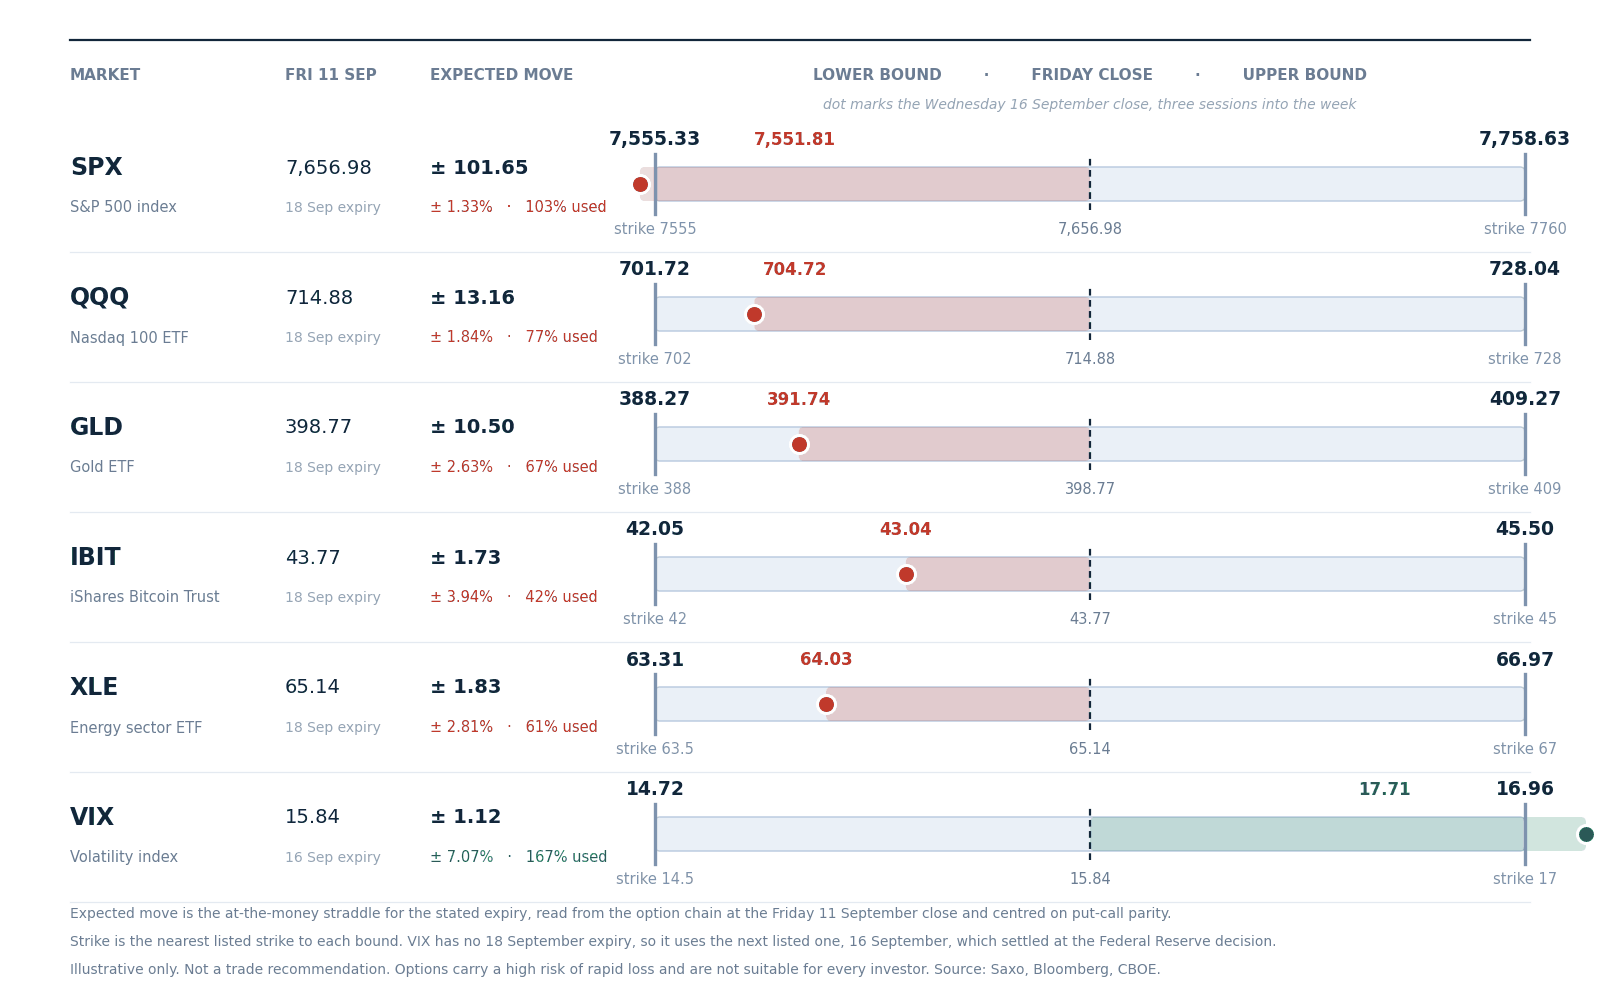 Expected move to the 18 September expiry, drawn around the Friday 11 September close, with the nearest listed strike at each bound. Volatility uses the 16 September expiry, the next one listed, which settled at yesterday’s decision. Read from the option chain at Friday’s close and centred on put-call parity, not a forecast.
- The index has already left its band. The S&P 500 sits 103% of the way through the range priced for the full week, to the downside, with two sessions left. The Nasdaq 100 fund has used 77%, gold 67%, the energy fund 61% and the bitcoin fund 42%, all downward.
- Volatility remains the widest miss. The VIX has covered 167% of the 1.12 point move the chain priced around Friday’s close. In our view a week that spends its equity range before its final two sessions, with the priced event already behind it, is adjusting through the rate path rather than the index level. Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply to exchange-traded fund trades; see Saxo pricing for costs and applicable charges.
Headline driver
The Federal Reserve raised the funds rate by 25 basis points to 3.75% to 4.00%, its first increase in three years, and most officials see at least one more before the year is out. Chair Kevin Warsh called the move a removal of accommodation and said he was hard pressed to describe conditions as restrictive.
The front of the Treasury curve took the message: the 2-year yield rose seven basis points to close near 4.74%, while the 10-year ended two basis points higher, just above 5.00%. The dollar reached a seven-week high. More in Saxo’s macro coverage and today’s Market Quick Take.
Market snapshot
- US (Wednesday 16 September close): S&P 500 7,551.81, down 0.45%. Nasdaq 100 28,945.06, up 0.02%. Dow 51,461.90, down 1.21%. Financials led the decline with Huntington Bancshares off 5.6%, and J.B. Hunt fell 13.3% after warning that diesel costs would weigh on third-quarter profit. Data-centre names held up, Lumentum gaining 9.6% and Coherent 6.9%.
- Europe (Wednesday 16 September close): the Stoxx 600 rose 0.5%, the DAX 0.5% and the FTSE 100 0.3%, helped by softer oil before the decision. Barratt Redrow jumped 11.7% on annual results, and Soitec gained 13.4% on a broker upgrade.
- Asia (Thursday 17 September session): the Nikkei 225 traded around 0.3% higher and the Kospi 0.6%, while the Hang Seng fell about 0.8%. Samsung Electronics added 0.6% and SK Hynix 0.3%.
- Commodities and rates: Brent settled at USD 105.83 and has slipped below USD 106 this morning as Saudi Arabia moves to restore pipeline capacity. Gold trades near USD 4,305 after a session that ran to USD 4,366 and back to USD 4,240. The US 10-year yield is 5.00% and the 2-year 4.72%. EURUSD 1.1460, USDJPY 156.11.
- Market regime: Transitioning, VIX 17.71, with the S&P 500 0.79% below its 50-day moving average and 20-day realised volatility at 8.7%, falling.
Data source: Saxo, Bloomberg, CBOE, as of 17 September 2026, approximately 06:00 CET. Past performance is not indicative of future results.
Options flow sentiment
Based on end-of-day 16 September, yesterday’s positioning and not today’s price action.
- Single-name flow the mega-cap and semiconductor tapes both carried large confirmed-opening totals, and the largest lines on both were deep in the money. The call side skewed long dated, a stock-replacement profile rather than a directional bet, while the put side sat almost entirely in this Friday’s quarterly expiry, where it reads as settlement traffic. In our view the desk was extending horizon in the largest names while letting the near book roll off.
- Sector and ETF flow the index complex carried the day’s size and split close to even, but its two biggest lines were the same deep in-the-money position rolled out of this week’s expiry into December rather than new protection. Gold saw financed upside bought. Energy funds ran as a premium-collection session, every explicitly flagged call sold to open. Rate funds leaned to calls, though the legs arrived paired and at mid, out past 2027. Named funds are market context only. Costs and charges apply to exchange-traded fund trades; see Saxo pricing for costs and applicable charges.
Volatility surface - 17 September 2026, approx. 06:00 CET
VIX term structure
- VIX 17.71, up 2.97%, the largest single gain on the cash curve at 0.51 points.
- VIX1D 17.01, down 0.76%, easing after Tuesday’s spike rather than collapsing as a passed event usually leaves it.
- VIX9D 17.40, up 1.10%.
- VIX3M 19.73 · VIX6M 21.03 · VIX1Y 22.07, contango intact from nine days out to one year.
VIX futures
- Front-month 18.50, a premium of 0.79 points to spot. September settled at yesterday’s expiry, so the front month is now October, where put-call parity returns roughly 18.77 on this morning’s indicative quotes. No session comparison is drawn from the level.
- Second-month 19.07, front-to-second ratio 0.970, curve in contango.
Skew and correlation
- CBOE SKEW 145.95, down 0.66 points, still in the elevated zone.
- COR3M 13.07, up 5.32%, the largest percentage move on the board.
- DSPX 31.99, up 0.57%.
Other vol measures
- VVIX 95.41 · MOVE 80.73, the latter down 3.56%.
- VXN 22.44, up 0.81%, leaving the VXN to VIX ratio at 1.27.
- GVZ 26.55, down 1.30% on a session that moved gold through a 126 dollar range.
Data source: Saxo, Bloomberg, CBOE, as of 17 September 2026, approximately 06:00 CET. Past performance is not indicative of future results.
Single-name volatility - where implied volatility sits against its own year
Saxo’s implied-volatility rank across 193 US and 379 euro-zone option underlyings, read this morning. A rank of 0 is a name’s one-year low, 100 its one-year high.
- Premium is not broadly rich. The typical US name ranks 38, closer to its low than its high, and fewer than one in five names rank above 50. Europe is cheaper, with the typical name at 34 and one in five within a fifth of its one-year low. The cheap end is semiconductors, Nvidia at 10 and Broadcom at 7, on the same tape where yesterday’s flow was extending horizon in the largest names.
- Where it is elevated, it is an energy story, not a market story. Eight of the twenty highest US ranks are energy: Petrobras 84, Diamondback 78, Exxon and Chevron 64, the energy sector fund 66. In our view single-name premium is tracking Brent and the Saudi pipeline headlines, while the index measures above are not being pulled along.
- A high rank does not always mean expensive. Rank measures distance from the year’s extremes, not how many days looked like today. Hyperliquid Strategies ranks 83, yet its implied volatility has been higher than this on five days out of six this year: one spike set the high. The high-yield bond fund is the mirror image, a rank of 39 on a level the fund has exceeded on only one day in seven. Named funds are market context only. Costs and charges apply to exchange-traded fund trades; see Saxo pricing for costs and applicable charges.
Data source: Saxo, as of 17 September 2026, approximately 06:00 CET, reflecting the 16 September close. Day counts are Saxo’s one-year implied-volatility percentile. Past performance is not indicative of future results.
What the market is pricing
- Session implied move. SPX options price a 0.77% move to tonight’s close, about 58 points, with the Bank of England at 13:00 CET and US jobless claims and housing starts at 14:30 CET all landing inside a session that runs to the 22:00 CET cash close. That is narrower than the 0.80% the market charged for the decision itself.
- Event implied range. Friday’s quarterly expiry prices 1.07%, roughly 81 points. Two sessions ago the same expiry priced 1.29%, and one fewer session at unchanged volatility would have left about 80. The market added nothing and took nothing out, after two consecutive nights of paying up.
- Tail risk signal. SKEW at 145.95 has barely moved through the decision while the 30-day measure firmed, so the premium being added is for a general widening rather than for a crash. Stripping today out of Friday leaves the expiry session carrying about 0.74%, close to the range charged for today.
- Correlation read. COR3M rose 5.32% on a session where the Dow fell 1.21% and the Nasdaq 100 finished flat, about as dispersed as a tape gets. In our view implied correlation rising into that dispersion says the market expects the next move to arrive as an index move rather than another rotation.
Options carry a high risk of rapid loss and are not suitable for every investor. Past performance is not indicative of future results.
Today’s catalysts
Canadian Prime Minister Mark Carney addresses the European Parliament at 11:30 CET, with a press conference at 12:30 CET. The Bank of England decides at 13:00 CET, with rates widely expected to stay on hold, and US jobless claims and August housing starts follow at 14:30 CET.
Carnival and Next report. Friday brings the Bank of Japan, where another increase is expected, plus the September quarterly expiry. Future outcomes are uncertain and may result in losses.
Conclusion
The hike was priced and the message was not, which is where the split comes from. Rate volatility fell because the question it was asking has been answered for now. Equity volatility firmed because the answer arrived with projections pointing higher and a chair who declined to call conditions restrictive, moving the uncertainty from the decision to the path.
What the option market is not doing is paying up for it. Friday’s window decayed along the flat-volatility path overnight and today’s range is priced tighter than yesterday’s. The premium sits in the 30-day tenor and in implied correlation rather than in the next two sessions.
In our assessment that leaves an index which has already used its weekly range walking into a quarterly expiry with the event behind it. Whether the last two sessions stay quiet depends less on the Federal Reserve now than on whether the front end of the Treasury curve has finished repricing, and options carry a high risk of rapid loss and are not suitable for every investor. Past performance is not indicative of future results.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it’s crucial to make informed decisions.
| More from the author |
|---|