
Access both platforms from your single Saxo account.

Vol collapses, skew climbs - Options Brief - 14 September 2026
Summary: Every headline volatility measure fell on Friday except one. The skew gauge went the other way, and it did it on the session the market decided Fed week was settled.
MARKET REGIME: LOW VOL BULL | VIX 15.84 | TERM STRUCTURE: CONTANGO | SKEW: ELEVATED (154.49) | FRONT-MONTH VIX FUTURES: 16.66
- The front of the curve emptied out on Friday. The S&P 500 rose 0.86% to 7,656.98 and ended four losing sessions, while the one-day volatility gauge fell 25.66% to 12.98 and the 30-day measure 11.21% to 15.84.
- Fed week got cheaper, not merely closer. The 18 September expiry prices 102 points, or 1.33%, against 141 quoted on Friday morning, where the clock alone would have left roughly 129.
- The tail did not come down with the rest. The skew gauge rose 5.08% to 154.49 and the September volatility future held a 0.82 point premium to spot, against 0.19 a session earlier.
Vol surface data: Saxo, Bloomberg, CBOE, as of 14 September 2026, approx. 06:00 CET. Past performance is not indicative of future results.
Where the week’s range sits
What the option market has priced for this week, before a single session of it has traded.
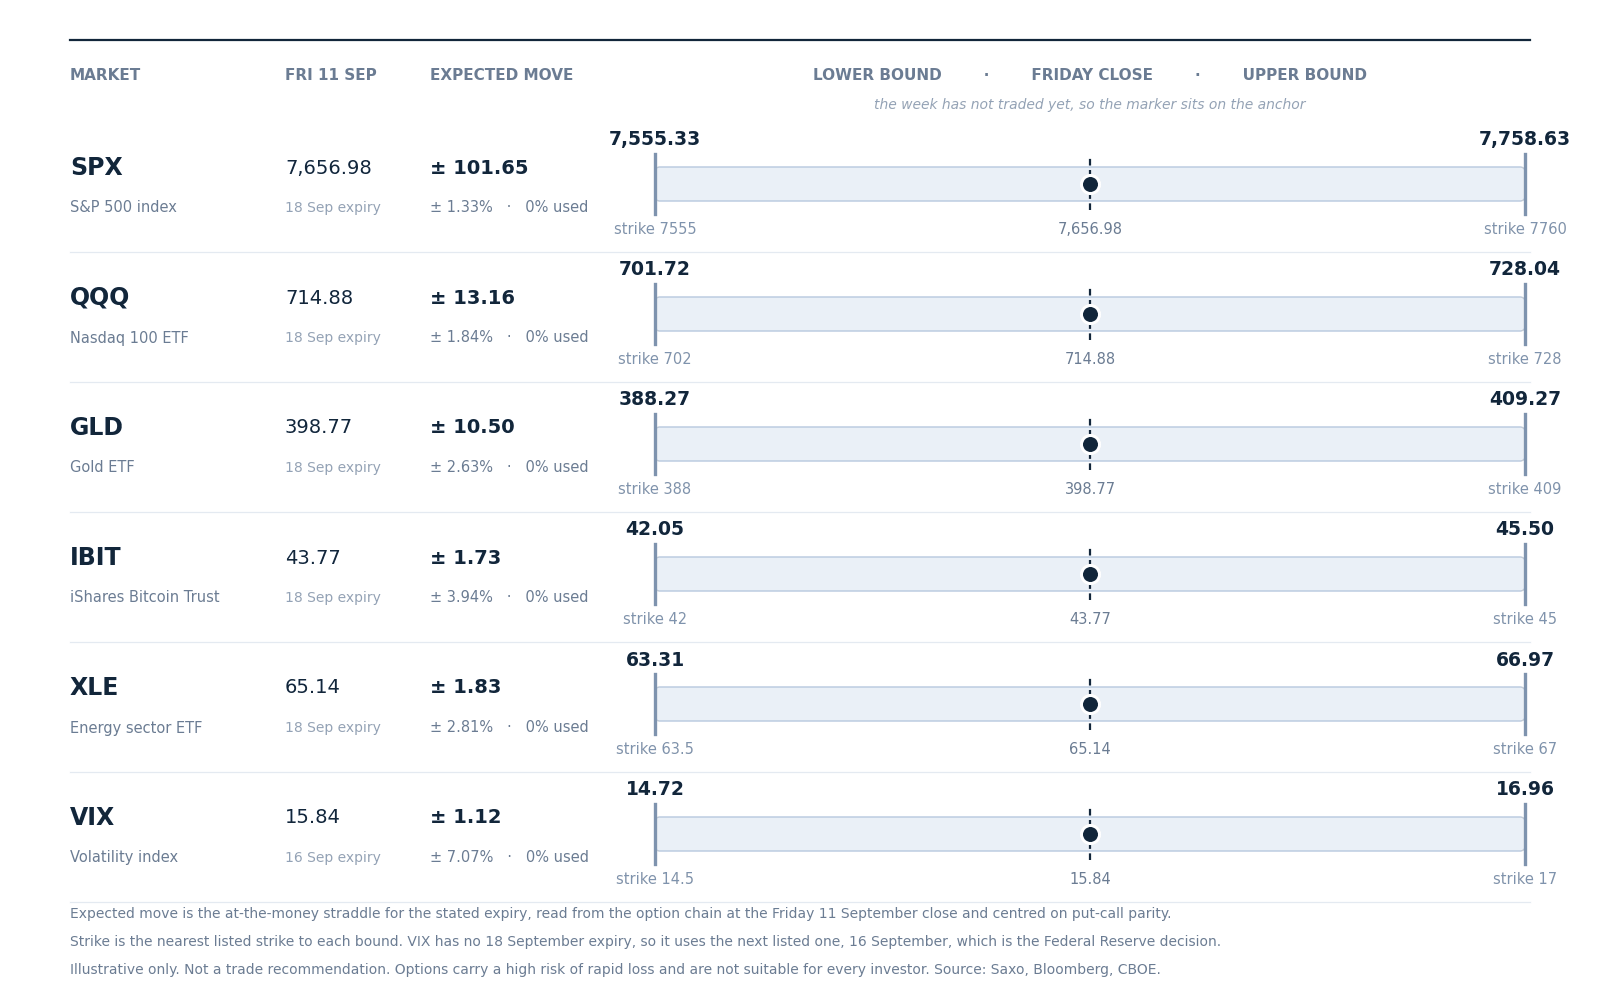 Expected move to the 18 September expiry, drawn around the Friday 11 September close, with the nearest listed strike at each bound. Volatility uses the 16 September expiry, the next one listed. Read from the option chain at Friday’s close and centred on put-call parity, not a forecast.
- The equity bands are narrow and the commodity bands are not. The S&P 500 has 101.65 points, or 1.33%, to work with and the Nasdaq 100 fund 1.84%, against 2.63% for gold, 2.81% for the energy fund and 3.94% for the bitcoin fund. Three rate decisions land inside that window.
- Nothing has been spent yet, which is the point of showing it now. Every marker sits on its anchor because the week opens today. In our view a 1.33% band across a Federal Reserve decision, a Bank of England decision and a Bank of Japan decision may prove thin. Options carry a high risk of rapid loss and are not suitable for every investor. Costs and charges apply to exchange-traded fund trades; see Saxo pricing for costs and applicable charges.
Headline driver
Saudi Arabia shut its East-West crude pipeline after drone attacks, halting a route that carries around 5 million barrels a day past the Strait of Hormuz, with no restart date set and roughly 4% of global supply at risk. US consumer prices rose 0.4% in August for an annual rate of 3.4%, and rate markets now price about an 87% chance of a 25 basis point increase on Wednesday. More in Saxo’s macro coverage and today’s Market Quick Take – Oil up, chips down, Fed ahead, 14 September 2026.
Market snapshot, Friday 11 September 2026 close
- US (Friday 11 September close): S&P 500 7,656.98, up 0.86% and higher for the first time in five sessions. Dow 52,578.27, up 0.98%. Nasdaq 100 29,368.44, up 0.91%. Dell gained 12.0% and Hewlett Packard Enterprise 12.4% after Oracle’s cloud results, with Apple up 1.8%.
- Europe (Friday 11 September close): Stoxx 600 639.10, up 0.49% but 1.7% lower on the week. DAX 25,568.56, up 0.82%, with Infineon 5.0% higher as chip names rebounded.
- Asia (Monday 14 September session): the Kospi fell 3.2% and the Nikkei 225 1.0% as oil and weekend calls to slow artificial intelligence development hit technology. SoftBank lost 12%, SK Hynix around 6% and Samsung Electronics 3.9%.
- Commodities and rates: Brent spiked to USD 108.49 at the Asian open and WTI held above USD 103 by 06:00 CET. Gold trades near USD 4,330 and copper has extended its slide below USD 6.50. The US 2-year yield sits just below 4.63% and the 10-year just below 4.97%. EURUSD 1.1570, USDJPY 154.04.
- Market regime (rules based read): Low Vol Bull, VIX 15.84, with the S&P 500 0.65% above its 50-day moving average and 20-day realised volatility at 8.8% and falling.
Source: Saxo, Bloomberg, CBOE, 14 September 2026, approximately 06:00 CET. Past performance is not indicative of future results.
Options flow sentiment
Based on end-of-day 11 September, yesterday’s positioning and not today’s price action.
- Single-name flow: confirmed-opening premium across the tape reached USD 1.75bn and split 50.6% to puts, about as even as this market gets. Almost every headline line was deep in the money and crossed at mid, including a memory maker’s put ladder printed across four expiries in the same second. That shape is financing and rolling rather than a view. In our view the size says institutions were repositioning, not choosing a side.
- Sector and ETF flow: large-cap technology carried USD 187.4m with 54.8% in calls, and the executions there ran to 2027 and 2028 strikes in matched pairs. Long-dated protection on the broad index was opened in size at the offer, though at that tenor it hedges slowly. Named funds are market context only. Costs and charges apply to exchange-traded fund trades; see Saxo pricing for costs and applicable charges.
Volatility surface – 14 September 2026, approx. 06:00 CET
VIX term structure
- VIX spot 15.84, down 11.21%
- VIX1D 12.98, down 25.66% · VIX9D 14.47, down 18.25%
- VIX3M 18.60 · VIX6M 20.39 · VIX1Y 21.75, a curve that rises steeply from a low front end
VIX futures
- Front-month VIX futures 16.66, a premium to spot of 0.82 points against 0.19 a session earlier. The continuous front-month series reads 18.770, a level belonging to the October contract after the roll, so no session comparison is drawn from it. The September figure comes from put-call parity on the 16 September expiry.
- Second-month VIX futures 18.39 by the same method, leaving the front-to-second ratio at 0.906 and the curve in steep contango
Skew and correlation
- CBOE SKEW 154.49, up 7.47 points, well above the 100 to 120 neutral zone
- COR3M 11.21, down 9.45%, three-month implied correlation back near the low end of its range
- DSPX 30.58, down 3.20%, the S&P 500 dispersion index
Other vol measures
- VVIX 91.28, down 11.09% · MOVE 82.21, up 0.14%
- VXN 21.02, down 9.90%, holding a ratio of 1.33 to the headline gauge
- GVZ 25.68, down 9.83%
Source: Saxo, Bloomberg, CBOE, 14 September 2026. Past performance is not indicative of future results.
What the market is pricing
- Session implied move. Today’s expiry prices 39 points, or 0.51%, derived from at-the-money option pricing rather than a forecast, with no scheduled US release inside the window and the Federal Reserve two sessions away. See Saxo pricing for costs and applicable charges.
- Event implied range. The 18 September expiry carried 141 points on Friday morning and prices 102 now. One session has come off the clock, so flat-volatility decay alone would have left about 129. In our view taking a further 27 points out of a window that spans three central bank decisions may say the market has decided the Wednesday move is settled rather than contested.
- Term-structure read. Spot volatility fell 2.00 points while the September contract fell 1.37, widening the basis to 0.82 points, and the front-to-second ratio sits at 0.906. In our assessment a curve that steepens while its front end collapses appears to price calm now and something less calm from the decision onward.
- Tail risk signal. The skew gauge rose to 154.49 on a session when every headline volatility measure fell, and three-month implied correlation dropped to 11.21. In our view cheap correlation alongside expensive wings may point to a market comfortable that index moves stay small and unwilling to say the same about a gap. Options carry a high risk of rapid loss and are not suitable for every investor.
Options carry a high risk of rapid loss and are not suitable for every investor. Past performance is not indicative of future results.
Today’s catalysts
Canada publishes August consumer prices at 14:30 CET. G20 energy ministers meet in Houston through Wednesday, with the Saudi pipeline outage on the agenda. The Federal Reserve decides on Wednesday, the Bank of England on Thursday and the Bank of Japan on Friday, all inside the 18 September expiry. Future outcomes are uncertain and may result in losses.
Conclusion
In our assessment Friday emptied the near end of the volatility curve and left the wings where they were. The combination of a 0.51% same-day range, a 1.33% range to Friday and a skew gauge above 154 could suggest the option market is pricing a quiet path to Wednesday rather than a quiet week, though a curve this steep can flatten quickly and options carry a high risk of rapid loss that is not suitable for every investor. The week opens with its range drawn and none of it spent. Past performance is not indicative of future results.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it’s crucial to make informed decisions.
| More from the author |
|---|