
You can access both of our platforms from a single Saxo account.

Global Market Quick Take: Asia – June 28, 2024

Key points:
- Equities: US economic data shows signs of slowing, while equities close mixed
- FX: SEK underperforms as Riksbank hints at three more rate cuts this year
- Commodities: Oil extend gains on political risks, supply concerns
- Fixed income: Fed's Foreign RRP Pool Hits New Record High
- Economic data: US PCE, UoM
------------------------------------------------------------------
The Saxo Quick Take is a short, distilled opinion on financial markets with references to key news and events.
Disclaimer: Past performance does not indicate future performance.
In the news:
- Nike stock sinks after company projects larger sales decline than expected in 2025 (Investing)
- Fed's Bostic expects one rate cut in 2024, as many as four in 2025 (Investing)
- US stock futures drift higher; PCE data, Presidential debate in focus (Investing)
- Core inflation in Japan's capital accelerates in June (Investing)
- Nasdaq Rises for 3rd Day Ahead of Inflation Data (Barron’s)
- Tesla Stock Nears $200. Why It’s Make or Break Time (Barron’s)
Macro:
- US Q1 GDP was revised higher to 1.4% from 1.3%, despite expectations that it will be left unchanged. Consumer Spending was revised down to 1.5% while PCE Prices and core were revised fractionally higher to 3.4%, and 3.7%, respectively. However, Q1 data is now stale, and markets are aware that disinflation trends were interrupted. Focus now is on May PCE that is scheduled to be reported today (preview below).
- US jobless claims eased slightly to 233k from 239k, beneath the expected 236k, but remains elevated compared to just a month ago. Signals on the US labor market remain mixed and do not spell any urgent need for rate cuts for now.
- Japan’s Tokyo CPI came in slightly above expectations, especially on the core measures. Headline inflation was at 2.3% YoY for June, as expected and above 2.2% YoY in May. Ex-fresh food inflation jumped higher to 2.1% YoY from 1.9% previously and ex-fresh food and energy rose to 1.8% from 1.7%. This may give room to BOJ to hike rates or reduce bond buying at the July meeting, but it is unlikely to be a respite for the yen.
- US PCE Preview: US core PCE, the Fed’s preferred inflation gauge, is released on Friday. May CPI and PPI suggest that disinflation may be back after being questioned in Q1. Core PCE is expected to soften to 0.1% MoM from 0.2% previously or 2.6% YoY from 2.8% in April. Market expectations are muted but any downside surprise can still bring Fed rate cut expectations forward to September, pushing 2-year yields closer to 4.50%. Any upside surprise, meanwhile, can take Treasury yields and US dollar higher.
Macro events: German Unemployment (Jun), US PCE (May), US University of Michigan Final (Jun)
Earnings: N/A
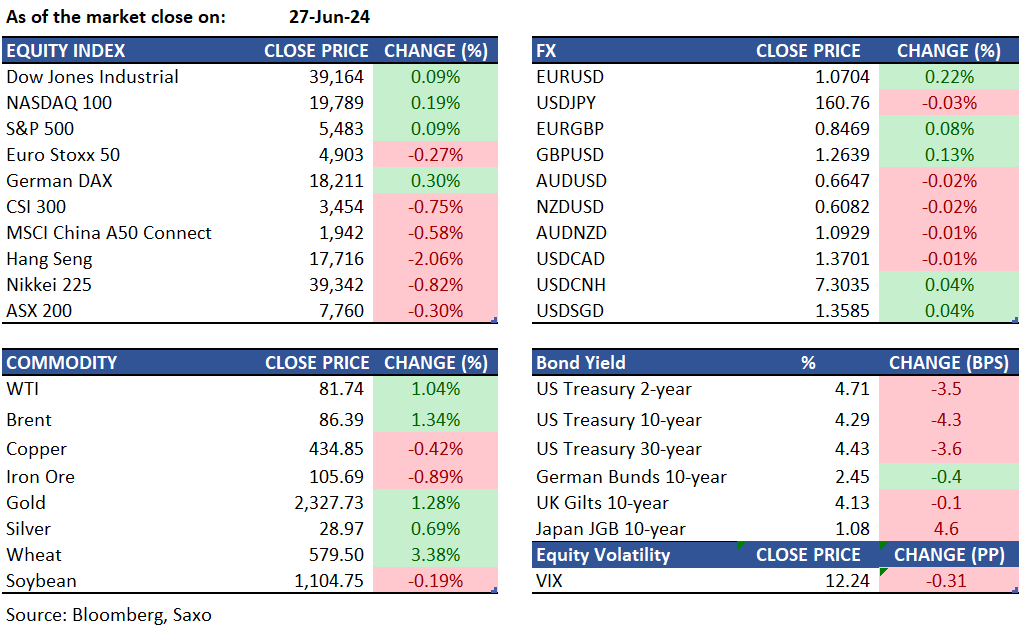
Equities: U.S. equities concluded the session mixed, with the Russell 2000 gaining 1% and outperforming due to a decline in Treasury yields, ahead of tomorrow’s crucial PCE inflation data. The Nasdaq remained strong, driven by a dynamic rotation among tech leaders. After a substantial rally, NVDA has cooled off, while AAPL led over the past two weeks. Recently, AMZN, TSLA, and GOOGL have taken the lead, sustaining the Nasdaq's upward momentum.Gross domestic product (GDP) grew at a revised annualized rate of 1.4% for Q1, although this marks a slowdown from the 3.4% rate observed in Q4 2023. In addition, U.S. data is showing some signs of slowing, with core capital goods orders falling by 0.6% in May, the goods trade deficit expanding by 2.7%, and retail inventories rising.
Fixed income: Foreign central bank usage of a key Federal Reserve facility surged to a new record high, signaling that policymakers globally are continuing to bolster their cash reserves. The yield on 10-year Treasury note declined 4 basis points to 4.29% on Thursday, as data suggested that the Fed’s tight monetary policy is hampering growth. Australian bonds rose in tandem with Treasuries after Reserve Bank Deputy Governor Andrew Hauser downplayed a hotter-than-expected May inflation report. Treasury bond futures remained steady ahead of key U.S. inflation data due on Friday. Australia’s 3-year note yield dropped 8 basis points to 4.09%, while the 10-year debt yield fell 7 basis points to 4.34%. A seven-year note auction produced a yield below the when-issued level. Futures of Japanese 10-year government notes ended the overnight session 17 ticks higher at 142.85, signaling a yield decline of nearly 2 basis points. Japan’s benchmark yield rose 4 basis points to 1.070% on Thursday.
Commodities: Gold rebounded to above $2,300 per ounce on Thursday after hitting a nearly three-month low. Markets reacted to key data suggesting the Federal Reserve may cut rates in September, making gold more attractive. Lower global interest rates also supported precious metals. Brent crude rose to $86.3 per barrel, nearing a two-month high, as Middle East supply concerns outweighed a surprise increase in US stockpiles. Iron ore prices with 62% iron content rose slightly to $106.56 per tonne in late June after Beijing relaxed homebuying curbs, potentially boosting the property market and steel demand for housing construction.
FX: The US dollar ended the day marginally lower ahead of Friday’s core PCE, but immediate focus is on the Biden/Trump debate which is set to begin at 2100 ET. EURUSD took over 1.07 again, with ECB rate cuts hinting that market expectations of about two rate cuts this year seem to be about right. Weekend French elections in focus, and volatility is likely to pick up. Japanese yen remained pegged near recent lows despite intervention threats, with USDJPY at 160.70, AUDJPY testing a break above 107, and GBPJPY rising to 203.40. Swedish krona underperformed as Riksbank signaled three more rate cuts for this year despite other major central banks turning more cautious about further rate cuts this year. USDSEK rose above 200-day moving average at 10.59.
For all macro, earnings, and dividend events check Saxo’s calendar.
For a global look at markets – go to Inspiration.