
You can access both of our platforms from a single Saxo account.

Global Market Quick Take: Asia – October 28, 2024

Key points:
- Macro: Japan’s ruling coalition loses its majority
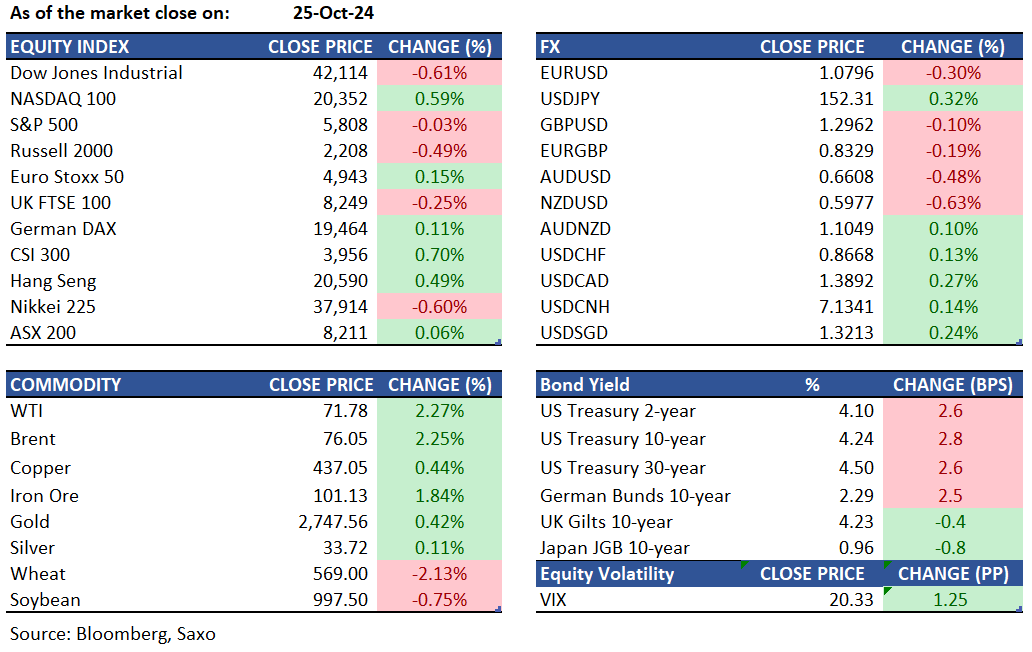
- Equities: US tech firms gained ahead of earnings this week. Nasdaq 100 up 0.59%
- FX: JPY leads losses amid political instability concerns
- Commodities: Oil fell over 4% after Israel’s strikes on Iran avoided key energy sites
- Fixed income: The 2-year yield rose above 4.10%
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Final US University of Michigan survey for October was revised higher to 70.5 from 68.9, above the expected 69.0, with Expectations and Conditions also revised upwards to 74.1 (prev. 72.9) and 64.9 (prev. 62.7), respectively. In terms of inflation expectations, 1yr declined to 2.7% from 2.9%, and 5yr was left unchanged at 3.0%. The report builds further the narrative of US economy staying resilient.
- The ruling LDP coalition lost its majority in Japan elections for the first time since 2009. Voter discontent over a slush-fund scandal pummelled support for PM Shigeru Ishiba’s party, which may seek partners in a bid to form a government. Political instability could take a toll on Japanese assets and Bank of Japan’s policy decision is due this week on Thursday.
- Geopolitical risks have escalated with Israel striking military targets across Iran after weeks of speculation. The scale of attacks looked to be measured with limited damage and there was a sense of relief that oil facilities were unscathed, but focus turns to any further risks of a retaliation.
- The decline in China’s industrial profits accelerated in September to -27.1% YoY from -17.8% YoY previously. YTD profits slumped 3.5% YoY as deflationary pressures weighed on corporate finances. Stocks could find support from the government’s buyback program, but caution on the effectiveness of stimulus measures in increasing and focus now turns to the NPC standing committee meeting scheduled from Nov 4 to Nov 8.
Equities:
- US - Nasdaq 100 closed 0.59% higher on Friday as major tech companies like Apple, Meta and Amazon gained ahead of their earnings this week. Banks underperformed as New York Community Bancorp fell 8% after issuing poor guidance and missing Q3 earnings estimates. Bank of America and Wells Fargo saw declines of 1.7% and 1.3% while Morgan Stanley and Goldman Sachs fell by 2%.
- Japan - Nikkei 225 futures mixed on Monday after the ruling Liberal Democratic Party lost its majority in the lower house behind Sunday's elections.
- Hong Kong - HSI rose 0.5% on Friday, boosted by gains in Chinese markets and anticipation of China's legislature session on November 4-8. Speculation grew about Beijing advancing its 2025 bond quota. The PBoC kept the lending rate at 2%. Auto and pharma stocks saw strong gains.
- Europe - DAX rose 0.1% to 19,464 on Friday amid cautious European markets. Mercedes-Benz shares fell 1% after disappointing results and halved net profit. VW, BMW, and Continental also faced declines.
- Earnings – Philips, Ford, ON Semiconductor, Cadence Design, Waste Management
FX:
- USD ended the week higher, with JPY leading the drop as US yields pushed higher on the back of resilient US economy and rising odds of a Republican sweep in the US elections.
- JPY weakness continued to extend into early Asian hours as Japanese election results highlighted risks of political instability. USDJPY was volatile as it traded close to 153, and risk-reward remains skewed to the upside in the run up to the US elections next week as Bank of Japan decision this week could signal delays to further normalization.
- AUD and NZD also ended the week lower amid US dollar strength and potential risks from the Trump trade given higher tariff risks could weigh on commodity currencies. CAD has been more resilient in the commodity currency space despite a 50bps rate cut from the Bank of Canada last week.
- EURUSD remains stuck around 1.08 with odds of a 50bps rate cut from the ECB in December on the rise. GBPUSD capped below 1.30 as the UK’s labour party is set to deliver its first budget in 15 years on Oct 30.
Commodities:
- Oil futures rose 2% on Friday but fell over 4% to below $69 on Monday after Israel's strikes on Iran avoided key energy sites, easing supply disruption fears.
- Gold rose to above $2,740, recovering from earlier profit-taking as Middle East tensions and US election uncertainties boosted safe-haven demand.
Fixed income:
- The 2-year yield exceeded 4.10% for the first time since mid-August, influenced by strong September durable goods orders. Late front-end underperformance aligns with a tight auction schedule, including doubled 2- and 5-year note auctions on Monday. Yields increased by 3-4 basis points, with the curve slightly steeper.
For a global look at markets – go to Inspiration.