Quick Take Asia

Global Market Quick Take: Asia – April 30, 2025

SaxoStrats 6 minutes to read

Key points:  

  • Macro: Trump expected to sign 3 orders to reduce tariffs on autos 
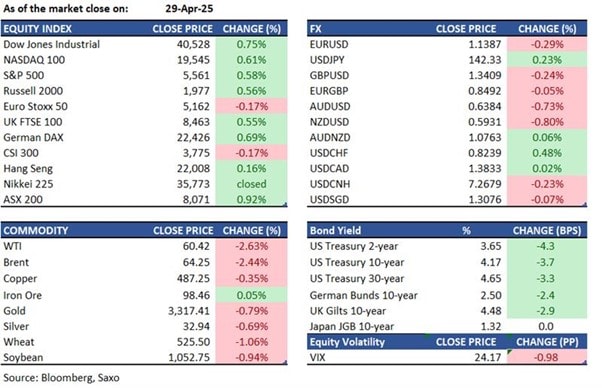
  • Equities:  S&P 500 is up 0.58%, its 6 consecutive rise.  
  • FX: Aussie and Kiwi were the weakest against the dollar 
  • Commodities: Oil fell again, staying near a three-week low 
  • Fixed income: 10-year Treasury yield has declined for six consecutive sessions 

------------------------------------------------------------------  
qt 2903

Disclaimer: Past performance does not indicate future performance.  

 Macro:  

  • Trump will sign three orders today to reduce tariffs on auto manufacturing, offering rebates for US-made cars and exempting imported parts from steel and aluminum tariffs. This announcement is expected to please the domestic auto industry. 
  • In March 2025, Japan's retail sales increased by 3.1% year-on-year, below the expected 3.5% and down from February's 1.3% growth. This marked the 36th consecutive month of expansion, but the slowest since last October. Monthly sales dropped 1.2%. 
  • The US goods trade deficit hit a record $162 billion in March 2025, above the expected $146 billion, as firms increased imports due to tariff threats. Imports grew 5% monthly and 30.8% annually to $342.7 billion, led by consumer goods, industrial supplies, and capital goods. 

Equities:  

  • US - US stocks rose on Tuesday, driven by news of a nearing trade deal and strong corporate earnings. The S&P 500 gained 0.58%, marking its sixth consecutive rise, the longest since November. The Dow Jones increased by 300 points (0.75%), its best streak since July, and the Nasdaq rose 0.55%. Honeywell (+5.4%) and Sherwin-Williams (+4.9%) led the Dow with strong quarterly results. General Motors dropped 1.1% after cancelling its share buyback and outlook due to tariff concerns, while Amazon remained stable after clarifying it wouldn't display tariff charges. UPS fell 0.5% despite better-than-expected earnings and plans to cut 20,000 jobs. The U.S. trade deficit in goods hit a record high, consumer confidence declined, and job openings in March were 7.19 million, below expectations.
  • EU - The Stoxx 50 declined by 0.5% on Tuesday, driven by Schneider Electric's 6.6% drop after missing revenue estimates and reducing its profit margin outlook. Luxury and retail stocks also contributed, with LVMH down 2% and Inditex falling 3.7%. Adidas fell nearly 3% despite strong profits, warning of potential price hikes due to US tariffs. Conversely, the Stoxx 600 rose 0.4%, continuing its six-session winning streak. HSBC exceeded expectations and announced a $3 billion buyback, while Deutsche Bank impressed with a 39% profit increase. BP fell after a 49% drop in Q1 profit from weaker oil prices. The autos sector struggled, with Volvo Cars down 1.2% after suspending guidance, and Porsche dropping 4.2% after lowering forecasts due to US tariffs.
  • HK - The Hang Seng rose by 36 points (0.2%) to close at 22,008 on Tuesday, driven by gains in tech and financials following a subdued session. During the Politburo meeting, Beijing refrained from new stimulus but reiterated support for exporters and workers affected by tariffs, with contingency plans in place. Mainland markets will close from May 1 for a 5-day Labour Day break. Auto stocks rose, with Geely up 3.7% and Li Auto 2.2%, as President Trump plans to ease duties on foreign auto parts. Wuxi AppTec surged 4% on strong Q1 profits. Other gainers included Sichuan Kelun-Biotech (9.5%), Alibaba Health (6.5%), Trip.com (2.9%), and Meituan (2.8%). Sinopec fell 1.4% after weaker quarterly earnings.

Earnings this week: 
Wednesday: Microsoft, Meta, Robinhood, Qualcomm, eBay
Thursday: Apple, Amazon, Block, CVS, Mastercard, Hershey
Friday: Exxon, Chevron 

FX: 

  • The dollar strengthened against all G10 currencies following reports of eased auto tariffs by the Trump administration. The euro dropped as inflation expectations neared a one-year high. The Bloomberg Dollar Spot Index rose 0.2% after a 0.5% decline on Monday.
  • USDCAD increased by 0.1% to 1.3844 after Canada's Liberal Party's narrow election win, with the loonie leading G10 currencies against the dollar.
  • EURUSD fell 0.3% to 1.1384, and USDJPY rose 0.2% to 142.28.
  • GBPUSD dropped 0.3% to 1.3404. AUDUSD declined 0.7% to 0.6388, and NZDUSD fell 0.6% to 0.5942, as China advised against yielding to US tariff threats. The Aussie and Kiwi were the worst performers against the dollar.
  • Economic data: Australia March/1Q CPI, March Private Sector Credit, China April Manufacturing, Composite PMIs, China Caixin April Manufacturing PMI, Eurozone GDP, France GDP, CPI, PPI, Germany CPI, GDP, unemployment, US GDP, PCE price index, employment cost index, ADP employment

Commodities: 

  • Oil remained near a three-week low after a 2% drop, as trade war concerns and rising US stockpiles affected prices. WTI was around $60, and Brent below $65. Upcoming data may confirm a US economic slowdown, with consumer confidence at a five-year low.
  • China's copper market gauge reached its highest since late 2023 as buyers scramble for supplies. The Yangshan premium rose from $35 a ton in late February to $94 on Tuesday, per Shanghai Metals Market data.
  • Gold fell as expectations rose that Trump would soften auto tariffs, reducing haven demand. Bullion dropped 1.3% to $3,299.76 an ounce, after a 0.7% gain previously.

Fixed income:  

  • Treasuries rose after disappointing March JOLTS and April consumer confidence data, maintaining gains. Trading featured a significant block flattener with 2-year and ultra 10-year contracts. Treasuries are set for a fourth month of gains as tariffs hint at economic weakening, while a major trader bets $18 million that the Fed won't cut rates this year.

For a global look at markets – go to Inspiration.  

Disclaimer

Confidentiality and Usage:
You may not reproduce, distribute, or transmit this material or any portion thereof without prior written permission from Saxo.

Nature of Information:
The information provided herein is based on current market conditions and analysts' opinions, which may reflect personal views of the author, and are subject to change without notice. This material does not include a record of any trading prices, or an offer of, or solicitation for, or endorsement to enter into any transaction in any investment product. Any forecast on the economy, markets and economic trends of the markets provided is not necessarily indicative of the future or likely performance of the investment product subject of this material.

Responsibility and Liability:
Saxo accepts no liability for any use that may be made of these comments or for any consequences that arise from such use. Saxo does not guarantee the accuracy or completeness of any information provided and assumes no liability for any errors, omissions, losses, or damages resulting from the use of this information.

The information provided in this material is solely for information only. It is intended for general circulation and does not take into account the specific investment objectives, financial situation or particular needs of any particular person. Accordingly, it should not be relied on or treated as a substitute for specific advice concerning specific situations of any person. Please seek advice from a financial adviser regarding the suitability of any investment product taking into account your specific investment objectives, financial situation or particular needs before you make a commitment to purchase an investment product. In the event that you choose not to seek advice from a financial adviser, you should consider whether any investment product mentioned in this publication is suitable for you.

Notwithstanding the above, insofar as any information provided herein contains research analyses or reports concerning any investment product authored by any foreign research house and is issued or promulgated to a person in Singapore who is not an accredited investor, expert investor, and/or institutional investor, Saxo Capital Market Pte. Ltd. accepts legal responsibility for the contents of this material to the extent required by law. Recipients of such material are to contact Saxo Capital Markets Pte. Ltd. in respect of any matters arising from, or in connection with, this material.

Risk Disclosure:
Trading in investment products involve significant risk, including the risk of losing your entire investment. Historical returns are not a guarantee of future returns. Prices can both rise and fall, and there is a risk that you will not get back the money you invested.

Conflicts of interest:
The author may hold positions in the investment products mentioned. The author does not own positions in the underlying investment product exceeding 0.5% of its market capitalisation, save as otherwise declared. The author is not permitted to trade the mentioned investment products within the first 24 hours after the publication of this article.

Saxo maintains partnerships with companies that compensate Saxo for promotional activities conducted on its platform. Additionally, Saxo has agreements with certain partners who provide retrocession contingent upon clients purchasing specific investment products offered by these partners. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.

Publication details:
If any listed companies are the subject of the material, the content has not been submitted to the companies in question prior to publication.

Please refer to our full disclaimer and notification on non-independent investment research for more details.

Saxo Markets
88 Market Street
CapitaSpring #31-01
Singapore 048948

Contact Saxo

Singapore
Singapore

Saxo Capital Markets Pte Ltd ('Saxo Markets') is a company authorised and regulated by the Monetary Authority of Singapore (MAS) [Co. Reg. No.: 200601141M ] and is a wholly owned subsidiary of Saxo Bank A/S, headquartered in Denmark. Please refer to our General Business Terms & Risk Warning to consider whether acquiring or continuing to hold financial products is suitable for you, prior to opening an account and investing in a financial product.

Saxo is part of the J. Safra Sarasin Group.

Trading in financial instruments carries various risks, and is not suitable for all investors. Please seek expert advice, and always ensure that you fully understand these risks before trading. Trading in leveraged products such as Margin FX products may result in your losses exceeding your initial deposits. Saxo Markets does not provide financial advice, any information available on this website is ‘general’ in nature and for informational purposes only. Saxo Markets does not take into account an individual’s needs, objectives or financial situation.

The Saxo trading platform has received numerous awards and recognition. For details of these awards and information on awards visit www.home.saxo/en-sg/about-us/awards.

The information or the products and services referred to on this website may be accessed worldwide, however is only intended for distribution to and use by recipients located in countries where such use does not constitute a violation of applicable legislation or regulations. Products and Services offered on this website are not intended for residents of the United States, Malaysia and Japan. Please click here to view our full disclaimer.

This advertisement has not been reviewed by the Monetary Authority of Singapore.

Apple and the Apple logo are trademarks of Apple Inc, registered in the US and other countries and regions. App Store is a service mark of Apple Inc. Google Play and the Google Play logo are trademarks of Google LLC.