
Access all our platforms from a single account.

Global Market Quick Take: Asia – May 09, 2025

Key points:
- Macro: UK-US deal: 10% tariff, USD 10B Boeing purchase, Rolls Royce exports free
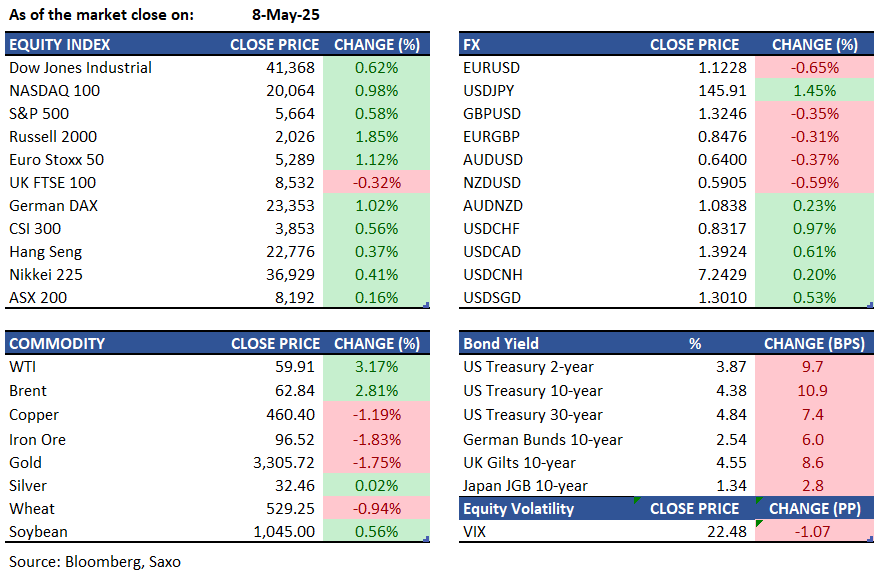
- Equities: Trump says to buy stocks now. S&P 500 up 0.6%, Nasdaq 100 up 1.1%
- FX: The US-UK trade deal lifted the pound; yen lagged
- Commodities: Gold dropped for two consecutive days due to dollar strength
- Fixed income: Yields were cheaper lead by front and belly of the curve
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- The UK-US trade deal keeps a 10% UK tariff rate. The UK will buy USD 10 billion in Boeing planes, and Rolls Royce can export parts tariff-free. The deal aims to boost revenue and export opportunities. Trump is optimistic about China tariff talks.
- Nonfarm labour productivity fell by 0.8% in Q1, and labour costs rose by 5.7%. Oxford Economics attributes the productivity drop to unusual factors, not a trend shift, and the rise in costs doesn't signal faster wage growth.
- Jobless claims fell to 228,000, below expectations, with continued claims at 1.879 million. Claims are stable despite tariffs, with last week's rise due to NY school spring break. Labour market trends may be clearer by July's FOMC meeting, making June easing unlikely.
Equities:
- US - The S&P 500 rose 0.6%, Nasdaq jumped 1.1%, and Dow gained 255 points, driven by trade optimism and easing geopolitical tensions. Trump called the UK deal a breakthrough for boosting American exports, though a 10% tariff remains. He suggested potential tariff reductions on China, contingent on trade talks in Switzerland this weekend. Tech shares rose sharply, with Tesla up 3.1% and Palantir soaring 7.8%. Apple and Alphabet also gained, partially recovering from previous losses. Arm fell 6.2% after issuing pessimistic guidance, and Eli Lilly dropped 3.2% amid widespread healthcare sector losses in Europe and North America. In after hours, Coinbase fell 2.6% after missing revenue estimates and net income falling 94% due to marking their crypto holdings to market.
- EU - European stocks closed higher on Thursday, with gains across most sectors as markets evaluated trade and monetary policy developments. The STOXX 50 rose 1.1%, while the STOXX 600 increased by 0.4%, tempered by losses in the pharmaceutical sector. The US-UK trade deal maintained a 10% tariff on UK goods, and the EU threatened tariffs on US goods if negotiations falter. The Riksbank and Norges Bank held rates steady, while the BoE cut rates. Tech and financials led STOXX 50 gains, with ASML, UniCredit, Santander, and Intesa Sanpaolo rising over 3%. AB InBev climbed 3.2% following strong results. Conversely, Mercedes Benz fell 6% due to dividend cuts amid economic uncertainty, and Novo Nordisk dropped 4% after lowering guidance on an obesity drug.
- HK – Hang Seng Index rose 0.8% to 22,881, extending gains for six sessions. The increase follows the Fed and HKMA maintaining rates, and optimism over Trump's trade deal announcement. China's PBoC introduced policy measures, including rate cuts, to support growth. Gains led by consumer and tech stocks, with financials lagging. Concerns over Beijing's fiscal measures and upcoming Chinese economic data capped upside.
Earnings this week:
Friday: Terawulf, 1stDibs, Enbridge, ANI Pharmaceuticals, Telos, OCBC
FX:
- The dollar strengthened broadly as Trump signalled openness to reducing China tariffs. The US-UK trade deal supported the pound, while the yen lagged in the G10. The Bloomberg Dollar Spot Index rose 0.7%, its biggest jump since April.
- USDJPY rallied 1.6% to 146.18 amid dollar moves.
- GBPUSD fell 0.4% to 1.3243 after the BOE cut rates to 4.25% due to trade war concerns.
- EURUSD dropped 0.7% to 1.1221. The EU plans €95 billion in tariffs on US exports if talks fail.
- USDCHF jumped 1% to 0.8320, while Riksbank and Norges Bank kept rates unchanged, signalling possible future cuts.
- AUDUSD steadied at 0.6396, possibly ending a four-week rally below the 200-DMA. NZDUSD was stable at 0.5905, facing a second weekly decline, with resistance at 0.6038 indicating April's range may extend into May.
- Economic data: China - April Trade, 1Q Current Account Balance, April Money Supply, Aggregate Financing, New Yuan Loans, Canada – April employment
Commodities:
- Oil rose further as focus shifted to upcoming US-China trade talks following Trump's UK agreement announcement. WTI surpassed $60 after a 3.2% gain; Brent closed near $63. Trump predicted progress in China talks, though Beijing urged the US to cancel tariffs first.
- Gold fell as the dollar strengthened following Trump's US-UK trade framework announcement, reducing haven demand amid global trade war concerns.
Fixed income:
- Treasuries bear flattened as risk-on sentiment grew and traders reduced Fed easing expectations. President Trump announced a UK trade deal, boosting stocks and front-end yields. He suggested China tariffs might lower with successful talks. A weak 30-year bond auction pressured Treasuries, with yields closing near daily highs.
For a global look at markets – go to Inspiration.