Quick Take Asia

Global Market Quick Take: Asia – January 31, 2025

Macro 6 minutes to read

Key points:

  • Macro: Trump renews commitment to impose tariffs and Canada and Mexico
  • Equities: Stocks continue to rise despite mixed earnings
  • FX: The US dollar strengthens against CAD and MXN
  • Commodities: Gold hits a record high as a safe haven
  • Fixed income: Treasuries trim gains due to tariff concerns

------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.


Macro:

  • President Donald Trump's renewed commitment to impose 25% tariffs on imports from Canada and Mexico starting February 1st caused a stir in foreign exchange markets late in the New York trading session.
  • The US economy grew 2.3% in Q4, below the 2.6% forecast, with strong consumer spending. PCE prices and jobless claims were better than expected. The Fed held rates steady, noting economic strength. The ECB cut rates by 25bps and suggested more cuts.

Equities: 

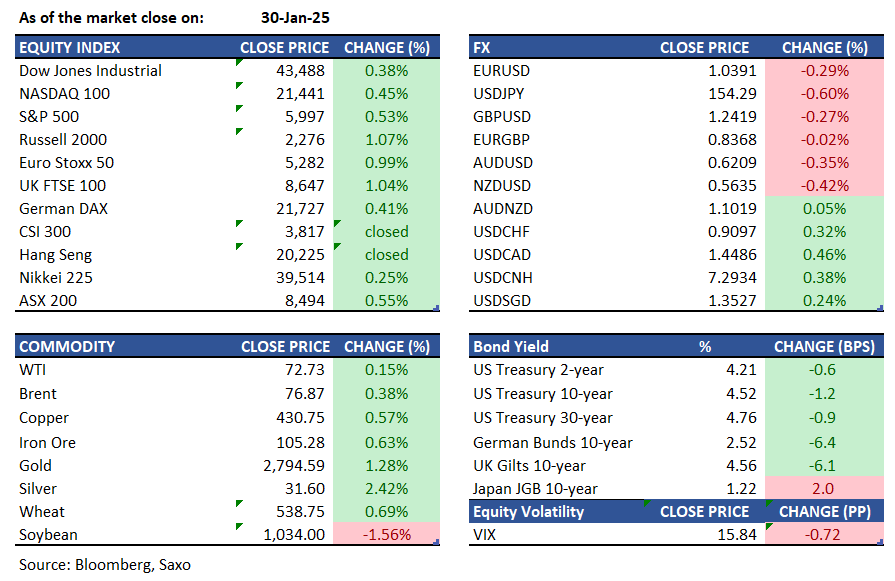
  • US - US stocks rose on Thursday despite mixed earnings. The Nasdaq and Dow Jones increased by 0.5%, and the S&P 500 by 0.6%. Meta and Tesla saw gains, while Microsoft dropped over 6.2% due to a disappointing revenue forecast. Oracle and Broadcom rebounded from earlier losses. US GDP grew by 2.3% in Q4, below expectations.
  • Japan - Nikkei 225 rose 0.25% to 39,514, and the Topix Index gained 0.23% to 2,782, marking a second day of gains. Chip-related stocks led the rally, with Advantest up 3.2% after boosting its profit forecast by 37% due to AI chip demand. Disco, Tokyo Electron, and Hitachi also gained. Bank of Japan's Deputy Governor hinted at possible rate hikes if economic conditions align.
  • Germany - DAX rose to a record 21,731 on Thursday after the ECB cut the deposit rate by 25bps and hinted at more cuts. The Fed paused monetary easing, adopting a cautious stance. The Eurozone economy stagnated last quarter, with contractions in Germany and France. Deutsche Bank fell over 4% due to a larger-than-expected Q4 profit drop from legal provisions.
  • Australia - ASX 200 rose 0.55% to 8,494, reaching record highs due to cooling inflation, prompting expectations of an RBA rate cut in February. Shares gained despite Wall Street's decline after the Fed paused its rate cuts, citing "somewhat elevated" inflation.

FX:

  • The dollar index reached a session high after U.S. President Donald Trump confirmed plans to implement 25% tariffs on Canada and Mexico this Saturday. As a result, the Canadian dollar fell by more than 1%, with USDCAD climbing as much as 1.2% to 1.4595 before retreating.
  • EURUSD slipped 0.1% to 1.0407, after having risen up to 0.4% earlier. ECB President Christine Lagarde stated that the decision to cut rates by 25 basis points was unanimous, easing worries that some policymakers might favor a larger cut.
  • USDJPY dropped 0.6% to 154.25, following the Bank of Japan’s significant move last week to reduce its massive balance sheet, underscoring Governor Kazuo Ueda’s intent to steadily move toward policy normalization.
  • Furthermore, GBPUSD edged down 0.1% to 1.2434, while USDCHF rose 0.3% to 0.9093.

Commodities:

  • Oil prices are climbing as Trump plans tariffs on Canada and Mexico, possibly exempting crude. He has threatened 25% tariffs on imports from these countries and China, with a decision on crude exemptions expected soon. Canada exports 4 million barrels of oil daily to the U.S., and these tariffs could cause refiners to cut production.
  • Gold reaches a new peak as investors seek refuge in safe-haven assets amid Trump's tariff threats. The metal benefits from rising demand driven by apprehensions about trade wars and economic growth. Gold is poised for its fifth straight weekly gain, with spot gold edging up 0.1% to $2,797.82 per ounce.

Fixed income:

  • Treasuries closed with slight changes, having retreated from earlier highs as small gains faded late in the session following President Trump's threats of 25% tariffs on Canada and Mexico, which strengthened the dollar. Trading was earlier influenced by the FOMC's statements from Wednesday, euro-zone bond gains post-ECB policy announcement, and a surprising drop in U.S. initial jobless claims. Treasury yields were nearly unchanged, having bounced back from earlier declines to year-to-date lows, with the 10-year yield at 4.52%, trailing bunds and gilts by about 5 basis points. European rate movements, driven by the ECB's actions, had a notable impact on Treasuries, as euro-zone markets anticipated further ECB easing this year.


For a global look at markets – go to Inspiration.


Disclaimer

Confidentiality and Usage:
You may not reproduce, distribute, or transmit this material or any portion thereof without prior written permission from Saxo.

Nature of Information:
The information provided herein is based on current market conditions and analysts' opinions, which may reflect personal views of the author, and are subject to change without notice. This material does not include a record of any trading prices, or an offer of, or solicitation for, or endorsement to enter into any transaction in any investment product. Any forecast on the economy, markets and economic trends of the markets provided is not necessarily indicative of the future or likely performance of the investment product subject of this material.

Responsibility and Liability:
Saxo accepts no liability for any use that may be made of these comments or for any consequences that arise from such use. Saxo does not guarantee the accuracy or completeness of any information provided and assumes no liability for any errors, omissions, losses, or damages resulting from the use of this information.

The information provided in this material is solely for information only. It is intended for general circulation and does not take into account the specific investment objectives, financial situation or particular needs of any particular person. Accordingly, it should not be relied on or treated as a substitute for specific advice concerning specific situations of any person. Please seek advice from a financial adviser regarding the suitability of any investment product taking into account your specific investment objectives, financial situation or particular needs before you make a commitment to purchase an investment product. In the event that you choose not to seek advice from a financial adviser, you should consider whether any investment product mentioned in this publication is suitable for you.

Notwithstanding the above, insofar as any information provided herein contains research analyses or reports concerning any investment product authored by any foreign research house and is issued or promulgated to a person in Singapore who is not an accredited investor, expert investor, and/or institutional investor, Saxo Capital Market Pte. Ltd. accepts legal responsibility for the contents of this material to the extent required by law. Recipients of such material are to contact Saxo Capital Markets Pte. Ltd. in respect of any matters arising from, or in connection with, this material.

Risk Disclosure:
Trading in investment products involve significant risk, including the risk of losing your entire investment. Historical returns are not a guarantee of future returns. Prices can both rise and fall, and there is a risk that you will not get back the money you invested.

Conflicts of interest:
The author may hold positions in the investment products mentioned. The author does not own positions in the underlying investment product exceeding 0.5% of its market capitalisation, save as otherwise declared. The author is not permitted to trade the mentioned investment products within the first 24 hours after the publication of this article.

Saxo maintains partnerships with companies that compensate Saxo for promotional activities conducted on its platform. Additionally, Saxo has agreements with certain partners who provide retrocession contingent upon clients purchasing specific investment products offered by these partners. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.

Publication details:
If any listed companies are the subject of the material, the content has not been submitted to the companies in question prior to publication.

Please refer to our full disclaimer and notification on non-independent investment research for more details.

Saxo Markets
88 Market Street
CapitaSpring #31-01
Singapore 048948

Contact Saxo

Singapore
Singapore

Saxo Capital Markets Pte Ltd ('Saxo Markets') is a company authorised and regulated by the Monetary Authority of Singapore (MAS) [Co. Reg. No.: 200601141M ] and is a wholly owned subsidiary of Saxo Bank A/S, headquartered in Denmark. Please refer to our General Business Terms & Risk Warning to consider whether acquiring or continuing to hold financial products is suitable for you, prior to opening an account and investing in a financial product.

Saxo is part of the J. Safra Sarasin Group.

Trading in financial instruments carries various risks, and is not suitable for all investors. Please seek expert advice, and always ensure that you fully understand these risks before trading. Trading in leveraged products such as Margin FX products may result in your losses exceeding your initial deposits. Saxo Markets does not provide financial advice, any information available on this website is ‘general’ in nature and for informational purposes only. Saxo Markets does not take into account an individual’s needs, objectives or financial situation.

The Saxo trading platform has received numerous awards and recognition. For details of these awards and information on awards visit www.home.saxo/en-sg/about-us/awards.

The information or the products and services referred to on this website may be accessed worldwide, however is only intended for distribution to and use by recipients located in countries where such use does not constitute a violation of applicable legislation or regulations. Products and Services offered on this website are not intended for residents of the United States, Malaysia and Japan. Please click here to view our full disclaimer.

This advertisement has not been reviewed by the Monetary Authority of Singapore.

Apple and the Apple logo are trademarks of Apple Inc, registered in the US and other countries and regions. App Store is a service mark of Apple Inc. Google Play and the Google Play logo are trademarks of Google LLC.