
Access all our platforms from a single account.

Asia Market Quick Take – September 5, 2025

Asia Market Quick Take – September 5, 2025
Key points:
- Macro: US private sector hiring slows. US to lower Japan auto imports to 15%.
- Equities: Lululemon falls 16% after cutting outlook again
- FX: All eyes on NFP as US dollar index implied volatility remains elevated
- Commodities: Oil fell on OPEC+ output-hike speculation before Sunday’s meeting
- Fixed income: 10-year yield ~4.17%, near lowest since 1 May
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- US private businesses added 54K jobs in August 2025, below the 65K forecast, following 106K in July. Leisure and hospitality led gains, amid a general hiring slowdown. The service sector gained 42K jobs; goods-producing added 13K, while manufacturing lost 7K jobs. Early strong job growth has been disrupted by uncertainty.
- US will lower tariffs on Japanese auto imports to 15% by month's end, per an executive order by President Trump, Reuters reported. This formalizes a July trade agreement with Tokyo, easing negotiations and reducing uncertainty for Japan's auto industry.
- Japan's nominal wages rose 4.1% in July 2025, exceeding the 3% forecast. Real wages increased 0.5% for the first time since December, aided by steady pay and bonuses, but high prices persisted. Consumer inflation hit 3.6%, above the 2% target. Major firms agreed to pay hikes over 5% in spring talks.
- The ISM Services PMI increased to 52 in August 2025, surpassing the forecast of 51 and marking the highest growth in six months. Business activity, new orders, and inventories saw faster growth. However, employment contracted (46.5), backlog of orders hit a 16-year low (40.4), and prices remained elevated (69.2).
- The US trade gap widened to $78.3 billion in July 2025, exceeding forecasts of $75.7 billion. Exports grew 0.3% to $280.5 billion, while imports rose 5.9% to $358.8 billion. Gains in nonmonetary gold and civilian aircraft contrasted with declines in finished metal shapes and pharmaceutical preparations.
- US initial jobless claims rose by 8,000 to 237,000 in late August, exceeding expectations of 230,000. Continuing claims fell to 1,940,000, the lowest in five months, below forecasts of 1,960,000. The report indicates a softening labor market, supporting the Fed's view on potential rate cuts.
Equities:
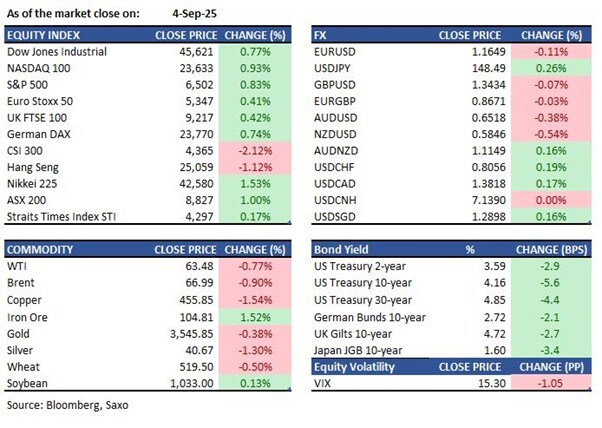
- US - U.S. stocks climbed Thursday as weak labor data boosted expectations for a Fed rate cut this month. The S&P 500 rose 0.8% to a record, the Nasdaq gained 0.9%, and the Dow added 350 points. Private payrolls grew just 54K in August and jobless claims hit a two-month high, reinforcing bets on a 25 bps cut, while a strong ISM services PMI signaled economic resilience. Amazon jumped 4.3% on AI optimism, Meta rose 1.6%, and Broadcom gained 1.2% ahead of earnings, while Salesforce slid 5.1% on weak guidance. In the after hours, Lululemon fell 16% after cutting its outlook for the 3rd straight quarter while Broadcom gained 4.5% after beating earnings expectations and issuing strong guidance for this quarter. Docusign gained 8.2% after reporting Q3 earnings that beat expectations, raising its full year revenue outlook to $3.189b - $3.201b from $3.16b.
- EU - European stocks closed higher Thursday, with the STOXX 50 up 0.4% and STOXX 600 up 0.6%, extending gains as long-term yields eased on weak U.S. labor data, reinforcing Fed rate-cut bets. Tech outperformed, with ASML up 3.5% and SAP up 0.9%, while travel stocks slumped after Jet2 cut its winter capacity outlook, plunging 12.5% and dragging Ryanair (-3.2%), easyJet (-3.7%), and TUI (-1.2%).
- HK - Hang Seng fell 1.1% to 25,058 on Thursday, its third straight loss amid broad declines. The index tracked mainland weakness after reports China may ease short-selling curbs to cool an overheated market following a 10% August surge. Tech dropped 1.9%, led by Cambricon on concerns over index rebalancing, while property, consumer, and financials also slipped on global fiscal worries. Losses were partly offset by expectations of a Fed rate cut after weak U.S. jobs data. Major decliners included Horizon Robotics (-6.9%), SMIC (-6.4%), Kuaishou (-3.1%), Innovent (-6.9%), Hansoh (-4.4%), and Akeso (-4.2%).
- SG – The STI index gained 0.17% yesterday led by Venture Corp gaining 2.18%. Flight bookings poised for pick up in Q4 on the back of high profile events like F1 and Blackpink’s two sold out concerts. Bookings are up 19% yoy.
Earnings this week: No notable names scheduled today
FX:
- The dollar advanced as further signs of labour‑market cooling bolstered expectations for a Fed rate cut this month. Traders positioned for larger swings ahead of tonight’s US jobs report, with overnight implied volatility on the dollar index at its highest since early July and one‑day EURUSD vol also higher. EURUSD fell 0.1% to 1.1651.
- USDJPY hovered around 148.50, up 0.3%, after touching 149.14 on Wednesday, a one‑month high; Reuters said the US and Japan are in late‑stage talks to reduce tariffs on Japanese auto imports. The yen was broadly steady ahead of payrolls, and Japanese bonds are expected to firm on overseas leads.
- GBPUSD slipped 0.1% to 1.3436.
- AUDUSD fell 0.4% to 0.6517, pressured by weaker Chinese equities amid reports of potential market‑cooling measures.
- NZDUSD is down 0.7% this week to 0.5846 and was little changed this morning.
- The yuan was mostly steady as a stronger PBOC fixing offset dollar strength: USDCNH was little changed at 7.1392, while USDCNY ended Thursday slightly stronger at 7.1401 after three days of declines.
Commodities:
- Oil retreated on speculation OPEC+ will raise output at Sunday’s meeting, adding to fears of higher supply later this year. WTI fell 0.8% to settle near $64.50, extending losses after weaker‑than‑expected US jobs data dented the demand outlook. Prices had already slumped Wednesday on reports the group may consider fresh increases.
- Copper fell a second day on the LME as base metals retreated and the dollar firmed ahead of Friday’s US payrolls. It closed down 0.8% at $9,898/t after a March‑high intraday on Wednesday; nickel -0.4%, aluminium -1.1%, zinc -0.6%.
- Gold eased from record highs as markets awaited US jobs data to validate Fed‑cut bets; bullion fell up to 1.3% on profit‑taking after a seven‑day surge, having set a record above $3,578 on Wednesday.
Fixed income:
- US Treasuries advanced after August ADP missed forecasts and weekly jobless claims exceeded expectations. Post‑data, swaps priced about a 92% chance of a 25 bp cut at the September meeting in two weeks. Attention stays on the labour market, with tonight’s payrolls a key catalyst for near‑term Fed pricing. The 10‑year yield hovered around 4.17%, near its lowest since 1 May.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.