
Access all our platforms from a single account.

Asia Market Quick Take – 30 September, 2026

Key points:
- Macro: US jobs openings miss forecasts, lowest in 5 months
- Equities: Stocks lower for 2nd day as yields rise; Carnival +13% after earnings
- FX: EURUSD falls to a 16-month low; AUDUSD hits a two-month low
- Commodities: WTI falls below $90 and gold rebounds
- Fixed income: US 30-year Treasury yield tops 5.61%, hitting a 24-year high
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- US job openings fell by 256,000 to 7.08 million in August 2026, a five-month low and below forecasts, with broad sector and regional declines except in the South. Hires and separations were little changed at 5.2 million and 5.1 million, respectively.
- Japan’s industrial production fell 1.7% m/m in August 2026, its second straight decline and well below forecasts for a 1.7% rise, as weaker export demand hit autos, machinery, and petroleum/coal products. Output still rose 3.4% y/y, easing from 3.9% in July.
- Japan’s retail sales rose 2.7% y/y in August 2026, the sixth straight gain but below the expected 3.3% and July’s 3.7%, driven mainly by a 17.7% jump in motor vehicle sales. However, sales fell 1.2% m/m, reversing a 2.1% increase in July.
- Advance estimates showed Canada’s real GDP rose 0.2% in August after a flat July, with gains in mining, quarrying, and retail partly offset by weaker oil and gas. The soft start to Q3 reinforces expectations for the BoC to hold rates as the US import ban on various Canadian goods takes effect.
Equities:
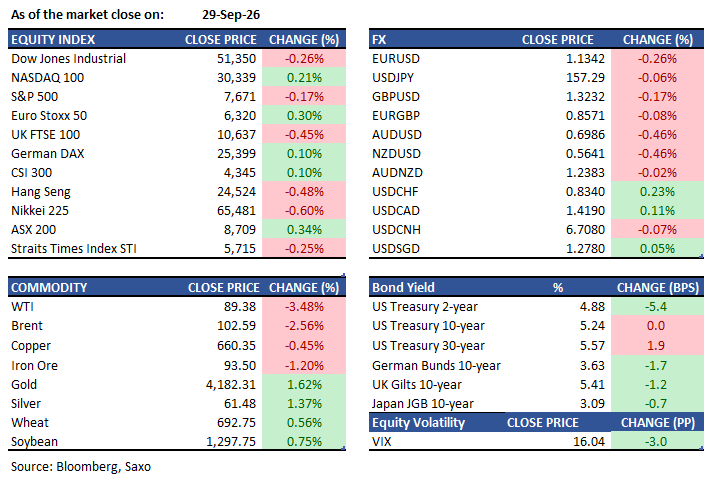
- US (Tuesday, 29 Sep close): US equities posted a second consecutive day of losses as surging long-end Treasury yields and weak consumer confidence weighed on sentiment. The S&P 500 fell 0.2% to 7,670.84, the Dow dropped 0.3% to 51,349.92, and the Nasdaq Composite edged down 0.1% to 26,797.54. The Nasdaq 100 managed a slim 0.2% gain. The largest single-stock move was Fair Isaac (FICO), which plunged 26.5% for its biggest-ever decline. Carnival surged as much as 14% — its best session since April 2025 — after raising its full-year EPS outlook. Apple fell 2.7%, leading S&P 500 decliners. In after-hours trade, Coursera (COUR) gained 5.1% after Pale Fire Capital acquired a stake, while US index futures ticked modestly higher (S&P 500 futures +0.1%, Nasdaq 100 futures +0.3%).
- EU (Tuesday, 29 Sep close): European equities erased early gains as the US Treasury selloff resumed into the close. The Stoxx 600 edged down to 638.08, the FTSE 100 fell 0.5% to 10,636.71 with Shell the largest drag (-1.7%), and the DAX was fractionally higher at 25,399.21 with Infineon the standout gainer (+4.8%). The Euro Stoxx 50 rose 0.3% to 6,320.26. Julius Baer surged as much as 8.8% to a record high after Swiss regulator FINMA required only CHF250 million in additional capital, less than previously feared. Lindt fell 8.7%, the index's largest single-stock decline. ASML rose 4.2% on chip sector optimism. The Stoxx 600 is on track to close September down ~1.9%.
- Asia (Wednesday, 30 Sep, as of 08:01 HKT): Asian equities are rebounding for the first time in three sessions, aided by lower oil prices and reduced Fed rate-hike bets. The Kospi opened up 1.1% to 6,943.47, led by chipmakers, though Samsung and SK Hynix face a headwind as their combined ¥55 trillion buyback programme is ~80% complete and may end earlier than expected. Nikkei 225 futures on SGX were up 0.9% at 66,350 ahead of the open; the index closed Tuesday at 65,481.27 (-0.6%), with Kioxia notable for a ~40% quarterly decline. Nidec shares are set to open higher after reports it is finalising the sale of its components unit to Carlyle for over ¥100 billion. The Hang Seng closed Tuesday at 24,523.57; Shein fell 10% after its inaugural 1H results showed a 53% plunge in operating income. The STI closed at 5,714.84. Regional chipmakers are expected to benefit after Trump reportedly lifted some semiconductor export restrictions.
Earnings and events this week:
- Wednesday: Micron Technology — Q4 FY2026 results (widely watched for AI/semiconductor demand signals), Factset
- Thursday: Nike
- Friday: No major earnings expected; focus shifts to the September Non-Farm Payrolls report.
FX:
- The euro fell as much as 0.5% on Tuesday to $1.1312, its weakest level since May 2025, driven by broad dollar strength on rising US yields. The pair is on track for its worst monthly performance since July 2025. Current spot: 1.1341.
- The US Dollar Index extended its advance alongside long-end Treasury yields, rising to a two-month high on Tuesday. Current level: 101.42. The dollar is benefiting from the hawkish Fed backdrop and risk-off flows.
- The Australian dollar dropped as much as 0.7% to 0.6966 in Tuesday's New York session, its lowest since July 30, after RBA Governor Bullock signalled less urgency for further rate hikes. Current spot: 0.6987. AUD is down ~2.5% month-to-date.
- Despite the sharp widening of US-Japan yield spreads (10-year spread widened ~17bp over the past week), the yen has held relatively firm near 157.36, reportedly finding support after joint US-Japan FX intervention in July. Japan's top currency official has recently issued fresh warnings against yen weakness. The Mexican peso is the worst-performing major currency over both the past week and month-to-date, down ~4.3% over five sessions and ~6.1% in September, with USDMXN pushing above 18 as several pillars of its earlier strength give way simultaneously.
Commodities:
- Brent crude fell 2.8% on Tuesday to close below $103/bbl (current: $102.59) after Saudi Arabia resumed flows through its East-West pipeline and the Trump administration released up to 40 million barrels from the SPR. WTI fell more than 3% to $89.25. The pullback is providing some relief to inflation fears, though prices remain elevated relative to pre-Iran-war levels.
- Gold rebounded on Tuesday after falling more than 3.5% on Monday to $4,115.71/oz — its lowest close since early August — as oil gains and rising real yields dented the metal's appeal. Current spot: $4,186.82/oz. Silver also bounced sharply from Monday's rout, which saw it fall more than 5%. Current silver spot: $61.52/oz.
Fixed income:
- The 30-year Treasury yield surpassed 5.61% on Tuesday, touching levels last seen in June 2002, extending a six-day streak of gains. The move was driven by persistent inflationary concerns, heavy corporate bond supply, and fiscal worries around the US's $40 trillion national debt.
- Williams' comments triggered a front-end rally, with the 2-year yield falling ~5bp to 4.88% at session lows, while the long end held losses. The 5s30s spread widened to 52.8bp from 47.9bp. The 10-year yield settled at 5.259%, on pace for its eighth 19-year closing high this month. Real 10-year yields rose to 2.91%, up 99bp year-to-date.
- Japanese government bonds have outperformed global peers in September, with the 10-year JGB yield at 3.085%. A 2-year JGB auction is scheduled for Wednesday; analysts expect solid demand given yields near 2% offer relative value versus the BOJ policy rate.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.