
Access all our platforms from a single account.

Asia Market Quick Take – 09 April, 2026

Asia Market Quick Take – 9 April, 2026
Key points:
- Macro: Israel strikes Lebanon, threatening the ceasefire
- Equities: Ceasefire sparks broad US equity rally; airlines soar, energy shares slump
- FX: Risk-on mood drives SEK, AUD, NZD sharply higher as dollar weakens
- Commodities: WTI crude plunged 16.4%, its biggest one-day drop since April 2020
- Fixed income: European bonds surged; German 10y at 2.90%, 3-week low
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- US and Iran agreed to a two-week ceasefire tied to reopening the Strait of Hormuz, but the passage remains mostly blocked and tanker traffic suspended after renewed Israeli strikes on Lebanon. Iran says three terms of the truce have already been violated and disputes whether it covers Lebanon. US Vice President JD Vance, heading to Islamabad for talks with Iran, says there are signs the strait may begin to reopen.
- Fed March minutes showed inflation worries from the Iran war, but markets still priced in possible rate cuts later this year.
- The average 30-year fixed US mortgage rate for conforming loans dipped to 6.51% in the week ending April 3, 2026, from 6.57%, its first decline in over a month as Treasury yields fell on Middle East war worries. Overall applications still slipped 0.8%, with refis down 2.8% and purchase loans up 1.1%.
- RBNZ held its cash rate at 2.25%, flagged higher near-term inflation risks from Middle East tensions, and signaled possible hikes.
Equities:
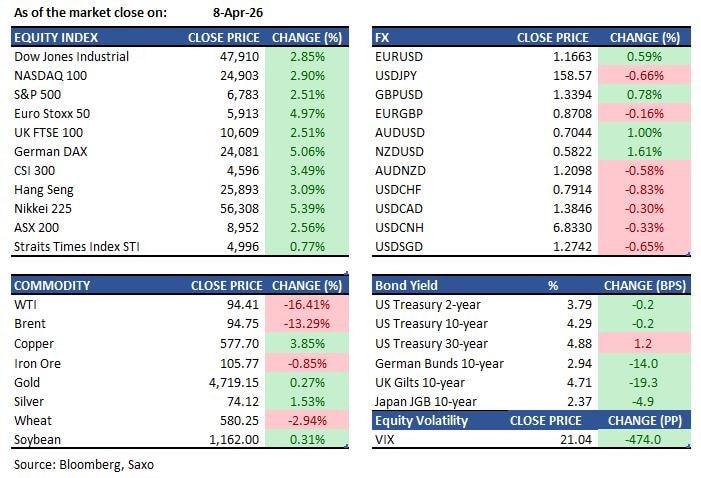
- US: US equity markets surged in a broad relief rally following the ceasefire announcement. The S&P 500 soared 2.5% to 6,773.1, breaking above its 50-day and 200-day moving averages. The Nasdaq Composite jumped 2.7% to 22,603.4, while the Dow Jones Industrial Average catapulted 2.7% to 47,824.2, gaining 1,325 points. More than 400 stocks in the S&P 500 traded higher. Energy stocks fell sharply, with Exxon down 6.4% and Occidental declining 6.6%. Airlines rallied strongly, with United up 9.6%, American up 7.4%, and Delta up 5.4%. Avis Budget Group surged more than 150% over three weeks amid a short squeeze.Levi Strauss gained 10.6% after they reported stronger than expected quarterly results and raised full year projections.
- EU: European equity markets staged their biggest rally since March 2022, with the Stoxx Europe 600 Index surging 3.9%. Germany's DAX led gains, climbing 5.1% to 24,080.63, its largest advance since March 2022. France's CAC 40 rose 5% to 8,304.55, while the UK's FTSE 100 jumped 2.5% to 10,608.88. Travel and tourism stocks led the advance, with EasyJet and TUI both jumping more than 10%. Energy stocks declined as oil prices collapsed, with Norway's OSEBX falling 3.5% as Equinor dropped as much as 13%. Industrials and materials sectors posted strong gains across the region.
- Asia: Asian equity markets rallied sharply on the ceasefire news, with the MSCI Asia Pacific Index gaining 4.9% to a one-month high. Japan's Nikkei 225 surged 5.4% to 56,308.42, its largest gain in almost a year, led by AI-linked stocks including Furukawa Electric and Kioxia Holdings, which rose 18.6%. South Korea's Kospi jumped 6.9% to 5,872.34, with Samsung Electronics up 7.1% and SK Hynix soaring 13%. Hong Kong's Hang Seng Index climbed 3.1% to 25,893.02, with HSBC rising 6.6%, Meituan gaining 10.3% and Alibaba up 6.75%. China's CSI 300 Index gained as much as 3.4%, the most since October 2024. India's Nifty 50 rose 3.8% to 23,997.35, its steepest single-day advance since May 2025. Singapore's Straits Times Index rose 0.8%with SATS gaining 4.5%.
FX:
- USD weakened to a four‑week low after the US and Iran agreed to a two‑week ceasefire, which sent oil sharply lower and lifted global equities. The Bloomberg Dollar Spot Index fell as much as 1.1% intraday before closing down 0.8%.
- High‑beta currencies rallied, led by SEK, with USDSEK dropping 1.6% to 9.3208.
- EURUSD climbed over 1% to a high of 1.1722 and GBPUSD rose as much as 1.45% to 1.3484, with both pairs advancing for a third straight session; sterling still carries the most persistent “tail” premium linked to prior energy‑inflation shocks.
- USDJPY fell 0.65% to 158.58 after Japan’s inflation‑adjusted wages posted their fastest rise since 2021, bolstering expectations the BOJ could hike as soon as this month.
- AUDUSD briefly gained up to 1.6% to 0.7085 before easing, while NZDUSD jumped as much as 2.3% to 0.5859 after the RBNZ held rates at 2.25%.
- The Chinese yuan climbed to a three-year high, with USDCNH falling 0.32% to 6.8334 and USDCNY dropping 0.4% to 6.8360, both at their strongest since March 2023.
Commodities:
- WTI crude oil plunged 16.4% to settle at $94.41 per barrel, its largest one-day decline since April 2020, though prices rebounded overnight to around $97 as the Strait of Hormuz remained largely blocked and Israeli attacks on Lebanon threatened the fragile ceasefire.
- Gold pared gains, up 0.4% after earlier rising as much as 3.2% above $4,800/oz, after Iran’s parliament speaker Mohammad‑Bagher Ghalibaf said three clauses of the temporary US‑Iran ceasefire had been violated.
- Copper advanced 3.2% to settle at $12,709 per ton on the London Metal Exchange, hitting a three-week high on improved risk sentiment, while silver surged 4.73% to $75.224 per troy ounce.
Fixed income:
- US Treasury yields initially fell sharply before paring declines, with the 10-year yield dropping as much as 6.5 basis points to 4.240% before closing down just 0.6 basis points at 4.291%.
- European government bonds surged, with German 10-year yields falling as much as 18 basis points to 2.90%, a three-week low, while Italian yields slumped 31 basis points to 3.66%.
- The Treasury's $39 billion 10-year note auction attracted average demand with a high yield of 4.282%, slightly above the when-issued level, while the bid-to-cover ratio came in at 2.43.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.