
Access all our platforms from a single account.

Asia Market Quick Take – 05 March, 2026

Asia Market Quick Take – 05 March, 2026
Key points:
- Macro: US sinks Iranian warship near Sri Lanka; First since WWII
- Equities: Equities rebound as oil declined and strong UD data
- FX: AUDUSD nears 0.71, bolstered by strong GDP growth
- Commodities: Oil continues to rise due to closure of Straits of Hormuz
- Fixed income: US 10Y yields rise as investors weigh risk of inflation
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- US-Iran tensions rose after a US submarine allegedly sank an Iranian warship near Sri Lanka, the first such strike since WWII. The US-Israeli campaign is in its sixth day, worrying markets over a prolonged conflict. The Strait of Hormuz is blocked after Iran's IRGC threats. President Trump offered insurance and escorts for Gulf vessels, while Treasury Secretary Bessent suggested market-stabilizing measures.
- The US ISM Services PMI rose to 56.1 in February, surpassing January's 53.8 and beating expectations of 53.5. Business activity and new orders saw significant growth. Employment improved to 51.8, while supplier deliveries slowed at 53.9. The Prices Index fell to 63, indicating cost pressures.
- US private businesses added 63,000 jobs, led by education and health services with 58,000 in February. Small businesses created 60,000 jobs, while medium-sized firms cut 7,000. Job-stayers' pay growth held at 4.5%; for job-changers, it slowed to 6.3%.
- Euro Area producer prices rose 0.7% in January 2026, reversing December's 0.3% drop and exceeding the 0.2% forecast. Energy prices and gains in intermediate, durable consumer, and capital goods drove the increase, while non-durable goods prices fell 0.2%. Annually, prices decreased by 2.1%.
Equities:
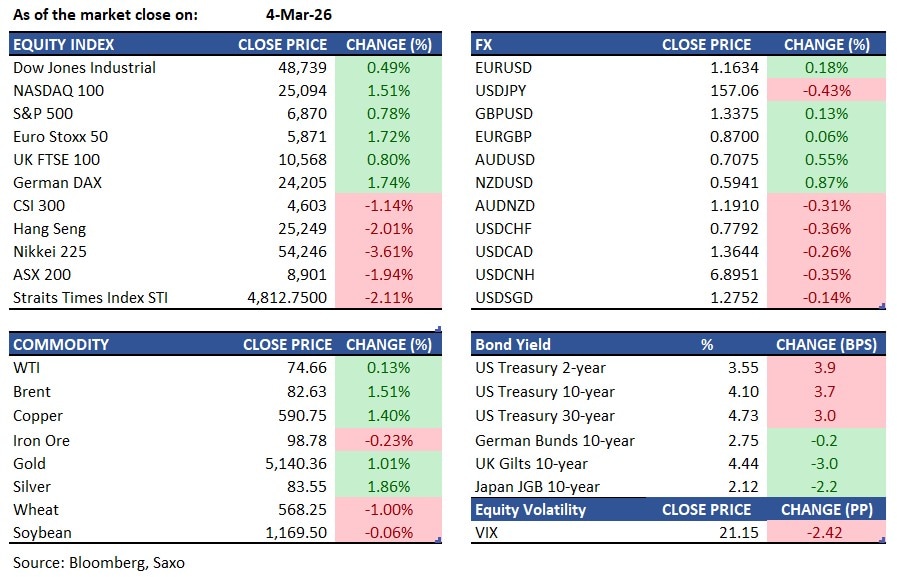
- US - S&P 500 increased by 0.7% and the Nasdaq 100 by 1.4%, buoyed by strong tech sector gains. The Dow rose 0.5% due to declining oil prices and reassuring economic data. Treasury Secretary Scott Bessent's support for Persian Gulf oil flows helped WTI crude fall for the first time since the conflict began. Despite new 15% global tariffs, sentiment improved with strong private job growth and easing inflation pressures. Tech stocks like Micron, AMD, and Amazon led the rally, while financials KKR and Blackstone rose around 3%. Moderna rose 16% after agreeing to pay $950 million to Genevant and Arbutus, settling a lawsuit over its Covid vaccine delivery tech. CrowdStrike gained by 4% after reporting fourth-quarter results that met expectations and providing forecasts for the upcoming quarter and year.Broadcom forecasts strong Q2 revenue of $22B, outpacing $20.53B estimates. Q1’s adjusted EPS reached $2.05, exceeding expectations. Shares rose 4% in aftermarket trading, boosted by a $10B buyback plan and anticipated AI chip sales growth.
- EU -European stocks attempted to rebound on Wednesday, with the STOXX 50 up 0.7% and STOXX 600 gaining 0.6% after significant losses. Technology, utilities, and consumer non-cyclicals led the recovery, with ASML Holding up 1.5%, L’Oréal 1.2%, and SAP 1.6%. Spanish stocks lagged behind as financials fell due to Trump's threat to halt trade following Spain's base-use restrictions; CaixaBank fell 1.8%, Bankinter 1.9%, and Banco Santander 0.8%. Adidas dropped about 7% due to disappointing results.
- Asia - Asian equities are expected to open higher after a previous session of heavy selling. Futures for Japan, Australia, and Hong Kong climbed, while South Korea’s Kospi index traded about 8% higher, suggesting a recovery after Wednesday’s decline. Hang Seng Index fell 2.0%, to 25,249, marking its third consecutive decline and the lowest level since mid-December. Concerns over Middle East tensions and China's manufacturing slowdown contributed to the drop. Losses hit financials and consumer stocks, while aluminum producers rose due to higher metal prices following a Qatari smelter shutdown.
Earnings this week:
- Thursday - Costco Wholesale, JD.com, Kroger, Marvell Technology, Samsara, Pattern Energy, Ciena, GoPro, American Eagle, Victoria's Secret
- Friday - Embraer, Algonquin Power, Genesco, Drilling Tools International
FX:
- USD weakened against all G-10 currencies as global equities rebounded and oil prices fell following reports, later denied by Tehran, that Iranian operatives sought discussions to end the conflict. The Bloomberg Dollar Spot Index lost 0.25% in New York afternoon trading.
- AUD, NZD, and SEK led gains among G10 currencies. The AUD was bolstered by a Q4 GDP growth rate of 0.8%, surpassing the expected 0.6%. AUDUSD remained high at approximately 0.7083
- USDJPY decreased 0.4% to 157.04 amid Japan's warnings of potential market intervention.
- EURUSD increased 0.2% to 1.1632, marking its first rise of the week but still trailing its 200-day moving average of 1.1671.
- CHF showed slight strength after February's year-over-year CPI exceeded expectations at 0.1% (expected -0.1%). EURCHF declined 0.17% to 0.90658 as Swiss officials indicated a heightened readiness for currency market intervention.
Commodities:
- Oil prices surged amid the US-Israeli conflict with Iran, disrupting traffic through the Strait of Hormuz. WTI reached $75.92, up 11% this week, while Brent closed at $82.62. The conflict forced production shut-ins, with the US proposing insurance and naval support to ease supply disruptions. India’s Mangalore Refinery halted exports due to delivery issues.
- Gold increased 0.95% to $5,137.16, supported by dip-buyers and a weaker dollar amidst Middle East tensions. While geopolitical risks boost demand, inflation from energy prices may limit gains as central banks hold interest rates steady. Silver, platinum, and palladium also rose.
- Aluminum prices surged to their highest since 2022 after Aluminium Bahrain BSC suspended deliveries due to shipping delays through the Strait of Hormuz amid the Iran conflict. Prices rose 5.1% in London, with aluminum settling at $3,342.50 per ton. Nickel also rose 2.2%.
Fixed income:
- US 10-year Treasury yield increased 2bps to 4.09% as traders examined Iran conflict updates, tariff news, and economic data. Oil prices eased following reports of potential negotiations with Iran. Rate cut expectations shifted to September. The ISM Services PMI showed strong sector expansion.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance. The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.