
Access all our platforms from a single account.

Asia Market Quick Take – October 17, 2025

Key points:
- Macro: Bank fraud revealed by Zions and West Alliance revives US regional woes
- Equities: Zions down 13%, Western Alliance falls 10.8% on loan fraud fears
- FX: Dollar Index fell; CHF, JPY, EUR strengthened amid US regional bank worries
- Commodities: Gold and silver extended gains, setting fresh records on haven demand
- Fixed income: Treasuries bull‑steepened; US 2‑year yields at 3.41%, lowest since 2022
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- US regional banking woes were reignited after Zions Bancorporation and West Alliance announced bad loans tied to fraud.
- The White House is poised to ease tariffs on the US auto industry, delivering a major win for carmakers. The Commerce Department is expected to announce a five‑year extension of an arrangement that allows manufacturers to reduce duties on imported parts, following months of lobbying by Ford and General Motors for relief from President Donald Trump’s tariffs.
- USTR's Greer noted China's actions suggest a move towards decoupling, with the US focusing more on rare earths investment. China's Commerce Ministry urged the US to recognize past progress and address recent tensions, attributing them to US restrictions. MOFCOM assured approved civilian rare earth licenses and distinguished export controls from bans. China's Foreign Minister advocated against US decoupling, urging constructive dialogue to resolve issues.
- Bank of Japan Governor Kazuo Ueda signalled further tightening is likely if confidence in the bank’s economic outlook improves. He will continue gathering information at international meetings and assess data ahead of the 29–30 October decision. Markets assign roughly a 17% chance of a hike this month.
- US President Donald Trump said he plans a second meeting with Russia’s Vladimir Putin “within two weeks or so” to seek an end to the war in Ukraine. He voiced optimism about a ceasefire, saying “Alaska set the stage” and “we’ll be successful, save a lot of lives.” High‑level staff talks will take place next week ahead of the summit, with the US delegation led by Secretary of State Marco Rubio.
Equities:
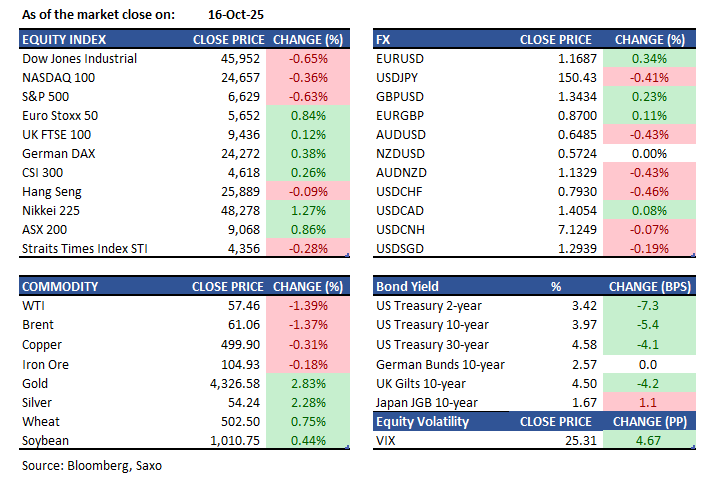
- US - U.S. stocks fell Thursday as concerns over regional bank credit quality and persistent U.S.-China trade tensions weighed on sentiment. The S&P 500 dropped 0.6%, the Nasdaq 100 slipped 0.5%, and the Dow lost 302 points. Zions Bancorporation plunged 13% on loan losses, while Western Alliance sank 10.8% amid a fraud lawsuit, fueling fears of bad loans. Earlier, chipmakers lifted markets after TSMC raised revenue forecasts and posted strong profits, reinforcing optimism around AI demand. Geopolitical risks intensified as Trump warned the U.S. is “in a trade war now” and threatened new tariffs. The prolonged government shutdown added uncertainty, delaying key data.
- EU - European stocks advanced Thursday, with the Stoxx 50 up 0.9% and Stoxx 600 gaining 0.6%, led by food and beverage shares. The sector jumped 3.2% after Nestlé announced plans to cut 12,000 jobs, with another 4,000 reductions over two years. Sartorius surged 9% on stronger revenue and profitability, while Nordea rose 3% to record highs on robust lending growth and a Norwegian acquisition. Whitbread slumped 10% after weak results. France’s CAC 40 benefited from political stability as the new government survived a no-confidence vote, easing investor concerns. Sentiment remained supported by hopes of tariff delays and improving corporate fundamentals.
- HK - Hang Seng slipped 0.1% to 25,888 Thursday, reversing Wednesday’s rally as investors awaited China’s fourth plenum (Oct. 20–23) and key economic data next week, including Q3 GDP and September retail sales. Tech, consumer, and property stocks led losses, with Nio plunging over 13% before trimming declines amid a lawsuit from Singapore’s GIC. Xiaomi (-3.8%), XPeng (-3.5%), and SMIC (-2.6%) also weighed on the index. Financials outperformed on defensive rotation, lifting China Life (+5.1%), Ping An (+1.5%), and Bank of China Hong Kong (+1.3%). Traders largely shrugged off U.S. tariff pause signals tied to rare-earth export controls.
Earnings this week:
- Friday: Tokyo Steel; American Express; Interactive Brokers; Volvo
FX:
- Dollar Index dipped to 98.30 on Thursday amid global risk-off sentiment fueled by US regional bank concerns, including bankruptcies and lawsuits against Western Alliance.
- CHF, JPY, and EUR gained as USD alternatives amid US risk aversion. BoJ officials, including Assistant Governor Shimizu and Tamura, urged caution in policy normalization due to trade uncertainties. Governor Ueda affirmed a steady global outlook but noted adjustments aligned with growth and inflation forecasts. USDJPY slipped to 150.20.
- GBP strengthened, buoyed by August GDP data meeting expectations and robust service and manufacturing outputs. GBPUSD reached 1.3440 from prior 1.3394 lows.
- AUD lagged following disappointing job numbers, with growth flat over two months and unemployment rising to 4.5%. AUDUSD hovered at 0.6480.
Commodities:
- Oil headed for a third weekly drop as investors focused on supply and the fallout from renewed US–China trade tensions. WTI traded just above $57 and was on track for a 2.4% weekly decline, while Brent settled near $61. President Donald Trump said he will meet Russia’s Vladimir Putin again within about two weeks to discuss ending the war in Ukraine, raising concern that additional OPEC+ barrels could deepen the global glut.
- Gold and silver set fresh records as credit‑quality concerns and intensifying US–China frictions lifted haven demand, alongside bets on an outsized Fed cut this year. Gold rose up to 1.2% to $4,379.96, its strongest week since 2020, while silver briefly hit $54.3775 before easing.
Fixed income:
- Treasuries bull‑steepened as credit concerns at two regional US banks spurred a flight to safety, with US 2‑year yields falling to 3.41% at the peak of the front‑end rally—the richest since 2022. The S&P Regional Banking ETF closed near session lows, down about 6%. Swaps priced in two full 25bp cuts for October and December. Australian bonds also firmed, buoyed by the Treasury rally and ahead of a 2030 note auction.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.