
Access all our platforms from a single account.

Asia Market Quick Take – 14 August, 2026

Key points:
- Macro: Headline and Core PPI cools. Initial jobless claims at 209k vs 202k expected.
- Equities: Sandisk +15% after issuing bullish outlook; S&P 500 trades to new highs
- FX: USD softer on cooler inflation; JPY steady near 160; NZD outperforms peers
- Commodities: Gold futures -1.03%, largest since Jul 31; snaps 4-day run
- Fixed income: 30-year auction at highest yield since 2001
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- US July PPI reported at 0% m/m (vs +0.2% est.) and up 4.7% y/y (vs 4.9% est.). Core PPI rose 0.2% m/m (vs 0.3% est.) and 4.2% y/y (vs 4.1% est.). Following Wednesday’s soft CPI, the data have cut the implied probability of a September Fed hike to under 40%.
- US initial jobless claims for the week ended 8 August rose 9,000 to 209,000 (vs 202,000 est.), while continuing claims fell 22,000 to 1.777 million.
- UK GDP grew 0.4% in Q2, matching expectations after 0.6% in Q1. June GDP rose 0.3% m/m, beating flat forecasts.
- Swiss producer and import prices fell 2.1% y/y in July 2026, unchanged from June and extending a three-year deflation streak. Producer prices were down 2.3% and import prices 1.5%. Month-on-month, overall prices slipped 0.1%, a third straight decline.
- UK manufacturing output fell 0.5% m/m in June 2026, worse than May’s revised -0.2% and below expectations. Annual growth slowed to 0.5% from a revised 2.0%, missing the 1.2% forecast.
Equities:
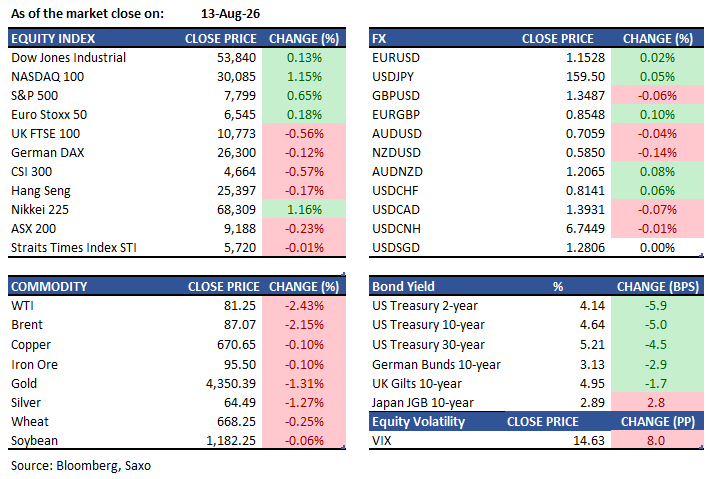
- US — S&P 500 rose 0.7% on Thursday to close at a fresh all-time high of 7,798.99, extending its August advance. The Nasdaq 100 gained 1.15% to its highest level since end-June, driven by renewed strength in technology and hyperscaler-linked names. Sandisk jumped 15% after giving a bullish outlook at an analyst meeting in New York, with its CEO expecting revenue to grow mid to high teens through 2030, with gross margins to sustain at 80%. Netflix gained 5% after Bill Ackman’s Pershing Square revealed a 3.15m share stake. In after-hours, Reddit surged 10% on announcement of its inclusion in the S&P 500 effective 18 August. Applied Materials fell 5% despite reporting Q4 revenue of $9.12b that beat estimates and issued a strong forecast.
- EU — European equities were mixed on Thursday amid thin summer trading. The Euro Stoxx 50 edged up 0.18% to 6,545.47, just 0.09% below its all-time high set on 11 August. The DAX slipped 0.1% to 26,299.74 and the CAC 40 fell 0.28% to 8,650.56, its third consecutive down day. The FTSE 100 fell 0.6% to 10,772.67, dragged by miners and ex-dividend heavyweights, with Antofagasta sliding 6.7% after cutting copper production guidance. The standout mover was Adyen, which surged 16% after raising its revenue outlook.
- Asia — Asian markets are set for a strong open on Friday, building on Wall Street's record close. The Kospi opened up 2.7% to 6,995.67, boosted by a surge in memory and chip names following Sandisk's strong investor day targets. Japan's Topix is on track to extend its winning streak to an eighth consecutive session, with futures pointing higher. Lenovo was the standout in Hong Kong on Thursday, surging as much as 22% to a record after Q1 revenue jumped 43% year-on-year, well ahead of estimates, lifting peers including Dell and HP. CK Hutchison reported 1H net income of HK$26.8 billion versus HK$852 million a year ago, driven by asset disposal gains. SMIC posted Q2 revenue of $3.01 billion (+36% y/y) with net income significantly beating estimates. JD.com ADR fell 7% after Q2 net revenue of RMB346.4 billion beat consensus but was the first quarterly decline since listing. The Nasdaq Golden Dragon China Index fell 1.8% on Thursday, with Chinese drone stocks facing potential pressure from new US tariffs. STI data was not available at time of writing.
Earnings this week:
- Friday: Kweichow Moutai
FX:
- USD is modestly softer versus G10 peers, with EUR, GBP and AUD slightly higher and the Bloomberg Dollar Spot Index broadly flat as moderating US inflation reinforces expectations the Fed will keep rates on hold into September. NZD has outperformed a 14‑currency basket.
- USDJPY is again pressing toward 160 despite a recent historic joint US‑Japan intervention, as carry traders rebuild yen shorts, though reports that PM Takaichi’s government supports a faster BOJ hiking path (potentially Sep–Oct) offer some support to the yen.
- USDCNY and USDCNH are both flat for a third consecutive session. One-month implied volatility on USDCNH has fallen for the third time this week to 1.67%. The PBOC set Thursday's fixing at 6.7888, slightly weaker than Wednesday's 6.7882.
- In options, hedge funds are buying short‑term AUDNZD call spreads after softer NZ 2‑year inflation expectations BNY says cross‑border investors are re‑upping FX hedges on US assets, suggesting a “dollar de‑hedging peak.”
Commodities:
- WTI settled at $81.25 a barrel, down 2.4% on the session, snapping a six-session winning streak. Brent settled at $87.07, down 2.15%. Profit-taking emerged as the Hormuz deal remains elusive. Late Thursday, Iran attacked two ADNOC vessels transiting the strait, keeping the geopolitical risk premium in place. WTI traded near $81 in early Asian hours Friday.
- Comex front-month gold settled at $4,363.60 an ounce, down 1.03% — its largest single-day decline since July 31 — snapping a four-session winning streak. Spot gold fell as much as 1.5% to $4,343.91 intraday. Easing inflation data bolstered expectations the Fed will hold rates in September, reducing the inflation-hedge premium. Gold remains on track for a second consecutive weekly gain despite the pullback.
- The LME copper cash-to-three-month spread rose sharply to $245.64 per tonne — the highest since June 2025 — in a one-day move of $83.39, the largest in nearly eight weeks.
Fixed income:
- Treasuries advanced following the soft PPI print. The 2-year yield fell approximately 5 basis points, the 10-year fell to around 4.67%, and the 30-year fell ahead of the auction before edging back up post-results. The 5s30s spread widened, remaining inside daily range that marked the widest levels since May, with the long end structurally heavy and biased toward further steepening as the Fed premium drains from the front end.
- The US Treasury sold $25 billion in 30-year bonds at a yield of 5.216% — the highest since 2001 — tailing the when-issued yield of 5.212% by 0.4 basis points. The bid-to-cover ratio was 2.39x, below the prior auction's 2.44x. Indirect bidders took 66.8% and primary dealers took 11.5% of the allocation. This follows Wednesday's 10-year auction, which cleared at 4.683%, the highest yield since the 2007 global financial crisis. Both auctions reflect investors demanding greater compensation to finance the growing US deficit.
- Despite the overall rate-hike narrative, options markets saw demand for hedges against rate cuts by both the Fed and the Bank of England. US money-market fund assets rose to a record $7.93 trillion, with approximately $18.3 billion in inflows in the week through August 12, as attractive front-end yields continue to draw flows.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.