
Access all our platforms from a single account.

Asia Market Quick Take – 06 July, 2026

Key points:
- Macro: UK Composite PMI falls and Eurozone Services PMI rises
- Equities: European stock indexes hit new highs
- FX: USD firms; commodity FX softer, KRW gains on 24-hour trading
- Commodities: Gold above $4,170 and Silver above $62
- Fixed income: Bund yields rise almost 9bps to 2.93%
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- The FAO Food Price Index edged down to 130.3 in June 2026 from 130.8 in May. Cereals led the fall (‑3.5%), with wheat down 4.4% on strong Black Sea harvests. Sugar dropped 5.7% as Brazilian mills favored sugar over ethanol, though El Niño risks limited further declines. Dairy slipped 1.5% to its lowest since 2023. Meat rose 0.4% to a record high on stronger poultry, while vegetable oils gained 3.8%, driven by palm and rapeseed; sunflower oil was stable.
- The UK Composite PMI fell to 49.3 in June 2026 from 49.7, marking a second month of contraction and missing expectations of 50.6. Services shrank (48.8) while manufacturing grew (52.5). Sales posted their steepest drop since April 2025, and employment declined further. Input and output price inflation eased, and business confidence improved.
- The Eurozone Services PMI rose to 49.4 in June 2026 from 47.7, signaling the mildest downturn since the recent energy shock. New business fell slightly faster, but firms accelerated backlog clearance and returned to hiring amid improved sentiment as energy and borrowing costs eased. Input cost inflation declined for the first time since October.
Equities:
- US – Closed
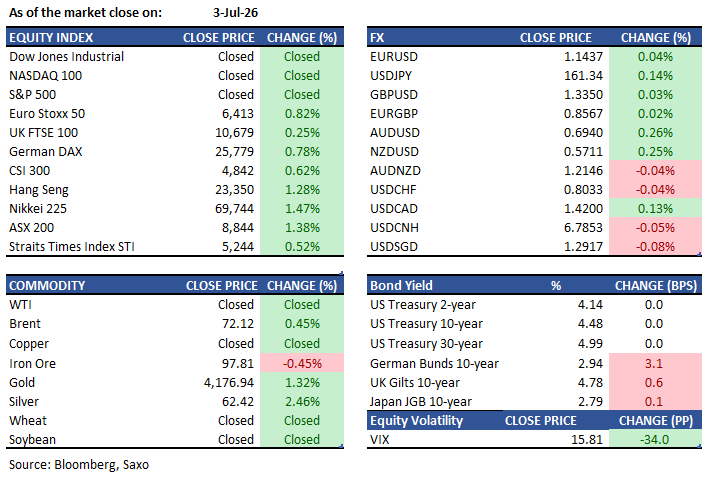
- EU - European stocks hit record highs Friday as AI‑linked tech rebounded and the macro backdrop improved. The Euro STOXX 50 rose 0.9% to 6,417 and the STOXX 600 0.7% to 653 in thin US‑holiday trade. Tech led gains (ASML +3.7%, Infineon +1.2%), along with data‑center and utilities plays (Siemens +2.5%, Schneider +1.5%, Iberdrola and Enel +1.5%). Lower short‑term yields lifted banks (BBVA, Deutsche Bank +1%), while softer US jobs data and Eurozone inflation tempered rate‑cut hopes.
- Asia - Asian markets ended the week higher on Friday, 3 July after semiconductor-driven volatility. The Kospi jumped 5.8% to 8,088, rebounding from a 7.9% plunge as Samsung and SK Hynix each climbed over 10% on reports Anthropic is in talks with Samsung on a custom AI chip. Hong Kong’s Hang Seng rose 1.3% to 23,350, led by BYD (+6.5%), Zijin Mining (+9%), and a 2%+ gain in the Hang Seng Tech Index (Xiaomi +6.6%, Horizon Robotics +11%), with mainland investors net buying HK$4.54 billion via Stock Connect. Japanese stocks also advanced. By Monday’s open, Citi cut its remaining long Kospi and moved Asia EM back to neutral on semiconductor peak concerns.
Earnings this week:
- Monday – NA
- Tuesday – Saratoga Investment, Penguin Solutions
- Wednesday – Levi's, Azz
- Thursday – Pepsico, Byrna, WD-40
- Friday – Delta Airlines
Key Event this week:
- Friday - SK Hynix ADR listing
FX:
- Overnight FX trading was relatively quiet, with broad-based USD strength. USDJPY rose 0.11% to around 161.46, keeping Japanese intervention risks in focus as Goldman Sachs lifted its USDJPY target to 165 on higher-for-longer US yields and only gradual BOJ tightening.
- Commodity currencies underperformed, led by NZDUSD, which fell 0.19% to 0.5700, while AUDUSD slipped 0.09% to 0.6930 and USDCAD and USDCHF edged higher to 1.4210 and 0.8040 respectively.
- EURUSD and GBPUSD were unchanged on the session, holding at 1.1440 and 1.3350, leaving European majors broadly stable against the dollar.
- The Korean won gained about 0.2% to 1,527.80 per dollar on the first day of 24-hour trading. Despite recent pressure alongside the yen amid broader USD strength, Korea’s solid fundamentals and the planned SK Hynix US listing could attract supportive inflows.
Commodities:
- Gold climbed to $4,170/oz and Silver to $62 per ounce on Friday. Weaker US jobs data reduced Fed hike odds for September, the dollar logged its biggest weekly drop since April, and central banks added 41 tons of gold in May, all supporting prices. Indian demand softened on higher prices, while Chinese demand edged up.
- Copper futures neared $6.2 per pound Friday and headed for a weekly gain as softer US jobs data cut September Fed hike odds to about 50% from 67%. Earlier pressure from hawkish Fed signals and easing supply risks via the Strait of Hormuz limited further upside.
Fixed income:
- The US 10-year yield slipped 2 bps to 4.46% after weaker June jobs data (57K added, prior months revised down) softened the labor market picture and cut September Fed hike odds to about 50% from 64%. Unemployment edged down to 4.2% on lower participation. Fed Chair Kevin Warsh said inflation expectations have eased, reducing urgency to hike, while reaffirming a focus on price stability.
- UK 10-year gilt yields traded just below 4.8%, with dovish BoE signals and soft US jobs data curbing hike expectations, though yields were still up about 6 bps on the week amid repositioning and higher Japanese long-term yields. BoE Governor Bailey flagged a slowing economy, sees inflation returning to 2% later than expected, and ruled out near-term cuts. US payrolls rose 57,000, with unemployment at 4.2% on lower participation.
- Germany’s 10-year Bund yield rose to 2.93%, its first weekly gain since early June and up about 9 bps, as traders reversed part of the post–US-Iran deal drop and higher Japanese long-term yields added pressure. Yields remain below May peaks, with softer inflation (headline 2.8%, core 2.4%), lower oil, and dovish ECB signals reducing odds of a third hike, though a second is still seen as likely. A weak US jobs report also dampened near-term Fed hike expectations.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.