
Access all our platforms from a single account.

Asia Market Quick Take – 02 February 2026

Key points:
- Macro: Trump nominates Kevin Warsh as next Fed chair. PPI hotter than expected
- Equities: Apple rises 0.5% on earnings
- FX: USD strengthens after Fed nomination
- Commodities: Metals plunge with Silver closing 25% lower
- Fixed income: Treasuries rise after Warsh nominated as Fed chair
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Trump nominated Kevin Warsh to replace Fed Chair Powell, a choice seen by markets as supporting a more disciplined and cautious approach to easing.
- US producer prices rose 0.5% in December, surpassing expectations. Services rebounded and nonferrous metals surged, while diesel fell. Core PPI climbed 0.7%. Annual inflation remained at 3%, and core inflation increased to 3.3%, both above forecasts.
- China's Manufacturing PMI dropped to 49.3 in January 2026 from 50.1, missing expectations. Factory activity weakened with contracting new orders, slower output, and declining foreign sales. Input prices rose faster, selling prices increased again, and business confidence hit a six-month low.
Equities:
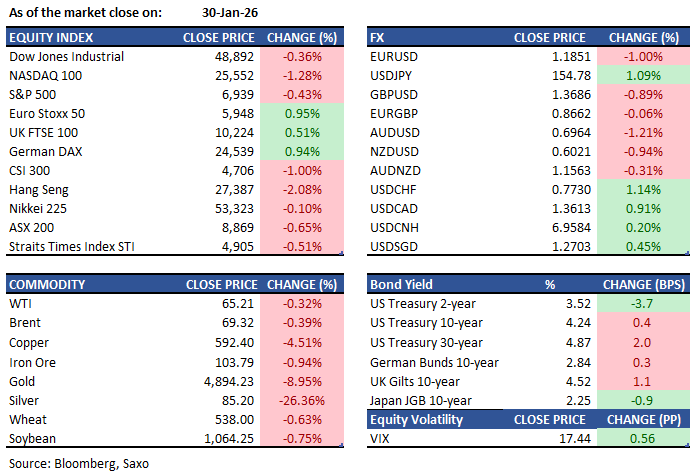
- US - Stocks fell on Friday, with the S&P 500 and Dow down 0.4% and Nasdaq dropping 1.3%, due to higher Treasury yields and a stronger dollar after Trump's nomination of Kevin Warsh as Fed Chair. This led to caution in easing and pressured rate-sensitive sectors. Materials, tech, and communications lagged, while healthcare did better. Apple edged up 0.5%, Visa fell 2.9%, ExxonMobil dropped 0.7%, Chevron gained 3.3%, American Express slipped 1.8%, and Verizon jumped 11.8%. Despite this, the S&P 500 rose 1.2%, Dow 1.6%, and Nasdaq 1.1% in January.
- EU - European stocks ended January sharply higher as improving Eurozone growth supported sentiment. The STOXX 50 rose 0.8% and the STOXX 600 gained 0.5% after GDP data showed the region grew 0.3% in Q4, beating expectations and signaling economic traction despite recent uncertainty. Banks and tech led the rebound, with Deutsche Bank, Intesa Sanpaolo, ASML and SAP up 2%–4%. Adidas jumped 4% on record 2025 revenues. In contrast, mining stocks lagged, with Anglo American, Glencore and Rio Tinto falling around 2.5%–2.7% as investors trimmed metals‑related bets.
- HK - HSI dropped 581 points, or 2.1%, to 27,387, ending a seven-day rise due to U.S. futures slump before Trump's Fed Chair decision. Consumer and tech sectors fell over 2%. CK Hutchison fell 4.8%, while Zijin Gold, Zhaojin Mining, CSPC Pharma, and Geely Auto were major losers. Despite this, the market gained 2.4% weekly and 6.9% monthly, boosted by property sector recovery in Hong Kong. China may issue CNY 200 billion in bonds to recapitalize insurers.
Earnings this week:
- Monday: Disney, Palantir, Aptiv, Teradyne, IDEXX Laboratories, NXP
- Tuesday: PayPal, AMD, PepsiCo, Supermicro, Merck, Chipotle, Pfizer, Lumentum, Amgen, ADM, EQT
- Wednesday: Uber, Alphabet, Lilly, ARM Holdings, Boston Scientific, Qualcomm, Johnson Controls, AbbVie, Snap, Symbotic, Amcor, CME Group, UBS
- Thursday: ConocoPhillips, Amazon, Energizer, Strategy Blocks, Shell, Roblox, Reddit, Cigna, Estee Lauder, Affirm
- Friday: Centene, Canopy Growth, Cboe, Biogen, Nvent, Under Armour, Toyota
FX:
- USD strengthened following Trump's nomination of Warsh for Fed Chair, easing independence concerns. Warsh's reformist views may face peer challenges. December PPI was hotter than expected. Fed officials discussed labor risks and low inflation. The DXY rebounded to 97.06 from lows of 95.55.
- USDJPY remains mostly unchanged at 154.96 after a 1.1% increase on Friday, reducing its overall weekly decline to 0.6%.
- AUDUSD is 0.1% lower at 0.6955, following a 1.2% drop on Friday, moderating its weekly gain to 1%. NZDUSD shows a similar 0.1% decline at 0.6015, after a 0.9% decrease on Friday, bringing its weekly gain down to 1.2%.
- EURUSD is steady at 1.1849, with a 1% fall on Friday turning into a weekly loss of 0.2%. Meanwhile, GBPUSD is 0.1% higher at 1.3698, having slid 0.9% on Friday, trimming its weekly gain to 0.3%.
Commodities:
- Silver fell over 35% to $75 per ounce Friday, retreating from a record $122 amidst profit-taking. Despite this, it's set for a monthly gain over 30% due to uncertainties, a weaker dollar, and strong demand. Geopolitical tensions rose with Trump's tariffs on oil suppliers to Cuba and his call for nuclear talks with Iran. Trump also nominated Kevin Warsh as Fed chair. Gold slid 14% to below $4,800.
- WTI crude fell nearly 3% to $63 per barrel Monday after Trump talked of serious negotiations with Iran. Previous price rallies stemmed from US-Iran tensions, Strait of Hormuz concerns, and geopolitical issues in Venezuela, Kazakhstan, and Russia.
Fixed income:
- Treasuries dropped initially on news of Trump's nomination of Warsh for Fed Chair. T-Notes hit 111-17+ amid dollar strength and stock/metal selling. Warsh's hawkish stance on QE prompted a reassessment of Treasury policy support. The short-end later recovered.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.