
You can access all of our platforms from a single Saxo account.

Banks slid, chips climbed, the index did neither - Options Brief - 23 September 2026
Summary: Financials had their worst day since March. The chips extended a six-session run. The S&P 500 finished six hundredths of a point from where it started. What the option market now charges for that arrangement is the interesting part.
The S&P 500 finished Tuesday six hundredths of a point from where it began, at 7,764.64. That is about as close to unchanged as a large index gets.
Underneath it, financials had their worst day since March and the semiconductor complex extended a six-session run. A day like that does not normally produce a flat tape. This one did, because the pieces moved against each other and the sum came to rest.
MARKET REGIME: LOW VOL BULL | VIX 14.21 | TERM STRUCTURE: CONTANGO | SKEW: ELEVATED (144.80) | FRONT-MONTH VIX FUTURES: 17.35
- Correlation did the work. Three-month implied correlation fell 7.66% to 9.53, its lowest since 7 August, while dispersion rose 1.65% to 36.38, its highest since 11 August.
- Index volatility reached the floor of its range. The VIX fell 4.44% to 14.21, the lowest reading in the three months of sessions the volatility store holds, and the one-day measure dropped 11.70% to 8.83.
- Single-name pricing disagrees with the index. The index group’s median implied-volatility rank sits at 12.4, against 36.9 for financials and 55.3 for communication services.
Past performance is not indicative of future results.
Where the week’s range sits
What the option market priced for this week, against where Tuesday left it.
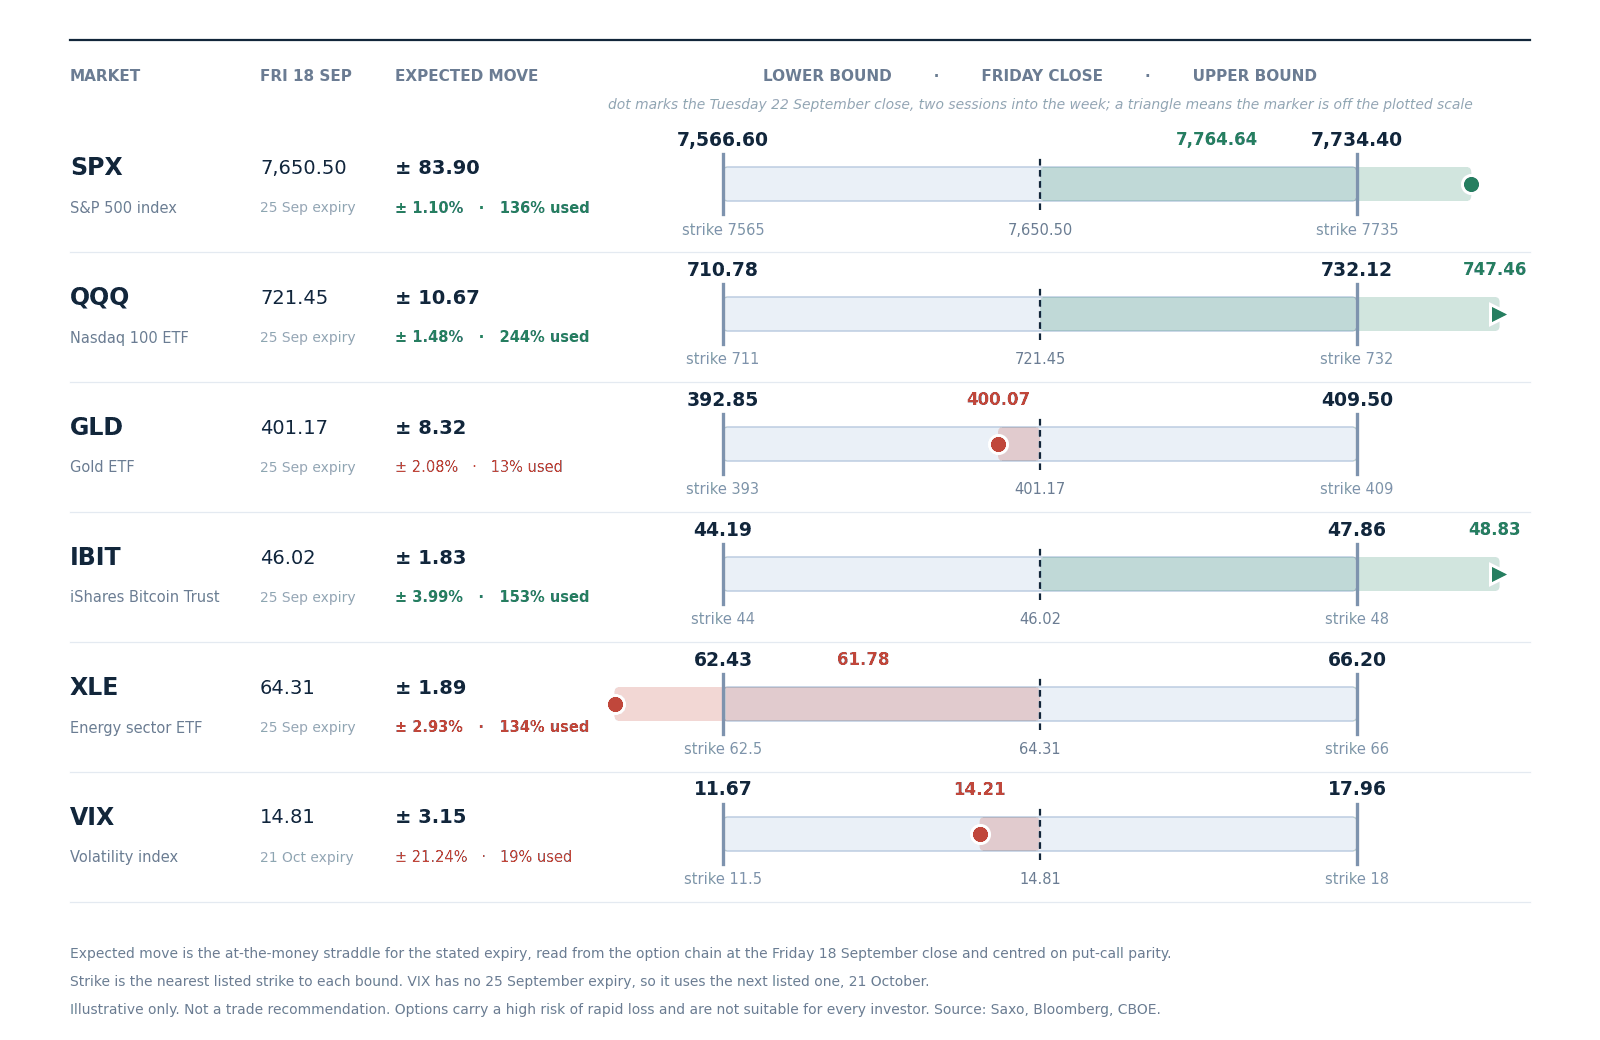 Expected move to the 25 September expiry, drawn around the Friday 18 September close with the nearest listed strike at each bound, and Tuesday’s close marked. Volatility uses the 21 October expiry, so its band covers a month. Read from the chain at Friday’s close and centred on put-call parity, not a forecast.
- Four of the six have now spent the whole week’s range. The S&P 500 sits 136% through its 83.90 point band and the Nasdaq 100 fund 244% through 10.67, both above the upper bound. The bitcoin fund is 153% through, and the energy fund 134% through in the other direction, below its lower bound.
- Only the two slowest movers are still inside. Gold has used 13% of its range and volatility itself 19% of a month-long band. In our view the bands were not badly set in aggregate, but they were set for markets that move together, and these markets may not be doing that. Options carry a high risk of rapid loss and are not suitable for every investor; see Saxo pricing for costs and charges on exchange-traded fund trades.
Headline driver
The selling in financials was specific rather than macro. Meta’s Muse agent drew concern that distribution in banking and insurance could be disrupted, and JPMorgan and the large insurers led the sector down about 2%, its weakest session since March.
Money moved rather than left. Shopify rose around 7% on moving quickly to integrate Muse, and Intel, Advanced Micro Devices and Arm Holdings advanced alongside it.
Crude fell for a sixth consecutive session, with front-month WTI under USD 90 and Brent at 98.23, after Washington and Tehran described a productive meeting and Saudi Arabia moved to restore exports through its East-West pipeline. Copper set a record above USD 6.90 per pound before easing to 6.82. More in Saxo’s macro coverage and today’s Market Quick Take.
Market snapshot
- US (Tuesday 22 September close): S&P 500 7,764.64, unchanged on the session. The Nasdaq 100 rose 0.82% to 30,732.40, a first record close since June, while the Dow fell 0.36% to 51,869.20 and the Russell 2000 added 0.51%. Financials were the weakest sector at roughly 2% lower. The gold miners fund gained 3.60%, the biotechnology fund 2.30% and the semiconductor fund 1.92%, against the financials fund at 1.97% lower.
- Europe (Tuesday 22 September close): the Stoxx 600 added 0.13% to 642.79, its best close since 8 September, led by technology. The DAX was little changed at 25,578.85 and the FTSE 100 fell, weighed by banks.
- Asia (Wednesday 23 September session, in progress): the Hang Seng is 0.78% lower at 24,891.16 and the CSI 300 0.50% lower. The Kospi opened close to 2% higher and gave most of it back, standing at 7,039.33, up 0.31%. Japan is closed for a public holiday.
- Commodities and rates: gold near USD 4,380, holding its established range, and silver at 67.08. WTI 89.33, down 1.31%. The US 10-year yield ended near 4.96% and the 2-year near 4.75% after a choppy session that tracked crude. EURUSD 1.1428, USDJPY 157.67.
- Market regime: Low Vol Bull, VIX 14.21, with the S&P 500 1.82% above its 50-day moving average and 20-day realised volatility at 10.3%, falling.
Data source: Saxo, Bloomberg, CBOE, as of 23 September 2026, approximately 06:00 CET. Past performance is not indicative of future results.
Options flow sentiment
Based on end-of-day 22 September, Tuesday’s positioning and not today’s price action.
- Single-name flow gave no readable direction. The headline share of call premium across mega-cap technology and semiconductors is an artefact of long-dated deep in-the-money stock-replacement activity crossed at the mid with no aggressor. Where a side is legible it leans the other way, with the cleanest bought prints in downside protection across memory and semiconductor names, laid on into the rally rather than chasing it. Financials were flat despite the sector’s move, with bought upside and bought downside splitting evenly.
- Sector and ETF flow looked like inventory rather than opinion. Index activity concentrated in paired at-the-money legs at the December quarterly and one large mid-market package, which is volatility exposure rather than directional risk. Metals, energy and rates repeated the pattern, with near-dated upside sold into strength. No tail hedging survived the confirmed-opening filter. Named funds are market context only; see Saxo pricing for costs and charges on exchange-traded fund trades.
Worth stating plainly: the flow shows no index selling against single-name buying and no sector-versus-index rotation, so it does not independently confirm the correlation reading elsewhere in this brief. In our view it is consistent with that reading rather than evidence for it.
Volatility surface - 23 September 2026, approx. 06:00 CET
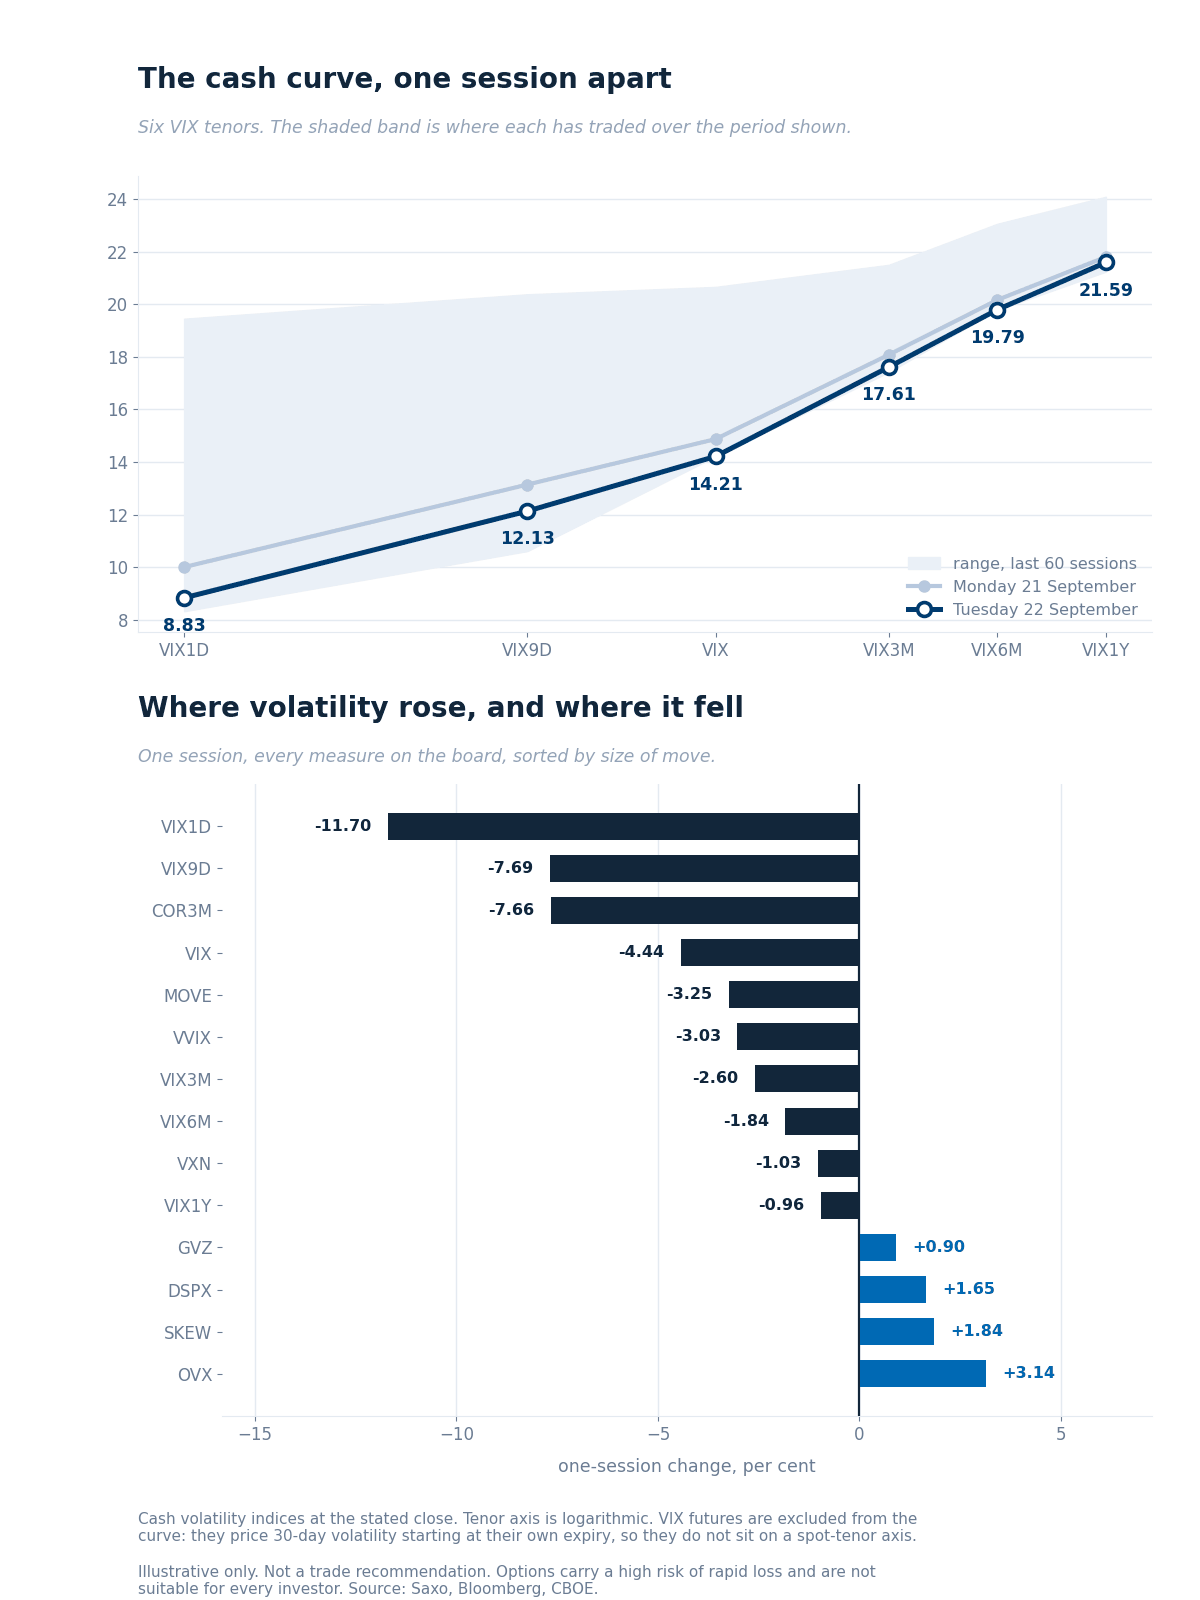 The six cash VIX tenors at Tuesday’s close against the previous session and the range each has held across 60 sessions, with the one-session change across every measure below.
Reading the curve
- Every tenor fell, and the front fell hardest. VIX1D lost 11.70% to 8.83 and VIX9D 7.69% to 12.13, against 0.96% at the one-year point. That pushed the whole curve towards the bottom of its 60-session band while steepening it at the same time.
- Ratios, which the graphic does not carry. VIX3M to VIX at 1.24, a steeper contango than on all but five of the previous 59 sessions. VXN to VIX jumped to 1.42 from 1.30, its widest since 25 August, consistent with a session in which the Nasdaq 100 rose 0.82% and the S&P 500 did not move.
VIX futures
- Front-month 17.35, the October contract, confirmed by put-call parity at 17.405 and consistent to half a basis point across the three strikes nearest the money, so the contract has not rolled. Against a 14.21 cash close that is a premium of roughly 3.14 points, widened from 2.96 a session earlier.
- Second-month 18.18, ratio 0.955, contango. Neither is in the graphic: both price 30-day volatility starting at their own expiry, so neither sits on the spot-tenor axis.
Data source: Saxo, Bloomberg, CBOE, as of 23 September 2026, approximately 06:00 CET. Past performance is not indicative of future results.
Single-name volatility - where implied volatility sits against its own year
Saxo’s implied-volatility rank across 186 US and 335 euro-zone option underlyings, where 0 is a one-year low and 100 a one-year high.
- The typical name barely moved, and the index group is the cheapest corner of the list. On a like-for-like basis the median US name sits at 32.5, against 32.7 a session earlier. The index group’s median rank is 12.4, the lowest of any group on the board, while financials sit at 36.9 and have risen, and communication services at 55.3 and energy at 54.4 are higher still.
- The banks are quietly rich rather than obviously expensive. JPMorgan carries a rank of 43.8 against a percentile of 73.8, Bank of America 41.1 against 74.6 and Morgan Stanley 52.0 against 80.2. Rank measures distance from the year’s extremes; percentile measures how many days looked like today. A rank well below the percentile means implied volatility is modest against a stretched annual range and nonetheless higher than on roughly three-quarters of the past year’s sessions.
- Nvidia is the mirror image, at rank 5.0 and percentile 2.4 after a six-session run in the sector. In our view the split between a floored index reading and mid-range sector readings is the same correlation observation seen from the single-name side. Named funds are market context only; see Saxo pricing for costs and charges.
Data source: Saxo, as of 23 September 2026, reflecting the 22 September close. Day counts are Saxo’s one-year implied-volatility percentile. Past performance is not indicative of future results.
What the market is pricing
- Session implied move. SPX options price about 0.38% to tonight’s close, roughly 30 points, derived from at-the-money option pricing rather than any forecast. The cash session runs 15:30 CET to the 22:00 CET close, so the US purchasing managers’ figures at 15:45 CET and the weekly energy inventory report at 16:30 CET both fall inside the expiry.
- Event implied range. Friday’s expiry prices 0.73%, about 57 points. The same expiry carried 0.91% in yesterday’s edition with one more session to run, and flat volatility with one session less would have left roughly 0.79%. About 7% has come out on top of what the clock explains, which is forward risk being priced down rather than merely running off.
- Correlation read. Implied correlation at 9.53 and dispersion at 36.38 put a very low price on the market moving as one. In our assessment that is a specific bet, it is the bet a session like Tuesday pays, and it may be the bet that fails first if a single catalyst starts moving every sector the same way.
- Tail risk signal. SKEW firmed 1.84% to 144.80, high against its long-run history though only mid-range against the last three months, with 34 of the previous 59 sessions higher. In our view the combination of a floored index measure and a firm tail describes a market relaxed about ordinary movement and still paying for protection against the unusual kind.
Options carry a high risk of rapid loss and are not suitable for every investor. Past performance is not indicative of future results.
Today’s catalysts
September purchasing managers’ indices for France, Germany, the euro area and the UK arrive between 09:15 CET and 10:30 CET, all ahead of the 15:30 CET US equity open.
Inside the session, the US September purchasing managers’ indices land at 15:45 CET and the weekly US crude and fuel stocks report at 16:30 CET. The industry estimate pointed to a 1.8 million barrel build in crude with gasoline and distillate drawing down, and crude is already six sessions lower.
Cintas and Paychex report today, Costco and H&M tomorrow. Xi Jinping’s Washington visit continues, covering trade, artificial intelligence and geopolitics, with expectations for a breakthrough low. Euro area consumer confidence fell to -16.5 in September from -15.5, breaking a four-month run of improvement, and Australia’s flash manufacturing survey slipped into contraction at 49.3. Future outcomes are uncertain and may result in losses.
Conclusion
Tuesday was a session in which the index told you almost nothing and the sectors told you a great deal. The option market has priced that arrangement into everything: index volatility at the bottom of its three-month range, implied correlation near a six-week low, dispersion near a six-week high, and single-name ranks several times the index reading.
The arithmetic works while the offsetting continues. Four of six markets have already run through the range priced for the whole week with two sessions still to go.
In our view today’s purchasing managers’ figures are the first catalyst this week with the reach to move every sector in the same direction at once, and that may be the specific event this configuration is least prepared for. Options carry a high risk of rapid loss and are not suitable for every investor. Past performance is not indicative of future results.
Important note: The strategies and examples provided in this article are purely for educational purposes. They are intended to assist in shaping your thought process and should not be replicated or implemented without careful consideration. Every investor or trader must conduct their own due diligence and take into account their unique financial situation, risk tolerance, and investment objectives before making any decisions. Remember, investing in the stock market carries risk, and it’s crucial to make informed decisions.
| More from the author |
|---|