
You can access all of our platforms from a single Saxo account.

Asia Market Quick Take – 14 October, 2026

Key points:
- Macro: Tensions continue between Houthis and Saudi. Iran steps up attacks on tankers
- Equities: Chips slide. Banks reported earnings. Microsoft closed at record high
- FX: USD weakened on lower yields; AI-driven equity rout pressured Asian currencies
- Commodities: Precious metal remain under selling pressure
- Fixed income: Treasuries rally led by long end of the curve
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Fed: NY Fed President John Williams said one more rate hike is appropriate this year but does not believe further tightening will be necessary in 2027. White House NEC Director Kevin Hassett added it is "very possible" the Fed could hold if inflation data continues to slow.
- US Data (Tuesday): US existing home sales rose 1.5% to a 3.99 million annual rate in September, slightly above the 3.95 million estimate. NFIB small-business optimism slipped 0.8 points to 97.9, a three-month low. Redbook same-store sales surged over 10% YoY in the week ended Oct. 10.
- Germany CPI: Final September harmonised CPI confirmed at +3.3% YoY, up from 2.9% in August, reinforcing sticky inflation concerns in the eurozone's largest economy.
- IMF Warning: The IMF flagged surging government bond yields as the biggest emerging risk to the global financial system. Ray Dalio separately warned the US bond selloff has a "long way to go."
- The IMF now sees global growth at 3.1% in 2026 and 3.4% in 2027, supported by resilient advanced economies and AI investment but constrained by high energy prices. Forecasts: US 2.3% in 2026–27; China 4.5% then 4.0%; Japan 0.7% both years; India 7.0% both years; eurozone 1.1% then 1.2%; UK 1.3% then 1.2%.
- BOJ: Bank of Japan officials are reportedly leaning against a back-to-back rate increase this month, according to people familiar with the matter, while eyeing a potential move as soon as December.
- Houthi militants struck Saudi Aramco’s Dhahran HQ and Riyadh’s airport as a Saudi-led coalition advanced in Yemen. Iran stepped up tanker attacks in the Strait of Hormuz, while the US said it helped move over 19 million barrels of crude. Trump defended his diesel export deal with Russia as a way to boost supply and cut prices.
- Singapore’s MAS unexpectedly held policy, keeping the exchange-rate band’s slope, width and center unchanged, signaling prior tightening may suffice amid oil- and AI-driven inflation. It’s the first pause after April and July hikes.
Equities:
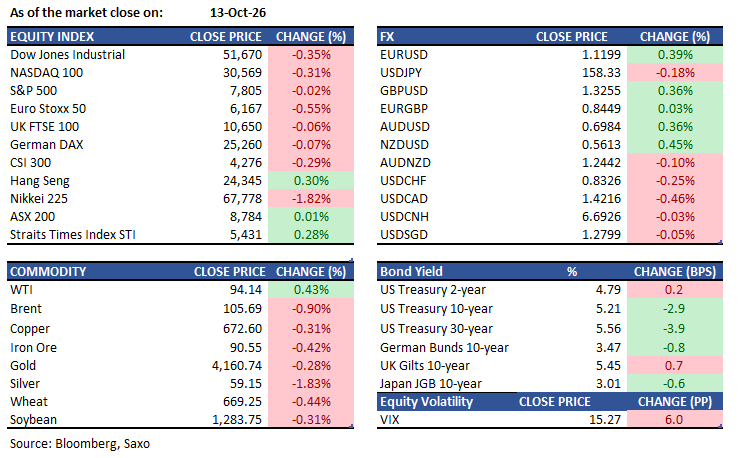
- US — The S&P 500 closed little changed at 7,805.45 on Tuesday, with the Nasdaq 100 down 0.3% and the Dow shedding 180 points. Chipmakers extended their slide for a sixth straight session — Applied Materials fell 6.7% and Micron dropped 3.6% — while Goldman Sachs rose ~3% on strong equity trading revenue. JPMorgan and Wells Fargo were mixed. Microsoft hit a record close. Johnson & Johnson sank ~6%. After hours, Bank of America moved lower following its results.
- EU — The Stoxx 600 closed down 0.1% at 635.01 on Tuesday, erasing gains of as much as 0.7% as tech stocks sold off late in the session. ASML fell 4.2% and ASM International dropped 6.3%, leading the tech subindex down 1.6%. On the positive side, Givaudan surged 9.4% after posting stronger-than-expected growth, and BP advanced 3.7% on guidance flagging a cut in capital expenditure. The DAX closed marginally lower at 25,259.90, weighed by Siemens Energy (-2.5%) and sticky German inflation data.
- Asia — Asian markets were hit hard on Tuesday by the global AI and semiconductor selloff. The Kospi plunged 5.5% at the close (down as much as 7% intraday), with Samsung Electronics and SK Hynix falling ~7% and ~10% respectively — the worst session in 21 months. The Nikkei 225 and Taiwan's Taiex both fell ~2%. The MSCI Asia Pacific Index lost 1.6%, its weakest close since August. Hang Seng and HK markets were also under pressure from the tech rout. The STI was softer. Smoore International fell as much as 16% in HK on VAT rebate cut concerns, and Man Wah Holdings dropped ~14% after flagging a 70–90% profit decline. Futures for Japan and Korea are pointing higher this morning, with analysts flagging Tuesday's Kospi move as a potential capitulation event.
Earnings this week:
- Wednesday: ASML, Bank of America, Morgan Stanley, BlackRock, State Street
- Thursday: Alcoa, Charles Schwab, Interactive Brokers, Prologis, Bank of New York Mellon, US Bancorp, PNC Financial, TSMC
FX:
- USD slipped 0.2% after four days of gains, as a global bond rally pushed the 10-year Treasury yield down to 5.22% and Brent crude fell toward $105/bbl.
- AUD closed 0.4% higher in New York, supported by falling oil prices and improved risk sentiment from the bond rally, though it has broadly stabilized over the past two weeks following the RBA's rate hike.
- JPY gained against the USD but lagged G10 peers. JPY was the laggard among G10 gainers, with USDJPY still elevated at 158.33.
- USDTWD surged 0.74% to 32.158 — the Taiwan dollar's largest single-day drop since June 2025 — driven by a sharp selloff in AI-linked equities following a technology breakthrough announcement by Chinese chipmaker CXMT Corp.
- USDKRW rose 0.49% to 1,342, with the won weakening alongside a Kospi selloff tied to the same AI equity theme.
Commodities:
- Brent crude fell ~1.9% to around $104.64/bbl, pulling back from recent highs near $106, as markets weighed resilient Middle East supply flows against ongoing Houthi attacks on Saudi infrastructure. The Brent-WTI spread remains wide at ~$13, near the widest in over a decade. WTI extended its rally overnight and is trading higher this morning. OPEC cut its demand growth forecast again.
- Gold traded near $4,160–$4,208/oz, holding a modtreaest loss as Middle East tensions stoked inflation fears and kept rate hike expectations elevated. Technical resistance remains firm at $4,300/oz, with support seen at $4,150/oz.
Fixed income:
- The long end rallied, with the 10-year yield falling ~2.7bps to 5.215% and the 30-year dropping ~3.7bps to 5.563%, supported by haven demand from the equity selloff and lower oil prices. The 2s10s curve flattened ~3bps.
- Bearish bond bets dominated options markets ahead of CPI, with standout trades targeting further selloffs in longer maturities. Separately, a buyer of long-bond call spreads targeted a 30-year yield move down to ~5.3%. Asset managers have been deleveraging long-duration Treasury futures positions in recent weeks.
- Eurozone yields fell in tandem with Treasuries. French fiscal and political stress remains a key overhang — a record 56% of European fund managers surveyed by BofA said they would underweight French equities over the next 12 months, with OAT-Bund spreads remaining elevated. The IMF's warning on surging yields added to the cautious tone across global government bond markets.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.
The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.