
Access both platforms from your single Saxo account.

Asia Market Quick Take – 16 September 2026

Asia Market Quick Take – 16 September, 2026
Key points:
- Macro: Saudi cancels September shipments after East-West pipeline shuts
- Equities: Coinbase and Circle fell more than 10% after Clarity Act failed to clear Senate
- FX: Dollar firms into tonight’s FOMC meeting, with a 25bp hike largely priced
- Commodities: US 10-year Treasuries at 2007 highs
- Fixed income: WTI up 4.4%, highest close since mid-May
------------------------------------------------------------------
Disclaimer: Past performance does not indicate future performance.
Macro:
- Saudi Arabia cancelled some September shipments after drone attacks shut its East-West pipeline, with no restart timeline amid renewed Houthi strikes. In Libya, oil output was hit by field and station shutdowns due to protests. Russia struck Kyiv fuel stations and Ukraine hit a Russian refinery, despite Trump’s claim of a mutual halt on energy attacks.
- The UK jobless rate held at 4.9% in the three months to July 2026, defying forecasts of 5.0%. Unemployment rose slightly to 1.78 million, while employment increased by 66,000 to 34.48 million, driven by more full-time jobs. The inactivity rate edged down to 20.9%.
- Germany’s wholesale prices rose 6.8% year-on-year in August 2026, up from 5.3% and the fastest since February 2023, driven by higher energy and raw material costs. Mineral oil products jumped 36.1% and metals 27.4%, while several food categories fell. Month-on-month, prices climbed 0.9%, the quickest in four months and above expectations.
- Japan’s exports jumped 19.3% year-on-year to JPY 10,048.4 billion in August 2026, beating forecasts of 18.2%, marking a 12th month of growth on a weaker yen and strong AI-chip demand, despite Middle East-related supply chain risks.
- Japan’s core machinery orders fell 3.7% m/m to JPY 1,016.9 billion in July 2026, the fourth drop this year and worse than the expected 2.8% decline, with both manufacturing and non-manufacturing orders weaker. Year-on-year, orders rose 11.2%, below the 15.3% forecast and down from 16.9%.
- The Empire State Manufacturing Index fell to 7.6 in September 2026 from 20.6 in August, below expectations of 14.75, signaling softer activity. New orders were flat, shipments slipped, supply conditions worsened, and price pressures rose, but firms stayed optimistic, with the future conditions index at 29.
Equities:
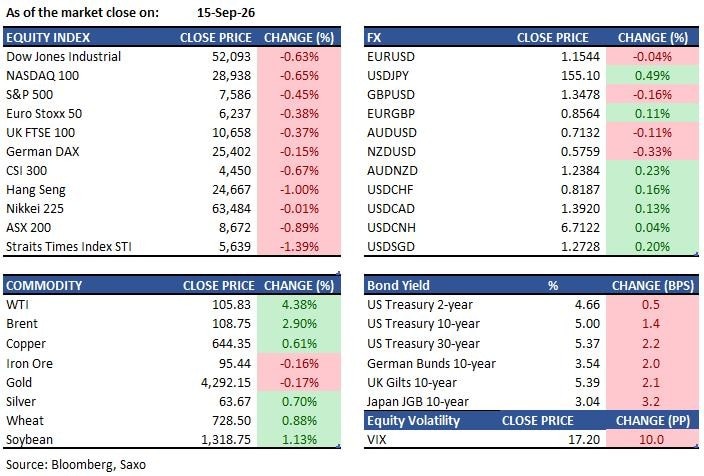
- US — US equities fell on Tuesday as elevated oil prices pushed Treasury yields to multi-decade highs, dampening risk appetite. The S&P 500 closed down 0.45% at 7,585.73, the Dow fell 0.63% to 52,093.11, and the Nasdaq 100 declined 0.65% to 28,937.84. Among Magnificent Seven names, Alphabet and Microsoft led losses, each down over 1% in premarket. The Senate failed to advance the Clarity Act, with the measure falling short in a 50-49 vote. Following the outcome, Coinbase shares declined 10%, while Circle Internet dropped 11%.
- EU — European equities fell on Tuesday, weighed by rising bond yields and elevated oil prices. The Stoxx Europe 600 dropped 0.3% to 634.18, its lowest close since June 12, with banks leading the decline. The FTSE 100 fell 0.4% to 10,658.13, led lower by HSBC (-2.2%) and London Stock Exchange Group (-3.2%). The DAX declined 0.2% to 25,402.28, with Zalando the largest faller at -3.7%. LVMH dropped 2.6%, losing its position as France's most valuable company and exiting Europe's top 10 by market cap. Lanxess fell 5.9% in the Stoxx 600. Grupa Kety was the top riser, up 9.9% after announcing a €645 million acquisition.
- Asia — Asian equities are broadly steady this morning as markets await the Fed decision, with the MSCI Asia index up 0.1%. Hang Seng fell 1.0% on Tuesday to 24,667.24, its lowest close since July 17, led by HSBC (-3.2%) and CATL (-6.0%), with all sectors declining. The Nikkei 225 closed virtually flat on Tuesday at 63,484.10, as AI-related rebounds offset pressure from elevated oil and BOJ rate decision caution ahead of Friday's meeting; the index is down 0.07% this morning at 63,415.20. The Kospi is up 0.10% this morning at 6,634.09, recovering from a 0.9% decline on Tuesday driven by semiconductor weakness — SK Hynix and Samsung fell over 4% on Monday on AI slowdown concerns. Guangzhou Auto surged 16% in Hong Kong on Monday after a joint asset deal with FAW Group. Chinese AI chip stocks rallied on Tuesday after Beijing unveiled a five-year electronics industry plan supporting semiconductors and advanced computing.
Events this week:
- Wednesday: FOMC rate decision
- Thursday: BOE rate decision
- Friday: BOJ rate decision
FX:
- USD is modestly firmer ahead of tonight’s Fed decision, with a 25bp hike almost fully priced and TD flagging scope for a knee‑jerk USD dip on an “as‑expected” outcome.
- EURUSD under pressure: The pair fell below its 100-day moving average at 1.1556 on Monday and has held below it since, with the 55-DMA at 1.1521 acting as near-term support. A close below that level opens the path toward 1.14.
- USDJPY touched as high as 155.43 overnight. US Treasury Secretary Scott Bessent described the recent coordinated yen intervention as "nominal" and framed a stronger yen as beneficial for US exports.
- The PBOC strengthened the yuan fixing for a fifth consecutive day, reportedly aiming to offset dollar gains ahead of an expected Trump-Xi summit later this month. USDCNY is flat on the day at 6.7117.
- GBP volatility measures are near record lows, which some traders flag as a warning sign of complacency ahead of Prime Minister Andy Burnham's first Budget.
Commodities:
- Brent crude settled around $109/bbl on Tuesday, extending September gains to nearly 20%, after talks to establish a temporary shipping lane through the Strait of Hormuz were reportedly postponed. WTI settled up 4.4% on Tuesday at its highest level since mid-May. This morning, Brent is slightly lower at $108.08 (-0.62%) and WTI at $105.12 (-0.67%) as some risk premium is pared back.
- Gold spot is at $4,283.48/oz, down 0.20% this morning, as a stronger dollar and rising real yields weigh on the precious metal. The gold-oil divergence has widened notably this month — Brent's surge has been accompanied by softer gold, higher yields, and a firmer dollar, echoing cross-asset dynamics seen during the early stages of the Iran conflict in March.
Fixed income:
- The 10-year Treasury yield rose as high as 5.04% on Tuesday before closing at 5.00%, the highest level since 2007. This morning the 10-year is at 4.99%, with the 30-year at 5.36%. The move is driven by a combination of surging oil prices, persistent inflation, swelling fiscal deficits, and positioning ahead of today's expected Fed rate hike.
- The 5s30s spread widened to 53.6bps from 52.3bps at the prior close, with the long end underperforming following the weak 20-year auction. The 2-year yield stands at 4.65%, with bond traders positioned in extreme short territory ahead of the Fed, betting the selloff continues.
- The global bond selloff is broadening. The German 10-year Bund yield is at 3.54% and the Japanese 10-year JGB yield is at 3.05%, both at multi-year highs. JGB futures fell 34 ticks overnight, tracking US Treasuries lower, with additional pressure from BOJ rate decision uncertainty ahead of Friday.
For a global look at markets – go to Inspiration.
This content is marketing content and should not be considered investment advice. Trading financial instruments carries risks and historic performance is not a guarantee for future performance.The instrument(s) mentioned in this content may be issued by a partner, from which Saxo receives promotion, payment or retrocessions. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.