Quarterly Outlook

Commodities in the crosshairs of climate and inflation

Ole Hansen
Head of Commodity Strategy

Summary:  The December 6 OPEC+ decision to maintain and deepen production cuts through the first quarter is likely to offset any potential growth concerns or renewed US-China trade worries.

Global commodities face a potentially volatile 2020, given the combination of growth concerns, geopolitical tensions, climate change and inflationary pressures. While global growth — and with that demand for key cyclical commodities — remains weak, we see the supply side also facing multiple challenges due to social unrest and climate change.

Climate change became top of mind in 2019 and we expect this focus will only continue to strengthen as the real impact is felt across the world. Whether these developments will be viewed as a temporary blip 50 years from now is irrelevant. The trend towards a warming atmosphere is likely to see weather become more volatile and unpredictable, thereby creating a challenge to global food supply chains. Already warm regions are getting hotter, while wet regions are getting wetter. 2019 was the year where several weather events ensured these developments received increased attention. 

Increased weather volatility is likely to manifest itself through intense droughts, floods, heatwaves and wildfires, leading to an increase in the rate of soil loss and land degradation. At sea the change may also have a significant impact on fish and shellfish habitats and could disrupt fragile ecosystems. 

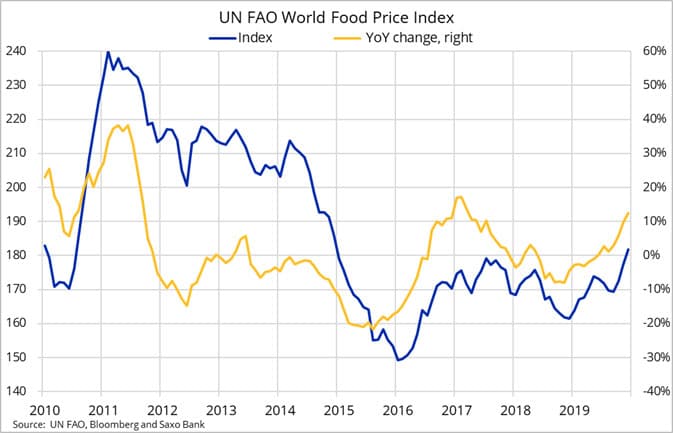
We have witnessed several years of ample supply with stable-to-lowering prices. In fact, the last period of tightness among the key crops was back in early 2010 when soaring wheat prices helped trigger the Arab Spring. While global demand and supply have both risen during the past decade, the global supply chain will be left vulnerable to a sudden weather-related drop in yields. 

The World Food Price Index, published monthly by the UN FAO, rose 12.5% year-on-year in December to reach a five-year high — but still sits significantly below its 2011 peak. The index, which tracks a total of 73 food commodities across five major commodity groups, saw prices rise fastest in vegetable oils (+20%) and meat (+17%). 
OLE chart 1

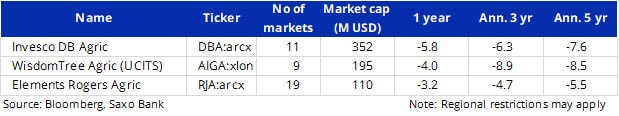
Ample supply and weak price action have resulted in negative returns on most exchange-traded funds with broad-based exposure to key agricultural commodities. The table below highlights three of the biggest ETFs with a diversified agriculture exposure. The chart on all three shows that the decade-long downtrend is now being challenged. Of the major commodities we see sugar, coffee, cocoa and wheat being some of the most exposed to global weather scares.
OLE chart 2

Following years of rangebound trading, we see gold further building on last year’s strong 18.5% gain. This as the technical and fundamental outlook continues to improve.  However, after racing higher at the beginning of January, we may see the metal spend most of the first quarter consolidating above $1500/oz before moving higher to peak at around $1625/oz later in the year. The short-term consolidation also takes into consideration the elevated level of hedge fund positions. These have become quite extended near record levels and, in the short term, could act as a drag on price. 

Geopolitical events such as the early-January US-Iran standoff supported gold but only for relatively short period of time. In order for the yellow metal to climb further, one or more of our below expectations need to be met:  

  • The US Federal Reserve is likely to continue to cut rates while embarking on another round of quantitative easing.

  • Rising inflation, through higher input cost from food and energy driving real bond yields lower. This reduces the opportunity cost associated with holding a non-coupon and non-interest paying asset.

  • Continued buying by central banks looking to diversify and, for some, to reduce the dependency on the dollar (so called de-dollarisation).

  • The dollar is potentially on its final leg of strength before turning lower.

  • Event risks such as renewed US-China trade concerns and the November US elections.  

Brent crude oil is likely to remain stuck in the $60s through the first half of 2020, before moving higher in the second. The December 6 OPEC+ decision to maintain and deepen production cuts through the first quarter is likely to offset any potential growth concerns or renewed US-China trade worries. 

The mid-September drone attack on the world’s biggest processing plant in Saudi Arabia, the conflict in war-torn Libya and the early-January standoff between US and Iran all show just how vulnerable the global supply chain can be. However, with ample availability of strategic reserves in the US, China, Saudi Arabia and IEA countries the fallout from a disruption should be limited and relatively short-lived. 

We see Brent crude oil at $75/b by year-end, as inflation picks up and the dollar weakens. Any short-term weakness, perhaps from speculators exciting speculative long positions, is likely to be limited. With continued threats to supply from the Middle East and Libya, the market is unlikely to reduce by much.   

Get the full report

Disclaimer

Confidentiality and Usage:
You may not reproduce, distribute, or transmit this material or any portion thereof without prior written permission from Saxo.

Nature of Information:
The information provided herein is based on current market conditions and analysts' opinions, which may reflect personal views of the author, and are subject to change without notice. This material does not include a record of any trading prices, or an offer of, or solicitation for, or endorsement to enter into any transaction in any investment product. Any forecast on the economy, markets and economic trends of the markets provided is not necessarily indicative of the future or likely performance of the investment product subject of this material.

Responsibility and Liability:
Saxo accepts no liability for any use that may be made of these comments or for any consequences that arise from such use. Saxo does not guarantee the accuracy or completeness of any information provided and assumes no liability for any errors, omissions, losses, or damages resulting from the use of this information.

The information provided in this material is solely for information only. It is intended for general circulation and does not take into account the specific investment objectives, financial situation or particular needs of any particular person. Accordingly, it should not be relied on or treated as a substitute for specific advice concerning specific situations of any person. Please seek advice from a financial adviser regarding the suitability of any investment product taking into account your specific investment objectives, financial situation or particular needs before you make a commitment to purchase an investment product. In the event that you choose not to seek advice from a financial adviser, you should consider whether any investment product mentioned in this publication is suitable for you.

Notwithstanding the above, insofar as any information provided herein contains research analyses or reports concerning any investment product authored by any foreign research house and is issued or promulgated to a person in Singapore who is not an accredited investor, expert investor, and/or institutional investor, Saxo Capital Market Pte. Ltd. accepts legal responsibility for the contents of this material to the extent required by law. Recipients of such material are to contact Saxo Capital Markets Pte. Ltd. in respect of any matters arising from, or in connection with, this material.

Risk Disclosure:
Trading in investment products involve significant risk, including the risk of losing your entire investment. Historical returns are not a guarantee of future returns. Prices can both rise and fall, and there is a risk that you will not get back the money you invested.

Conflicts of interest:
The author may hold positions in the investment products mentioned. The author does not own positions in the underlying investment product exceeding 0.5% of its market capitalisation, save as otherwise declared. The author is not permitted to trade the mentioned investment products within the first 24 hours after the publication of this article.

Saxo maintains partnerships with companies that compensate Saxo for promotional activities conducted on its platform. Additionally, Saxo has agreements with certain partners who provide retrocession contingent upon clients purchasing specific investment products offered by these partners. While Saxo receives compensation from these partnerships, all content is conducted with the intention of providing clients with valuable options and information.

Publication details:
If any listed companies are the subject of the material, the content has not been submitted to the companies in question prior to publication.

Please refer to our full disclaimer and notification on non-independent investment research for more details.

Saxo Markets
88 Market Street
CapitaSpring #31-01
Singapore 048948

Contact Saxo

Singapore
Singapore

Saxo Capital Markets Pte Ltd ('Saxo Markets') is a company authorised and regulated by the Monetary Authority of Singapore (MAS) [Co. Reg. No.: 200601141M ] and is a wholly owned subsidiary of Saxo Bank A/S, headquartered in Denmark. Please refer to our General Business Terms & Risk Warning to consider whether acquiring or continuing to hold financial products is suitable for you, prior to opening an account and investing in a financial product.

Saxo is part of the J. Safra Sarasin Group.

Trading in financial instruments carries various risks, and is not suitable for all investors. Please seek expert advice, and always ensure that you fully understand these risks before trading. Trading in leveraged products such as Margin FX products may result in your losses exceeding your initial deposits. Saxo Markets does not provide financial advice, any information available on this website is ‘general’ in nature and for informational purposes only. Saxo Markets does not take into account an individual’s needs, objectives or financial situation.

The Saxo trading platform has received numerous awards and recognition. For details of these awards and information on awards visit www.home.saxo/en-sg/about-us/awards.

The information or the products and services referred to on this website may be accessed worldwide, however is only intended for distribution to and use by recipients located in countries where such use does not constitute a violation of applicable legislation or regulations. Products and Services offered on this website are not intended for residents of the United States, Malaysia and Japan. Please click here to view our full disclaimer.

This advertisement has not been reviewed by the Monetary Authority of Singapore.

Apple and the Apple logo are trademarks of Apple Inc, registered in the US and other countries and regions. App Store is a service mark of Apple Inc. Google Play and the Google Play logo are trademarks of Google LLC.